Utah First-Time Home Buyer Programs
Get A Mortgage Loan And Unlock Your First Home in Utah
Buying your first home is life-changing, and it's only natural for you to want to take the big step without any uncertainties. At Summit Lending, we help first-time home buyers navigate the process of finding the best mortgage loan in Utah.
With us, you won't have to worry about struggling with mortgage payments or refinancing in the future. We help you get it right the first time.
Buying your first home in Utah
Your first home purchase is the one with the most unknowns: how much you can really afford, how much cash you need, which loan fits, and which state programs are worth the extra paperwork. Utah has some of the more generous first-time buyer help in the Mountain West, and it is delivered through lenders and brokers rather than directly to buyers. Summit Lending LLC (NMLS 2394434) is a Utah mortgage broker in Garland. We walk first-time buyers through federal loan options and Utah Housing Corporation programs and compare offers from multiple lenders so you can choose with clear numbers.
This guide covers what Utah first-time buyers can use in 2026, how the down payment assistance actually works, a realistic look at the market, and the order of steps that keeps surprises small. When you are ready, start a Utah preapproval or test a payment in the Utah loan calculator.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
What counts as a first-time home buyer
Most programs, including HUD and many state agencies, generally treat you as a first-time buyer if you have not owned a home in the past three years, though each program sets its own definition and exceptions. Some Utah Housing products do not require first-time buyer status at all, which surprises a lot of people. If you owned a home years ago, you may still qualify for first-time programs, and if you own now, you may still qualify for down payment assistance through a repeat-buyer product.
Utah Housing Corporation programs
Utah Housing Corporation (UHC) is the state's housing finance agency. It offers first mortgages and down payment assistance through approved lenders, with income and purchase price limits by county.
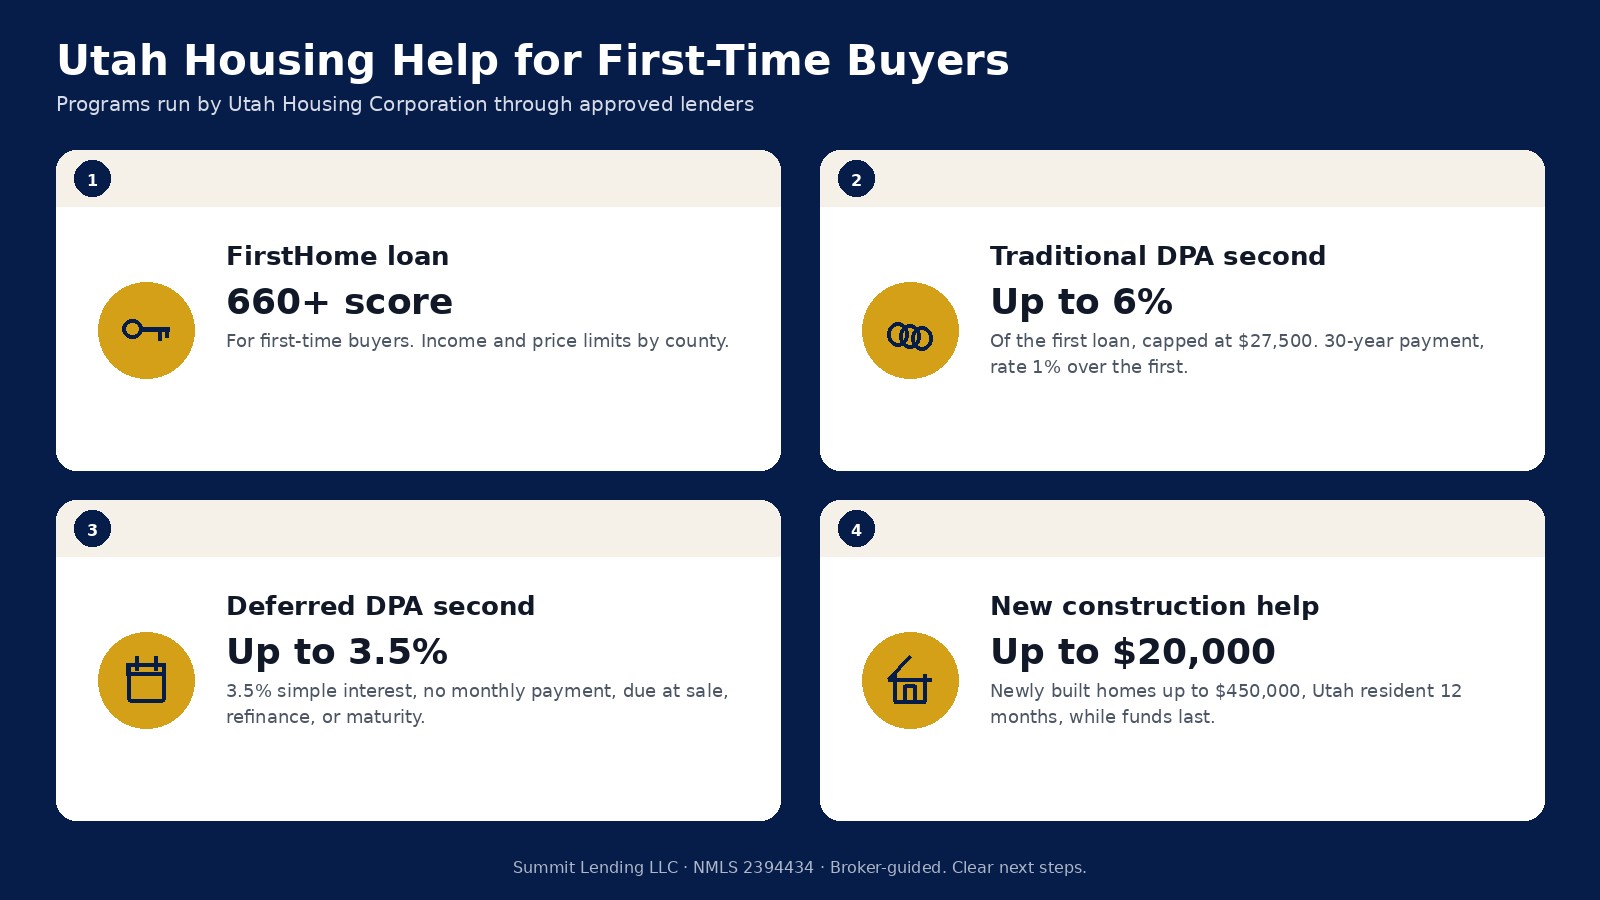
FirstHome loan
FirstHome is UHC's first mortgage for first-time buyers. It requires a credit score of 660 or higher and can be paired with UHC down payment assistance (UHC down payment assistance).
FHA/VA Mortgage and HFA Advantage
UHC's FHA/VA Mortgage, available with a 620 or higher score, and HFA Advantage, a conventional option at 680 or higher, are open to repeat buyers as well as first-timers. They are useful if you do not meet the strict first-time definition or if FHA or conventional fits your credit and debts better.
Down payment assistance second loans
UHC assistance comes as a second mortgage rather than a grant. The traditional version is up to 6% of the first mortgage, capped at $27,500, with a 30-year term and a rate 1% above your first mortgage. That means a monthly payment, but it can cover most or all of the down payment and some closing costs. The deferred version is up to 3.5%, also capped at $27,500, with 3.5% simple interest and no monthly payment; it is repaid when you sell, refinance, or reach the end of the term (UHC down payment assistance).
These programs are heavily used. UHC reports that in fiscal year 2026 it helped 3,236 Utah families, with average down payment assistance of $19,337 (UHC FY2026 report).
First-Time Homebuyer Assistance Program for new construction
Utah also funds a separate program for first-time buyers purchasing a newly built home. It offers up to $20,000 toward a home priced at $450,000 or less that has never been occupied. You must have lived in Utah for at least 12 months and move in within 60 days of closing (UHC program page, program FAQ). The program is set in state law (Utah Code 63H-8-501) and funds are limited, available until they run out, so confirm availability when you go under contract. If you are building rather than buying from a builder, see Utah construction loans.
Homebuyer grant for veterans
UHC also lists a Utah homebuyer grant for veterans of up to $2,500 (UHC grants). It can stack with other help in some cases, so mention your service early.
Federal loan options for first-time buyers
- FHA: 3.5% down with a credit score of 580 or higher, with more flexible debt ratios than many conventional loans (HUD FHA overview).
- Conventional 3% down: Fannie Mae allows up to 97% loan-to-value on eligible fixed-rate purchases (Fannie Mae Eligibility Matrix). PMI applies with less than 20% down and can be cancelled later (CFPB on PMI).
- VA: no down payment for eligible veterans and service members, with no monthly mortgage insurance (VA purchase loans, VA eligibility).
- USDA: no down payment in eligible rural areas for households under the income limit (USDA guaranteed loans). Check addresses on the USDA eligibility map.
The right answer depends on your score, your debts, the home, and how much cash you have. We often price two or three of these side by side for the same house.
A realistic look at the Utah market
The Utah Association of REALTORS reported a statewide median sales price of about $525,000 in August 2026, essentially flat from a year earlier, with roughly 17,274 homes in inventory (UAR market activity). Mortgage rates rose this fall: Freddie Mac's 30-year fixed survey average was 7.28% for the week of October 1, 2026, up from 6.34% a year earlier (Freddie Mac PMMS).
For first-time buyers, that combination means two things. First, the full monthly payment, not the price alone, decides affordability. Second, down payment help and seller concessions are worth more than usual because they reduce the cash you need without stretching the loan. Townhomes and starter homes in areas like West Jordan, Spanish Fork, Tooele, and Brigham City often line up better with UHC price limits than core Salt Lake neighborhoods.
Loan limits are rarely the constraint for a first home, but for reference the 2026 conforming limit is $832,750 in most counties (FHFA) and the FHA one-unit floor is $541,287 (HUD).
Step by step: your first Utah purchase
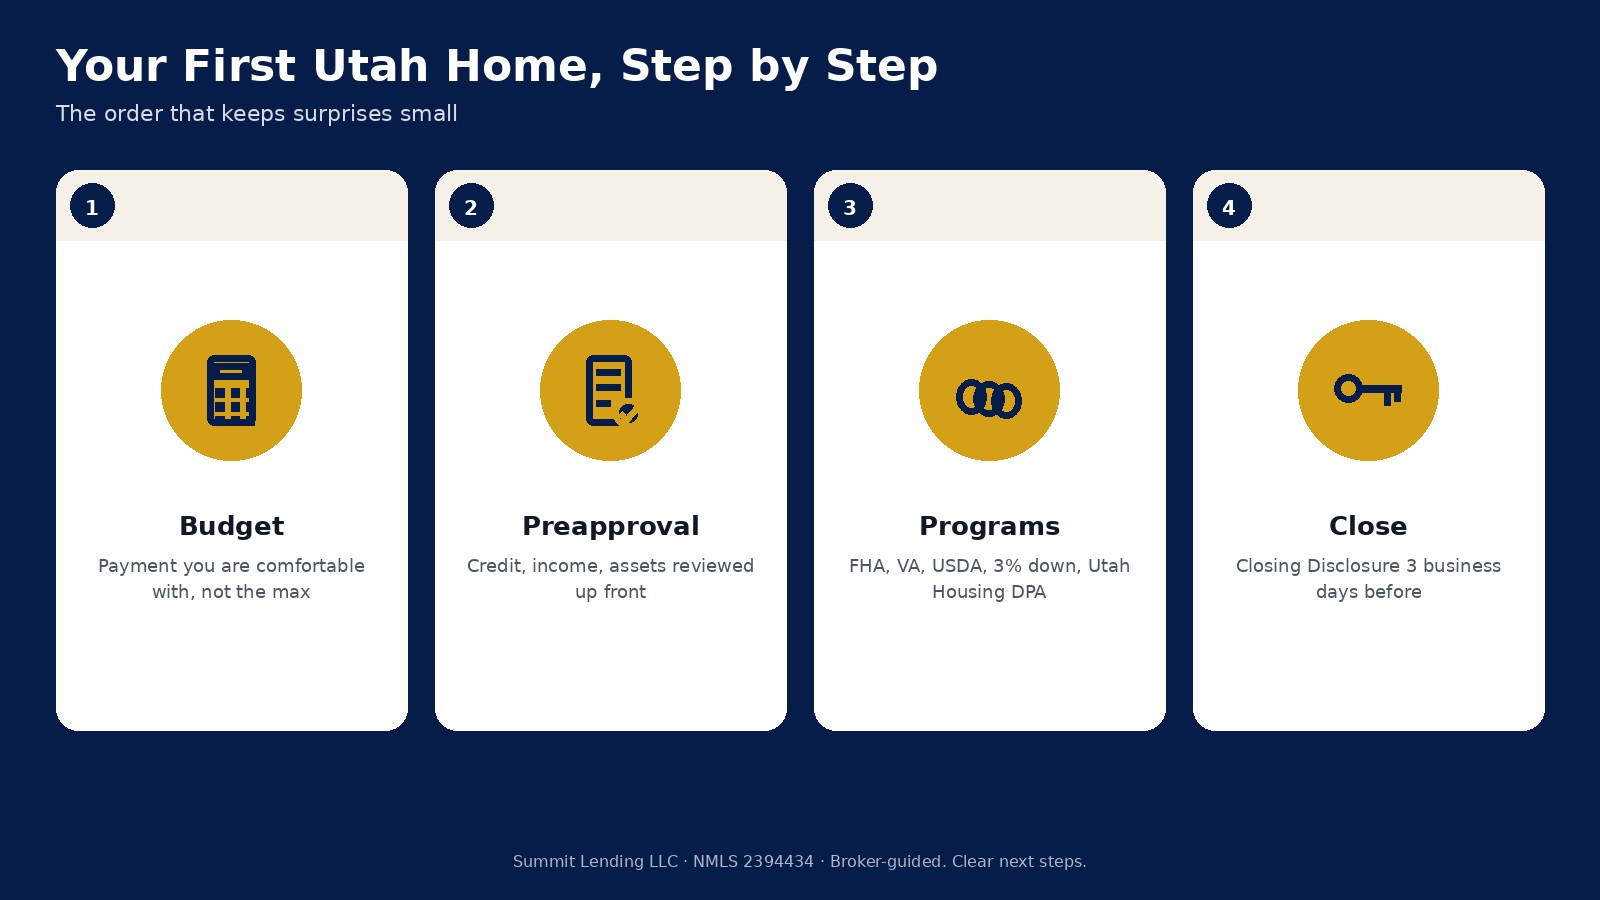
- Set your budget. Decide the monthly payment you are comfortable with, including taxes, insurance, and HOA dues. Lenders look at your debt-to-income ratio (CFPB on DTI), but your own comfort level matters more.
- Take homebuyer education. Many UHC loans require it, and it is useful anyway. HUD lists approved housing counselors (HUD counseling).
- Get preapproved. Lenders use the terms prequalification and preapproval differently, the CFPB notes, so ask what was verified (CFPB comparison). A letter based on reviewed credit and documents gives sellers more confidence. Start on Utah preapproval.
- Choose the program. We compare FHA, conventional, VA, USDA, and UHC options with and without down payment assistance.
- Shop and make an offer. Ask your agent about seller-paid closing costs. In a flat market, sellers often negotiate.
- Compare Loan Estimates. Lenders must send one within three business days of your application (CFPB on Loan Estimates).
- Close. Your Closing Disclosure arrives at least three business days before signing (CFPB on Closing Disclosures). We check it with you line by line.
The CFPB's buying guide is a good free companion for every step (CFPB Buying a House).
Common first-time buyer mistakes we help Utah buyers avoid
- Opening new credit or financing furniture before closing. Lenders recheck credit before funding (CFPB).
- Assuming down payment assistance is free money. Most UHC assistance is a second loan, and the traditional version has a monthly payment.
- Comparing only interest rates. Points, lender fees, and mortgage insurance can make a lower rate more expensive.
- Waiting on state help that has limited funds. Ask about availability the moment you are under contract.
First-time buyer help across Utah
Local guides are available for Salt Lake City, West Jordan, South Jordan, Lehi, Orem, Provo, Ogden, and Layton, plus Salt Lake County, Utah County, Davis County, Weber County, Cache County, Box Elder County, and Washington County. In smaller markets see Tremonton, Cedar City, Heber City, and American Fork.
Related pages
See Utah purchase loans for every loan type, Utah construction loans if you want to build, and Utah mortgage loans for the state overview. Buying in another state we serve? See first-time buyer guides for Idaho, Texas, and Wyoming, or the national first-time home buyer page.
Sources
- Utah Housing Corporation, down payment assistance
- Utah Housing Corporation FY2026 report (PDF)
- Utah Housing, First-Time Homebuyer Assistance Program (new construction)
- Utah Housing, FTHB assistance FAQ (PDF)
- Utah Code 63H-8-501
- Utah Housing Corporation, grants
- HUD, Let FHA loans help you
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- VA purchase loan
- VA home loan eligibility
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- Utah Association of REALTORS market activity
- Freddie Mac PMMS, Oct 1, 2026 release
- FHFA, 2026 conforming loan limits
- HUD No. 25-145, 2026 FHA loan limits
- CFPB, debt-to-income ratio
- HUD housing counseling
- CFPB, prequalification vs. preapproval
- CFPB, What is a Loan Estimate?
- CFPB, What is a Closing Disclosure?
- CFPB, Buying a House
- CFPB, when a lender checks your credit
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.
Our Process Is Straightforward
With Summit Lending, you can be rest assured that our mortgage loan experts will guide you throughout the process, from exploring your loan options to approval.