Texas Mortgage Loans with Hands-On Broker Guidance
Texas mortgage loans with broker guidance across the major metros
Texas is not one housing market. A first home in San Antonio, a refinance in Dallas-Fort Worth, a build in the Houston suburbs, and a purchase in Austin all ask different questions of a loan. Summit Lending LLC (NMLS 2394434) helps Texas borrowers compare purchase, refinance, construction, reverse, and commercial options with payment and cash-to-close numbers before they commit.
We are licensed in Texas and five other states (Utah, Idaho, Wyoming, Arkansas, and Arizona), based at 4542 W 14800 N, Garland, UT 84312. Call 385-200-1470 or email [email protected].
What the Texas market looks like in mid-2026
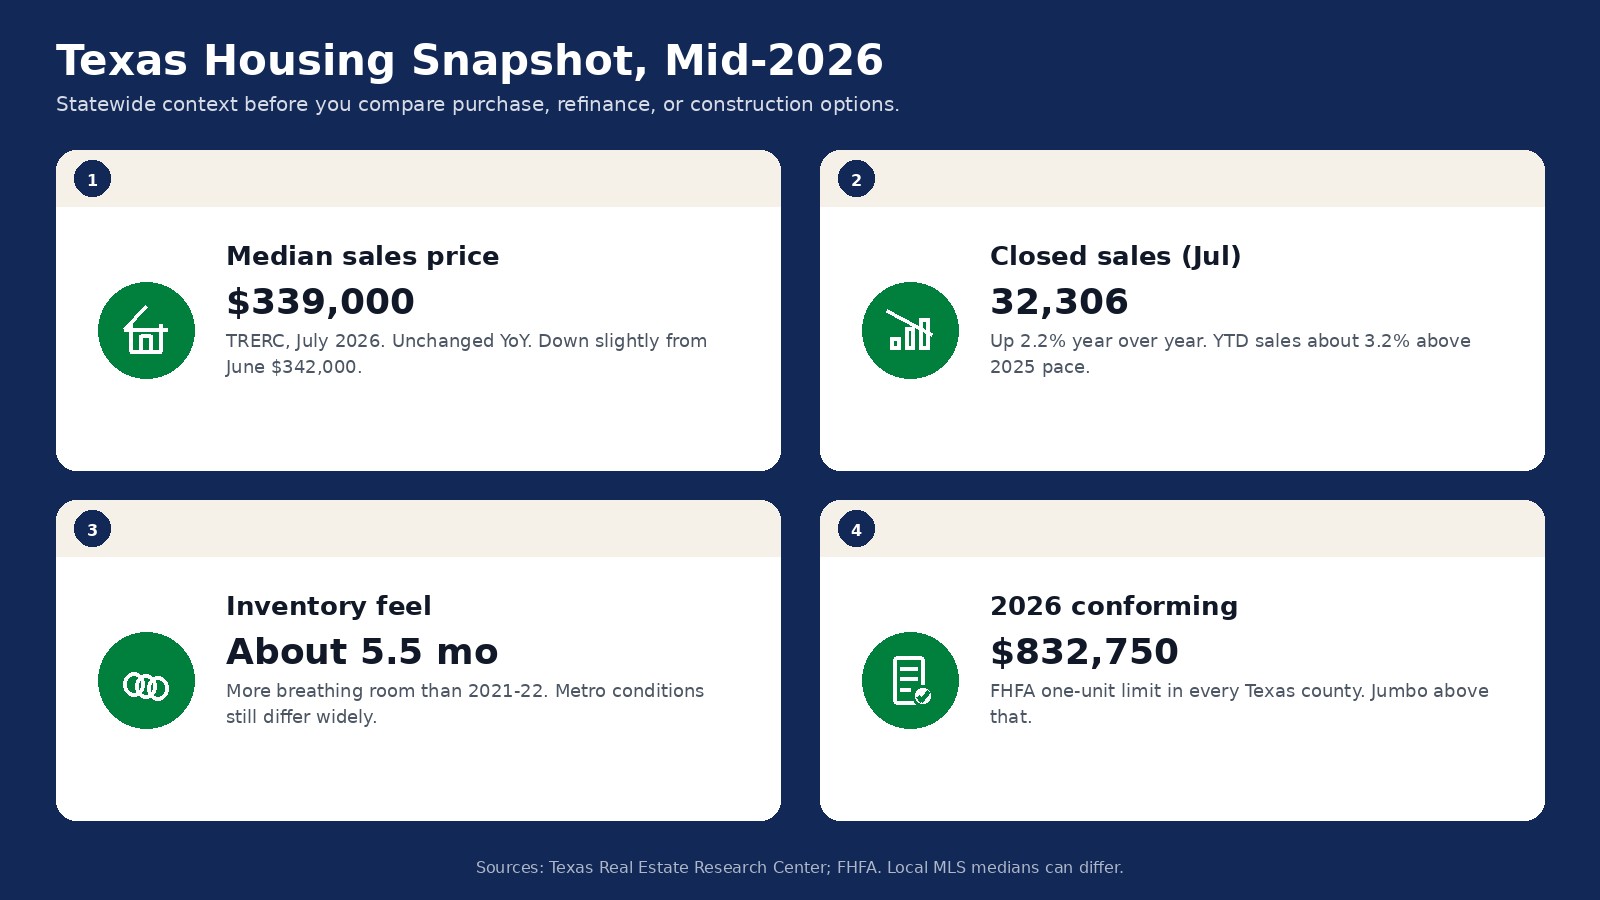
The Texas Real Estate Research Center reported a statewide median sales price of $339,000 in July 2026, unchanged from a year earlier and slightly below June's $342,000. Closed sales totaled 32,306 in July, up 2.2% year over year, with year-to-date sales about 3.2% ahead of 2025. Inventory has been closer to a balanced 5+ months in many areas than the ultra-tight conditions of 2021-2022, though metro results still diverge.
Redfin's June 2026 statewide median was about $347,911. FHFA's 2026 one-unit conforming limit is $832,750 in every Texas county. Freddie Mac's 30-year fixed survey average was 7.28% for the week of October 1, 2026. Survey averages are modeling context, not Summit Lending quotes.
Texas mortgage options we help with
- Texas purchase loans for Conventional, FHA, VA, and USDA structures when you qualify. National overview: purchase loans.
- Texas refinance for payment reduction, shorter terms, cash-out, or leaving an ARM. See also refinance.
- Texas construction loans with one-time and two-time close paths. Builders: Builder Portal.
- Texas first-time home buyer and Texas preapproval.
- Texas reverse mortgages for homeowners 62+ and Texas commercial loans for investment and business-use property.
Texas county and city starting points
- Houston area: Harris County, Houston, plus construction pages like Harris County construction
- Dallas-Fort Worth: Dallas County, Tarrant County, Collin County, Dallas, Fort Worth
- Austin area: Travis County, Austin, Travis County construction
- San Antonio area: Bexar County
Homestead and closing rules in Texas can affect cash-out and renovation transactions. Your title company or attorney confirms the details for your file; we flag the issues early so timelines stay honest.
Buying or refinancing in Texas: practical steps
- Start with Texas preapproval so your letter matches verified income and credit
- Model taxes and insurance for the county you are shopping, not a national average
- Compare programs on the same house with the Texas mortgage calculator
- If you are building, decide early between one-time and two-time close on Texas construction loans
Related Summit pages: all mortgage loans, Utah mortgages, Idaho mortgages, and Wyoming mortgages.
Metro notes Texas buyers ask about
Houston and the coastal counties bring flood-zone insurance questions into almost every purchase conversation. Budget for the right flood policy early when the property needs it.
Dallas-Fort Worth still sees strong migration into Collin, Denton, and Tarrant corridors. Comps move quickly; a verified letter helps you compete without overreaching.
Austin and Travis County remain relatively expensive versus the statewide median, so conforming versus jumbo planning matters sooner.
San Antonio and Bexar County often give first-time buyers more payment room than Austin, but taxes and insurance still need local quotes.
Working with Summit Lending from out of state
Many Texas buyers relocate from Utah, Idaho, or elsewhere in our footprint. We can start preapproval before you travel for a tour weekend, coordinate with your Texas agent, and keep document collection remote. If you are selling a home in another licensed state to buy in Texas, we can discuss both sides of the move.
Insurance and escrow realities in Texas
Wind, hail, and flood pricing can move a Texas payment as much as a quarter-point rate change. Get insurance quotes early, especially along the Gulf Coast and in wildland-urban areas. Escrow shortages after the first year are often an insurance or tax estimate problem, not a lender surprise.
Information on this page is for general education. It is not a commitment to lend. Loan availability, terms, and pricing depend on your credit, income, assets, property, and lender overlays. Summit Lending LLC, NMLS 2394434.
Frequently Asked Questions
Everything you need to know about home mortgage loans in TexasYour ideal loan depends on several factors like your financial situation, long term goals, and risk tolerance. Fixed rate mortgages offer stability, while adjustable rate loans may save you money initially. Government-backed options can be great for those with lower credit scores. At Summit Lending, we’ll guide you through the options to find a perfect fit.
Related Articles
Texas Property Taxes and Home Insurance: Budgeting the Real Mortgage Payment (Oct 2026)
Texas property tax bills go out in October, Harris and Dallas counties just raised rates, and TDI shows insurers filing for lower rates on average. Here is how the $140,000 homestead exemption, escrow, and insurance shape the payment you will actually make.
Texas Buyer's Market at 7.40%: How to Negotiate Price Cuts, Seller Credits, and Buydowns (Oct 2026)
Freddie Mac's 30-year average hit 7.40% on Oct. 8, while 69% of Texas Realtors say their buyers faced no competing offers this year. Here is how a price cut, seller credit, and rate buydown compare on an Austin-area home, plus the Texas contract tools that protect you.