Texas First-Time Home Buyers
Get A Mortgage Loan And Unlock Your First Home in Texas
Buying your first home is life-changing, and it's only natural for you to want to take the big step without any uncertainties. At Summit Lending, we help first-time home buyers navigate the process of finding the best mortgage loan in Texas.
With us, you won't have to worry about struggling with mortgage payments or refinancing in the future. We help you get it right the first time.
Buying your first home in Texas
Texas has more ways to help a first-time buyer than most states, and that is both good news and a source of confusion. Two state agencies run down payment programs, there is a federal tax credit you can pair with them, and the rules differ on who counts as a first-time buyer. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed in Texas. We compare loans from multiple wholesale lenders and help first-time buyers sort out which programs fit, before they fall in love with a house.
To see a payment first, use the Texas mortgage calculator. When you are ready, start a Texas preapproval.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
What first-time buyers face in Texas this fall
Redfin put the Texas statewide median sale price at about $333,611 for August 2026, down 1.3% from a year earlier, with roughly 180,524 homes for sale, about six months of supply. The typical home took around 68 days to sell (Redfin Texas data). That is a more balanced market than Texas buyers saw a few years ago, and it often means room to ask for seller help with closing costs.
Rates are the harder part. Freddie Mac's survey put the 30-year fixed average at 7.28% for the week of October 1, 2026, compared with 6.34% a year ago (Freddie Mac PMMS). On a $335,000 home with 3.5% down on FHA, principal and interest alone, with the upfront FHA premium financed, would be about $2,251 a month before taxes, insurance, and monthly mortgage insurance. Property taxes in Texas can add a lot, so get the rate for the exact address.
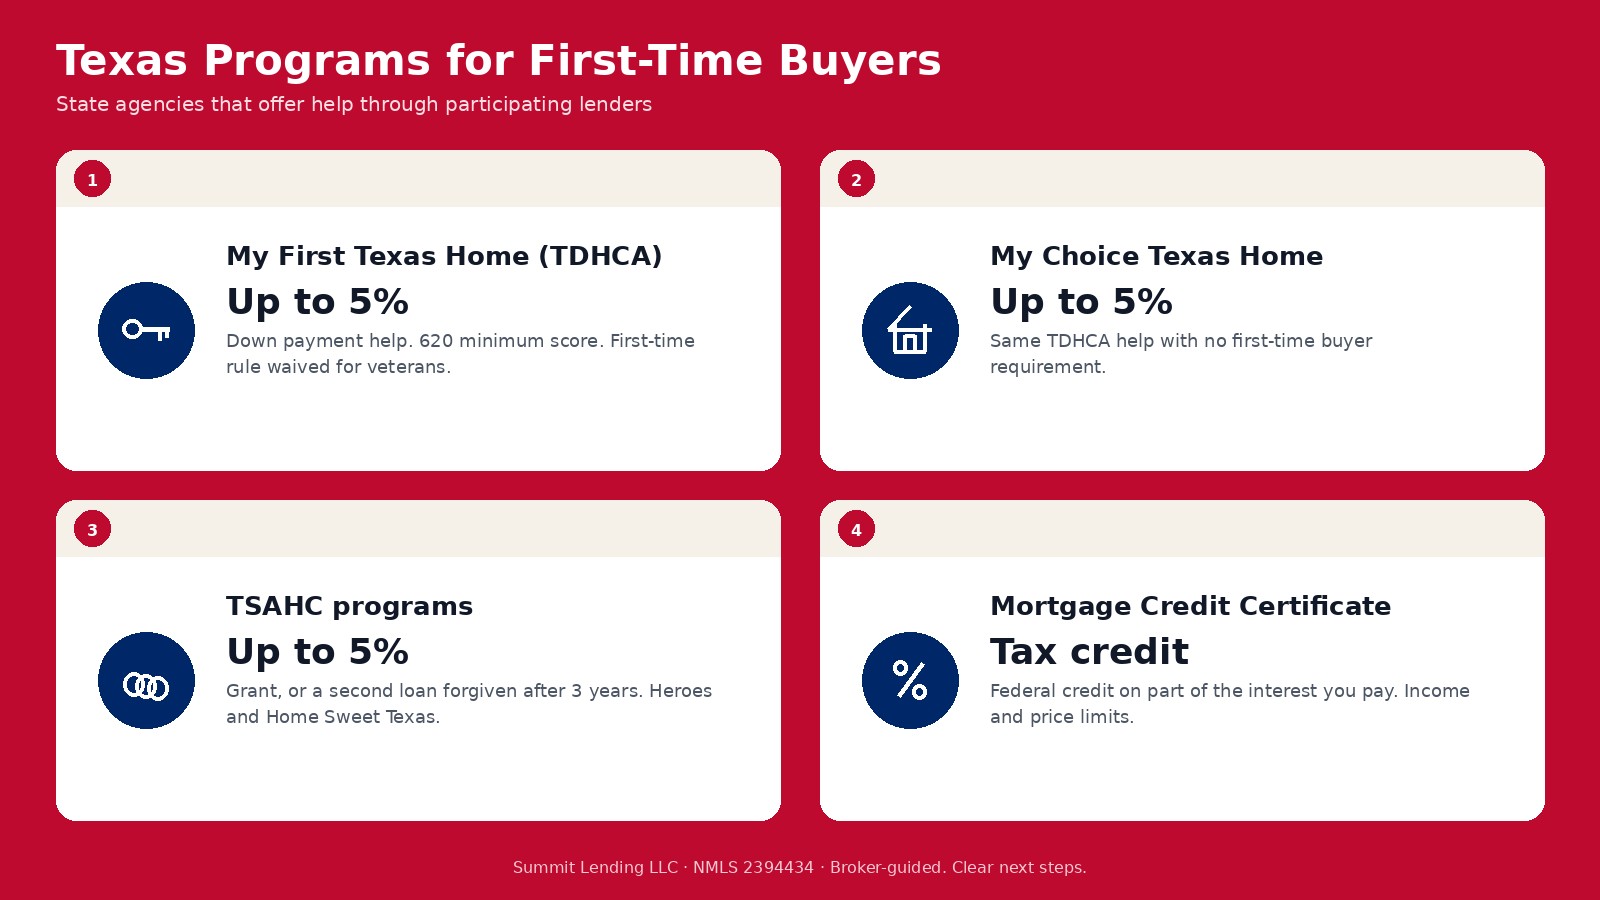
TDHCA programs: My First Texas Home and My Choice Texas Home
The Texas Department of Housing and Community Affairs (TDHCA) runs the Texas Homebuyer Program through participating lenders (TDHCA program chart):
- My First Texas Home. Down payment assistance up to 5% with an FHA, VA, or USDA loan. It is for first-time buyers, defined as no ownership interest in a primary residence in the past three years. That requirement is waived for veterans and for homes in qualified targeted census tracts. The minimum credit score is 620.
- My Choice Texas Home. The same up to 5% assistance with no first-time buyer requirement, and it adds a conventional option (Fannie Mae HFA Preferred). Minimum credit score is also 620.
- Texas Mortgage Credit Certificate. Available on its own or combined with a TDHCA loan, for first-time buyers under the same three-year rule.
For all three, the maximum debt-to-income ratio is 50% with automated or manual underwriting approval. Eligible properties include single-family homes, owner-occupied duplexes, FHA-approved condos, and FHA-approved manufactured homes. Purchase price and income limits apply.
TSAHC programs: Homes for Texas Heroes and Home Sweet Texas
The Texas State Affordable Housing Corporation (TSAHC) offers fixed-rate loans with down payment assistance of up to 5% of the loan amount (TSAHC programs). Homes for Texas Heroes is for listed professions, including educators, police officers, firefighters, EMS personnel, county jailers, correctional officers, and military veterans (Homes for Texas Heroes). Home Sweet Texas serves other low and moderate income buyers.
TSAHC assistance can come as a grant that never has to be repaid or as a second loan that is forgiven after three years if you do not sell, refinance, or move out during that time. TSAHC also offers a deferred, repayable option. First-time buyers can add a Mortgage Credit Certificate, which TSAHC describes as a federal income tax credit equal to 15% of the mortgage interest you pay each year (TSAHC).
Loan options for first-time buyers in Texas
FHA with 3.5% down
FHA requires 3.5% down with a 580 or higher score and is more flexible on credit history (HUD FHA overview). It adds a 1.75% upfront premium and an annual premium, 0.55% for most loans with less than 5% down (HUD Mortgagee Letter 2023-05). In 2026, the one-unit FHA limit is $571,550 in the Austin metro, $563,500 in Dallas-Fort Worth, and $557,750 in San Antonio (HUD lookup).
Conventional with 3% down
Qualified buyers can put 3% down on a one-unit primary home (Fannie Mae eligibility matrix). PMI applies below 20% down and can be cancelled once you reach 80% of the original value (CFPB on PMI). The 2026 conforming limit is $832,750 in all 254 Texas counties (FHFA).
VA and USDA with 0% down
Eligible veterans and service members can buy with no down payment and no monthly mortgage insurance (VA purchase loans), with a funding fee unless exempt (VA funding fee). USDA allows no down payment in eligible rural areas for households under the income limits (USDA); check an address on the USDA eligibility map.
Closing costs and the homestead exemption
Plan for closing costs on top of the down payment. TSAHC notes that closing costs typically run 2% to 5% of the purchase price, which is one reason its assistance can be used for both (TSAHC). Title insurance premium rates in Texas are set by the Texas Department of Insurance (TDI), while lender fees vary, so compare Loan Estimates.
After you move in, file for your homestead exemption with the county appraisal district. Since Proposition 13 passed in 2025, the school district homestead exemption is $140,000 (Ballotpedia on Proposition 13; Texas Comptroller). It can make a big difference in your escrow payment.
First-time buyer steps with Summit
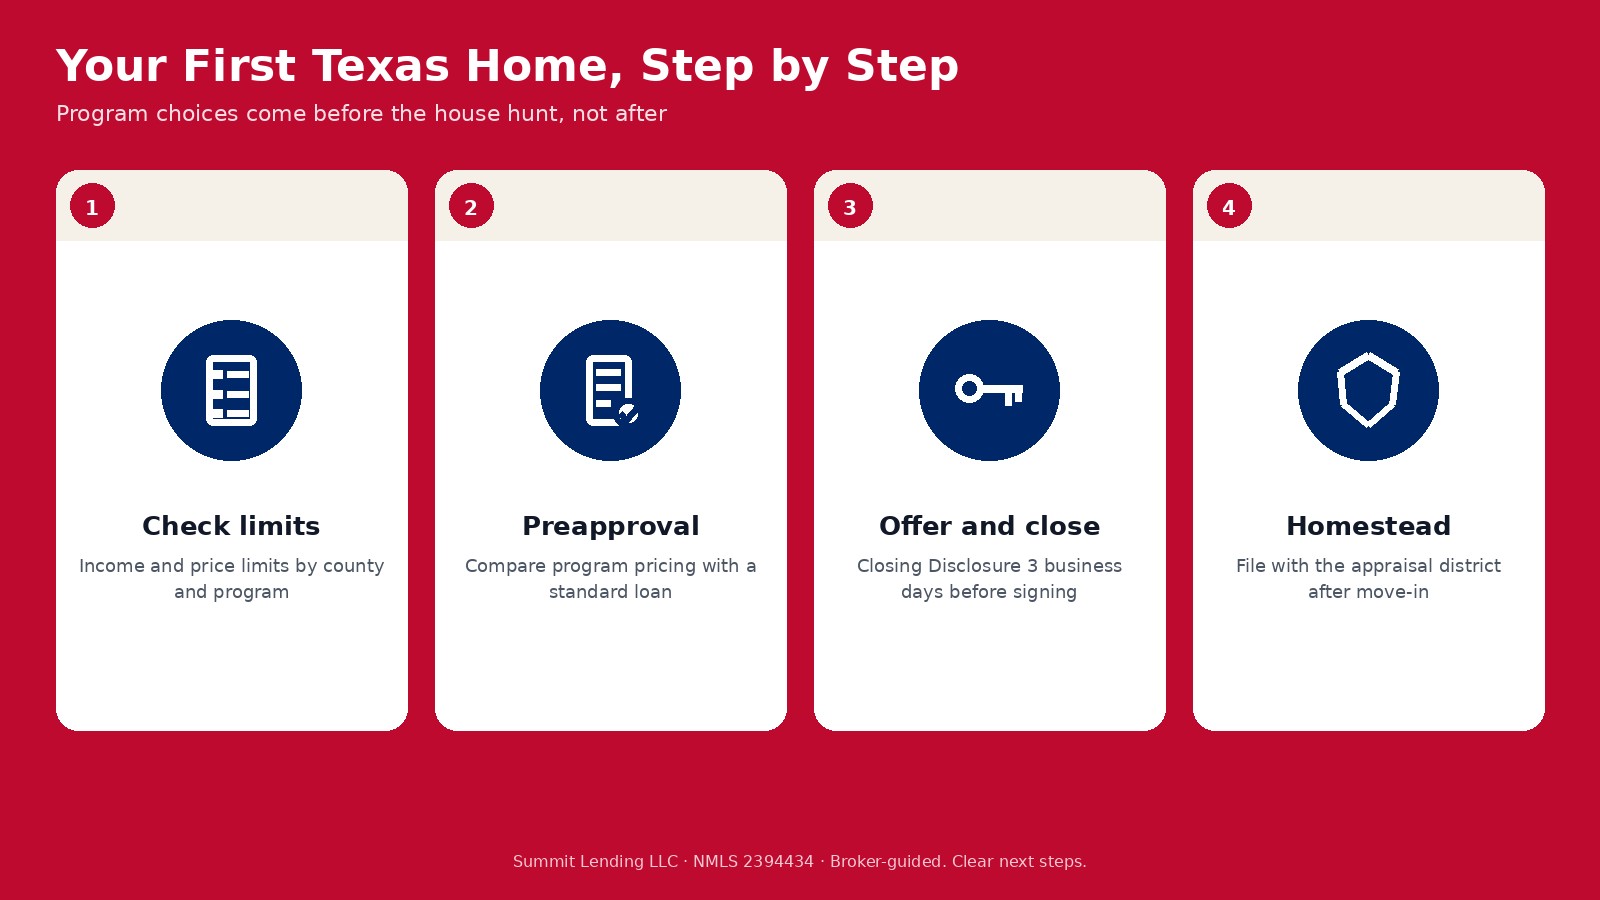
- Check limits and programs. Income and price limits vary by county and program. We check which ones you qualify for.
- Get preapproved. We verify credit, income, and assets. Lenders use prequalification and preapproval differently, so ask what was verified (CFPB comparison). Several mortgage credit checks within 45 days count as one inquiry (CFPB).
- Offer and Loan Estimate. Your Loan Estimate arrives within three business days of application (CFPB on Loan Estimates).
- Close. Your Closing Disclosure comes at least three business days before signing (CFPB).
- File for the homestead exemption. Do it with your appraisal district after move-in.
Lenders also look at your debt-to-income ratio, which compares monthly debts, including the new payment, with gross monthly income (CFPB on DTI).
Where we help first-time buyers in Texas
Greater Houston: Houston, Katy, Sugar Land, Pearland, Conroe, Harris County, Fort Bend County, and Montgomery County. North Texas: Dallas, Fort Worth, Plano, Dallas County, Tarrant County, Collin County, and Denton County. Central and South Texas: Austin, Waco, Killeen, College Station, Corpus Christi, Travis County, Williamson County, and Bexar County. West Texas: El Paso, Lubbock, and Amarillo.
Related pages
Compare Texas purchase loans, read the Texas mortgage overview, or see first-time buyer guides for Utah, Idaho, and Wyoming.
Sources
- Redfin, Texas housing market
- Freddie Mac PMMS, Oct 1, 2026 release
- TDHCA homebuyer program chart (PDF)
- TSAHC, loans and down payment assistance
- TSAHC, Homes for Texas Heroes
- HUD, Let FHA loans help you
- HUD Mortgagee Letter 2023-05, FHA annual MIP (PDF)
- HUD FHA mortgage limits lookup
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- FHFA, 2026 conforming loan limits
- VA purchase loan
- VA funding fee and closing costs
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- Texas Department of Insurance, title insurance
- Ballotpedia, Texas Proposition 13 (2025)
- Texas Comptroller, property tax exemptions
- CFPB, prequalification vs. preapproval
- CFPB, when a lender checks your credit
- CFPB, What is a Loan Estimate?
- CFPB, What is a Closing Disclosure?
- CFPB, debt-to-income ratio
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.
Our Process Is Straightforward
With Summit Lending, you can be rest assured that our mortgage loan experts will guide you throughout the process, from exploring your loan options to approval.