
First-Time Home Buyer Loans with a Clear Cash and Payment Plan

Get A Mortgage Loan And Unlock Your First Home
Buying your first home is life-changing, and it's only natural for you to want to take the big step without any uncertainties. At Summit Lending, we help first-time home buyers navigate the process of finding the best mortgage loan.
With us, you won't have to worry about struggling with mortgage payments or refinancing in the future. We help you get it right the first time.
First-time home buyer loans with a clear plan for cash, credit, and payment
Buying your first home is less about finding a secret loan and more about lining up a payment you can live with, enough cash to close, and a program that fits your credit and the property. Summit Lending LLC (NMLS 2394434) helps first-time buyers compare Conventional, FHA, VA, USDA, and assistance options without pretending every program is free money.
We serve Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona from 4542 W 14800 N, Garland, UT 84312. Call 385-200-1470 or email [email protected].
What "first-time" usually means
Many programs treat you as a first-time buyer if you have not owned a primary home in the last three years. Some assistance programs use a stricter definition or add income and purchase-price caps. Education courses are often required before funds are reserved. We will tell you which definition applies to the option you are considering.
Loan paths first-time buyers compare most
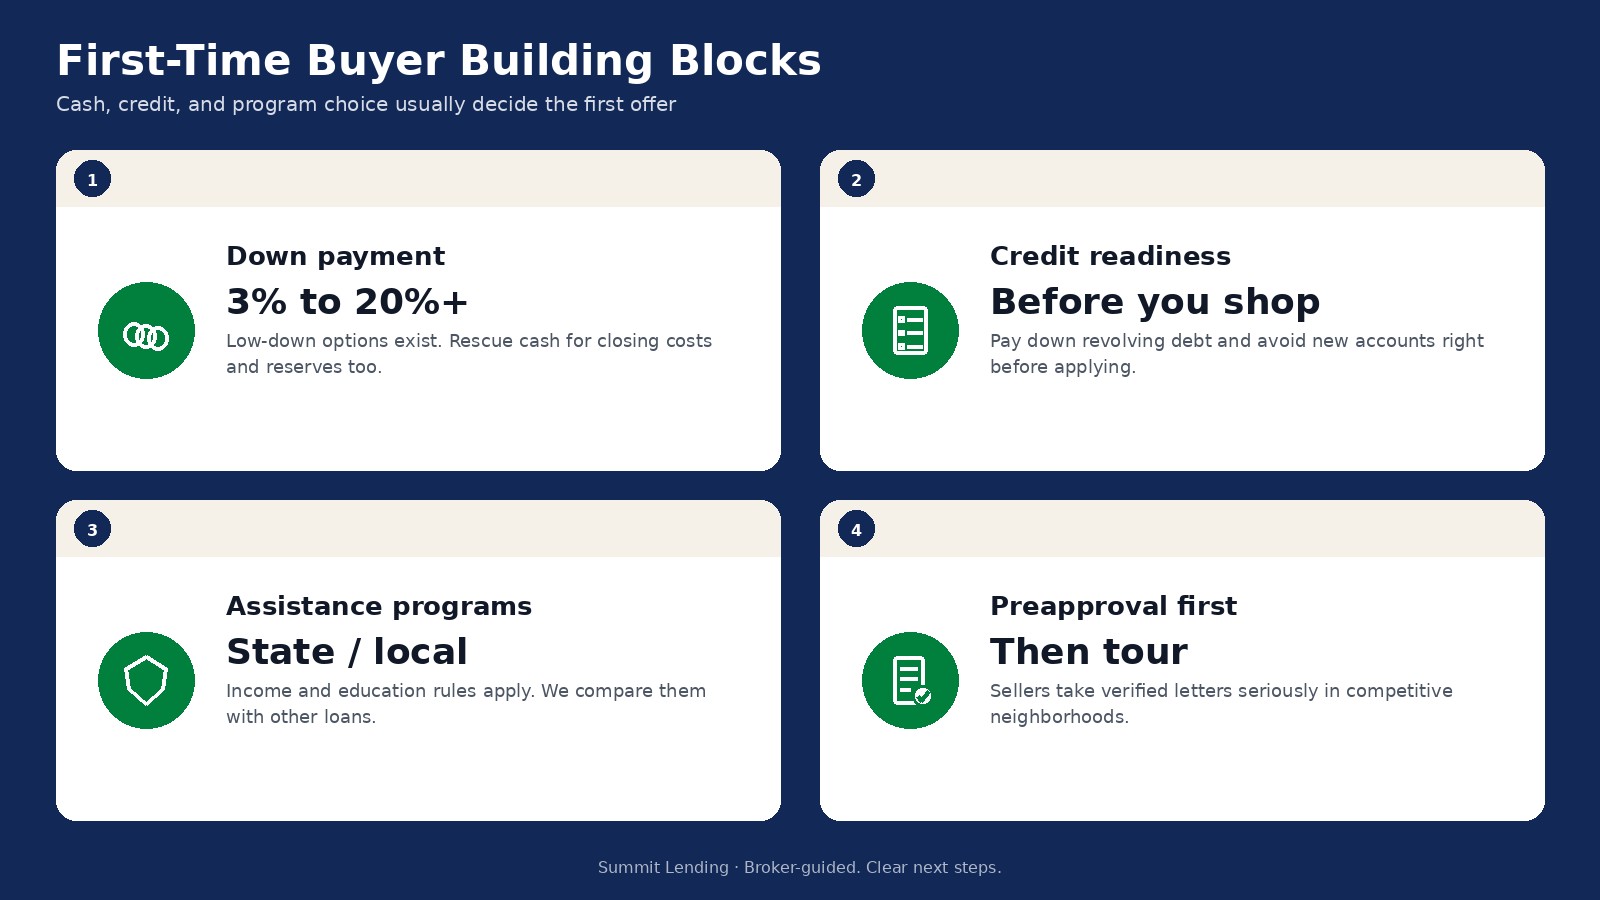
- Conventional with low down payment. Some options start near 3% down when credit and reserves work.
- FHA. Commonly 3.5% down with more flexible credit overlays, plus mortgage insurance rules you need to understand before you fall in love with a payment quote.
- VA. Often 0% down for eligible veterans and service members.
- USDA. 0% down in eligible locations when income limits fit.
- Down payment assistance. State and local seconds can reduce cash to close, usually with income limits, education, and sometimes higher combined payments. We compare them with a plain first mortgage so the tradeoffs are visible.
FHFA's 2026 conforming limit of $832,750 (high-cost ceiling $1,249,125) caps many Conventional files. Jumbo purchases need different planning. Payment modeling should use current survey context carefully: Freddie Mac averaged 7.28% on the 30-year fixed for the week of October 1, 2026. That is not a Summit quote.
State first-time buyer hubs
- Utah first-time home buyer and Utah mortgages
- Texas first-time home buyer and Texas mortgages
- Idaho first-time home buyer and Idaho mortgages
- Wyoming first-time home buyer and Wyoming mortgages
Pair those with a verified preapproval and the main purchase loans page. County pages such as Salt Lake County, Utah County, Harris County, and Ada County help narrow taxes and price expectations.
A practical first-time checklist
- Pull your credit and clean up obvious errors before you apply
- Estimate cash needed for down payment, closing costs, moving, and reserves
- Get preapproved, then tour homes inside that range
- Compare at least two programs on the same property
- Budget for taxes, insurance, and maintenance, not only principal and interest
Use the loan calculator for a first pass, then talk with us before you write an offer. Related reading: all mortgage loans and construction loans if you are considering a new build instead of a resale.
Common first-time mistakes we help you avoid
Maxing out the approval amount, skipping insurance quotes until the last week, financing furniture on new credit after you apply, and treating assistance funds as free money without reading the second-lien terms. Another frequent miss: forgetting that property taxes in a fast-growing county can move after reassessment. We build payment ranges with those realities included.
Education courses and assistance timing
If you want a program that requires a homebuyer education certificate, finish the course before you fall in love with a house that needs a three-day close. Assistance reservations can also have purchase-price caps and target-area rules. Starting early keeps those options alive instead of scrambling after your offer is accepted.
Building a starter-home payment you can keep
Payment shock after the first escrow analysis is one of the worst first-year surprises. Ask for tax and insurance estimates from the county and a local insurer, not only an online average. If you are stretching to the maximum approval, leave room for maintenance and an emergency fund. Owning should feel more stable than renting, not less.
Information on this page is for general education. It is not a commitment to lend. Loan availability, terms, and pricing depend on your credit, income, assets, property, and lender overlays. Summit Lending LLC, NMLS 2394434.
Our Process Is Straightforward
With Summit Lending, you can be rest assured that our mortgage loan experts will guide you throughout the process, from exploring your loan options to approval.




