
Mortgage Preapproval Built on Documents, Not Guesswork

Your Guide To Home Loan Pre Approval
What Are Mortgage Loan Pre-Approvals?
A home loan pre-approval serves as a stamp of approval from lenders confirming your financial readiness to buy a home. Before you get pre-approved, the lender will evaluate your debt-to-income ratio and creditworthiness. Upon approval, you will receive a statement that serves as their conditional commitment to lending you money to buy your home while also showing how much they are willing to give you.
Pre-approval Vs Prequalification - What's The Difference?
A prequalification gives you a rough idea of how much you can borrow based on what you tell the lender about your finances. Pre-approval, on the other hand, means the lender has checked and confirmed your financial information, giving you a conditional thumbs-up for a specific loan amount.
When Should You Get Pre-Approved?
You can get approved for a mortgage in as little as one business day if your paperwork is in order, while other lenders may take longer. Pre-approvals are usually valid for 90 days. However, some lenders may keep it valid for 30 or 60 days.
We recommend you start before looking for a home to ensure you can make an offer on the home you like on time.
Do Pre-approvals Affect Your Credit Score?
Before you get preapproved for a mortgage, lenders carry out a hard pull of your credit to check your score, temporarily lowering it by a few points. However, you will have a 45-day window in which multiple credit score inquiries will be considered on your credit report. Are you worried about denial? You can ask the lender why your home loan pre approval was denied and address the issue.
However, when you work with mortgage loan specialists like us, we ensure you apply for the loans that best align with your financial situation, maximizing your chances of approval.
Pre-Approval Costs
You may be wondering if you need to pay money to get pre-approved for a mortgage loan. That depends on the lender you choose to work with. Some do it for free, while others demand a non-refundable application fee you must pay upfront, whether you get approved or not.
Mortgage preapproval that sellers and listing agents can trust
A serious offer usually needs more than a soft online estimate. Mortgage preapproval means we have reviewed your credit, income, assets, and debts well enough to issue a letter tied to a realistic price range. Summit Lending LLC (NMLS 2394434) treats preapproval as underwriting prep, not a marketing PDF.
Based at 4542 W 14800 N, Garland, UT 84312, we help buyers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
Prequalification vs preapproval
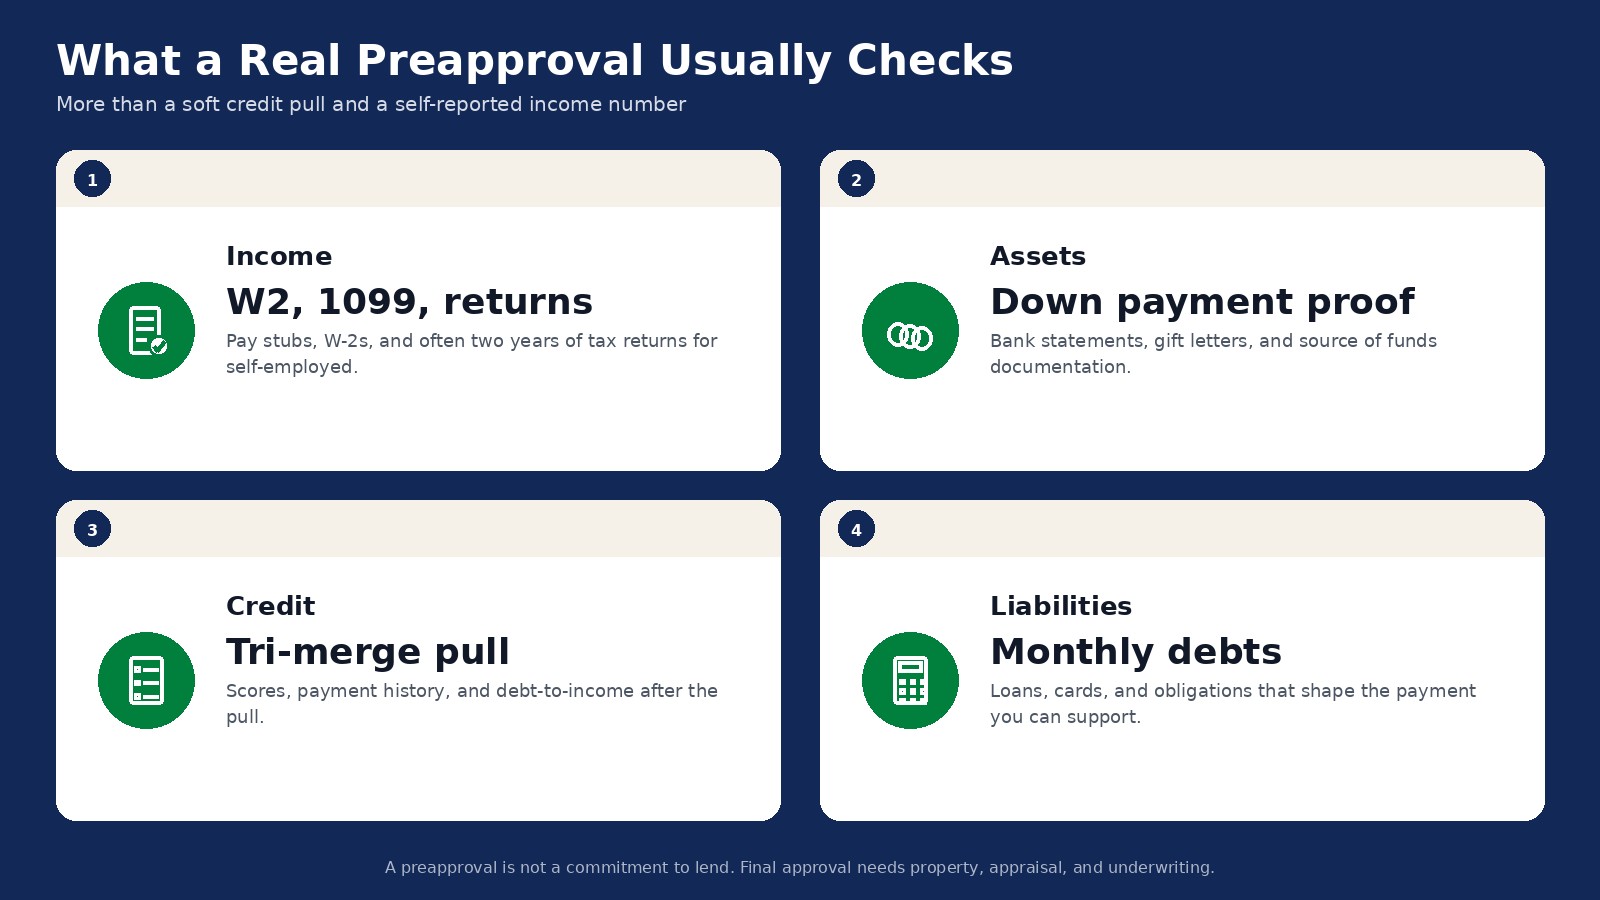
Prequalification is often based on what you tell a website or a loan officer. It can be a useful first conversation, but it is easy to overstate income or understate debts.
Preapproval typically includes a credit pull and documentation: pay stubs, W-2s or tax returns, bank statements, and a review of monthly liabilities. The letter that results is stronger in multiple-offer situations because it is grounded in verified numbers. It is still not a final commitment to lend. The property, appraisal, title, and full underwriting have to clear after you are under contract.
What we usually collect
- Government ID and basic application information
- Recent pay stubs and W-2s, or two years of returns if you are self-employed
- Two or more months of asset statements for down payment and reserves
- Gift letter and donor documentation when family money is part of cash to close
- Landlord contacts or mortgage statements if you rent or already own
After that review we talk payment comfort, not just maximum approval size. Freddie Mac's survey average of 7.28% for the week of October 1, 2026 is useful for payment modeling and is not a locked quote. Use the loan calculator, then refine with us.
State preapproval pages
- Utah preapproval and Utah mortgages
- Texas preapproval and Texas mortgages
- Idaho preapproval and Idaho mortgages
- Wyoming preapproval and Wyoming mortgages
First-time buyers should pair this page with first-time home buyer. If you already own and might refinance instead of buying, see refinance.
How to keep a preapproval healthy while you shop
- Do not open new credit cards or finance cars until after closing
- Avoid large unexplained deposits; document gifts and transfers
- Tell us about job changes before you accept an offer timing you cannot support
- Revisit the letter if your price ceiling or loan program changes
Ready to buy? Continue to purchase loans or your state purchase hub such as Utah purchase or Texas purchase.
How long a preapproval letter usually lasts
Many letters are written to remain reliable for 60 to 90 days, but the underlying credit and income facts can change sooner. If you pause shopping for several months, plan on a refresh. If your income is commission-heavy or seasonal, we may date the letter more conservatively and revisit numbers before you escalate an offer.
Conditional approval after you are under contract
Preapproval gets you to an accepted offer. Conditional approval is the next milestone, when underwriting has reviewed the full file against the specific property. Appraisal, title, insurance binders, and any condo or HOA questionnaires still have to clear. We keep that sequence visible so you do not confuse a strong preapproval with a clear-to-close.
Shop state hubs like Utah purchase and Texas purchase once the letter is in hand.
Using the letter with your real estate agent
Share the letter early, and tell your agent which price ceiling is comfortable, not only which ceiling is maximum. Maximum approval is not the same as a payment you can sustain. If you are shopping multiple states in our footprint, we can issue letters that match each search area after we confirm local taxes and insurance assumptions.
Self-employed and variable-income buyers
Two years of returns are common. Declining income, large one-time additions, or heavy write-offs need explanation. Bring a year-to-date profit-and-loss statement and be ready to talk through add-backs. The goal is a letter that underwriting will still recognize after you are under contract.
Information on this page is for general education. It is not a commitment to lend. Loan availability, terms, and pricing depend on your credit, income, assets, property, and lender overlays. Summit Lending LLC, NMLS 2394434.




