Utah Mortgage Preapproval
Your Guide To Home Loan Pre Approval in Utah
What Are Mortgage Loan Pre-Approvals?
A home loan pre-approval serves as a stamp of approval from lenders confirming your financial readiness to buy a home. Before you get pre-approved, the lender will evaluate your debt-to-income ratio and creditworthiness. Upon approval, you will receive a statement that serves as their conditional commitment to lending you money to buy your home while also showing how much they are willing to give you.
Pre-approval Vs Prequalification - What's The Difference?
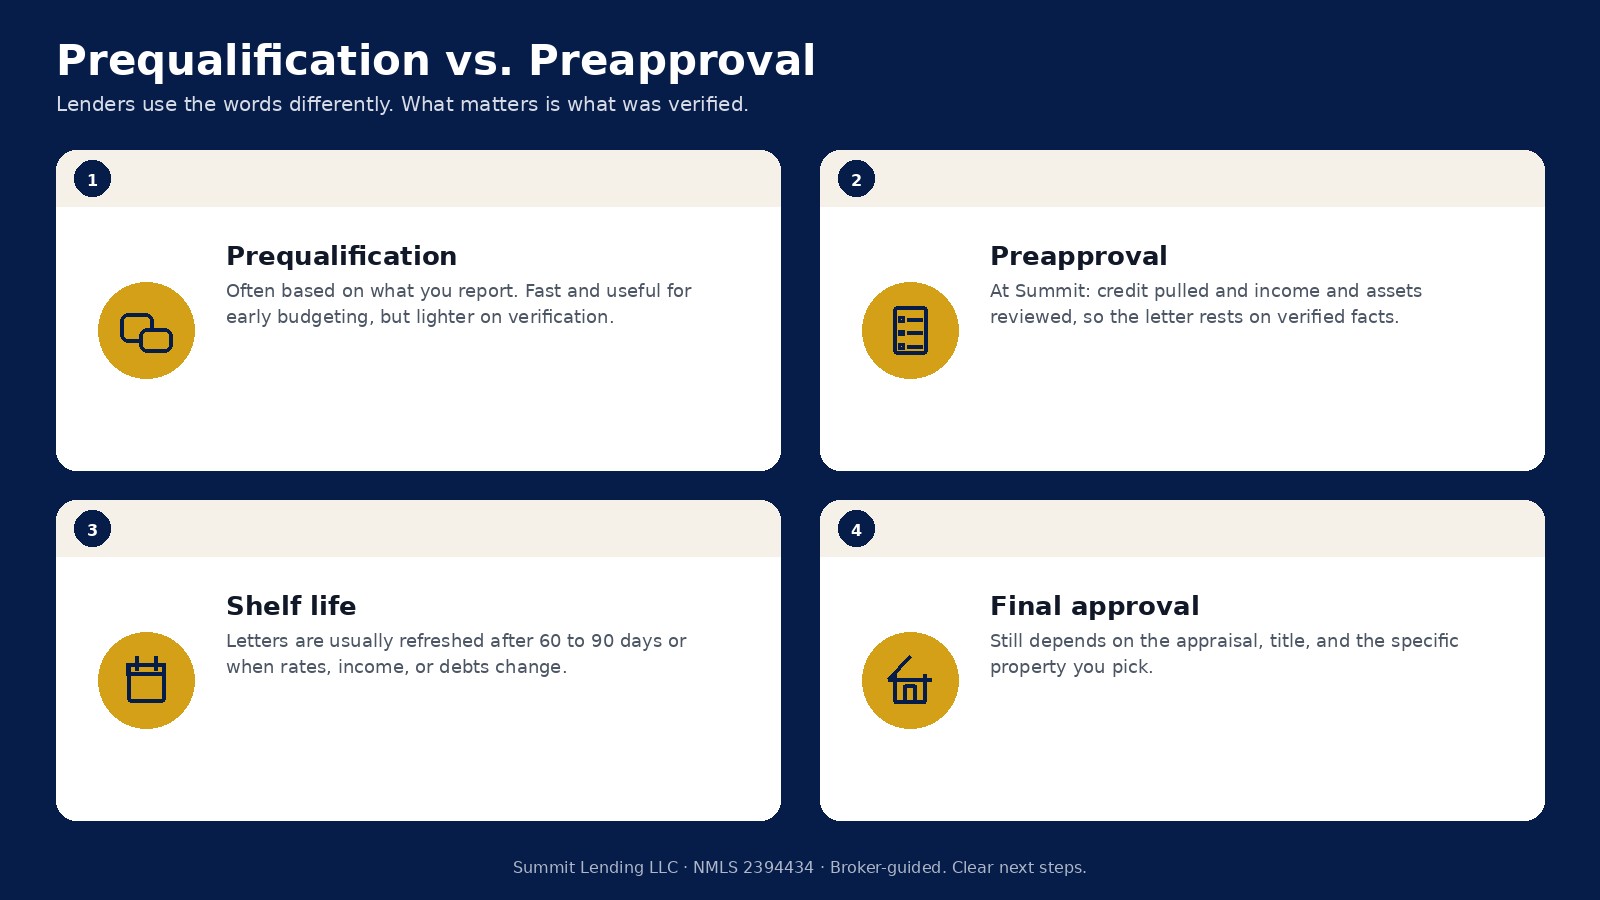
A prequalification gives you a rough idea of how much you can borrow based on what you tell the lender about your finances. Pre-approval, on the other hand, means the lender has checked and confirmed your financial information, giving you a conditional thumbs-up for a specific loan amount.
When Should You Get Pre-Approved?
You can get approved for a mortgage in as little as one business day if your paperwork is in order, while other lenders may take longer. Pre-approvals are usually valid for 90 days. However, some lenders may keep it valid for 30 or 60 days.
We recommend you start before looking for a home to ensure you can make an offer on the home you like on time.
Do Pre-approvals Affect Your Credit Score?
Before you get preapproved for a mortgage, lenders carry out a hard pull of your credit to check your score, temporarily lowering it by a few points. However, you will have a 45-day window in which multiple credit score inquiries will be considered on your credit report. Are you worried about denial? You can ask the lender why your home loan pre approval was denied and address the issue.
However, when you work with mortgage loan specialists like us, we ensure you apply for the loans that best align with your financial situation, maximizing your chances of approval.
Pre-Approval Costs in Utah
You may be wondering if you need to pay money to get pre-approved for a mortgage loan in Utah. That depends on the lender you choose to work with. Some do it for free, while others demand a non-refundable application fee you must pay upfront, whether you get approved or not.
Mortgage preapproval in Utah, done properly
A preapproval letter tells a seller that a lender has looked at your finances and is generally willing to lend you up to a certain amount. In a Utah market where good listings still draw multiple offers, a solid letter can be the difference between an accepted offer and a polite no. Summit Lending LLC (NMLS 2394434) is a Utah mortgage broker based in Garland. We build preapprovals on verified credit, income, and assets, and we compare loan programs from multiple lenders before we write the letter, so the number on it is one you can actually close on.
This page explains what a preapproval is (and is not), the documents to gather, how credit checks work while you shop, and how Utah programs fit in. Ready now? Call us, or test a budget first in the Utah loan calculator.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
Prequalification vs. preapproval
The Consumer Financial Protection Bureau points out that lenders use the terms prequalification and preapproval differently. Both describe a letter saying a lender is generally willing to lend up to an amount based on certain assumptions, and neither is a guaranteed loan offer (CFPB comparison). Some lenders issue a prequalification from information you report and reserve the word preapproval for files where information has been verified.
The useful question is not what the letter is called but what stands behind it. At Summit, a Utah preapproval means we have pulled credit with your permission, reviewed income and asset documents, and checked the loan program against your debt-to-income ratio and the price range you plan to shop. That gives your agent something to stand behind when a listing agent calls to ask about you.
What you need for a Utah preapproval
Income
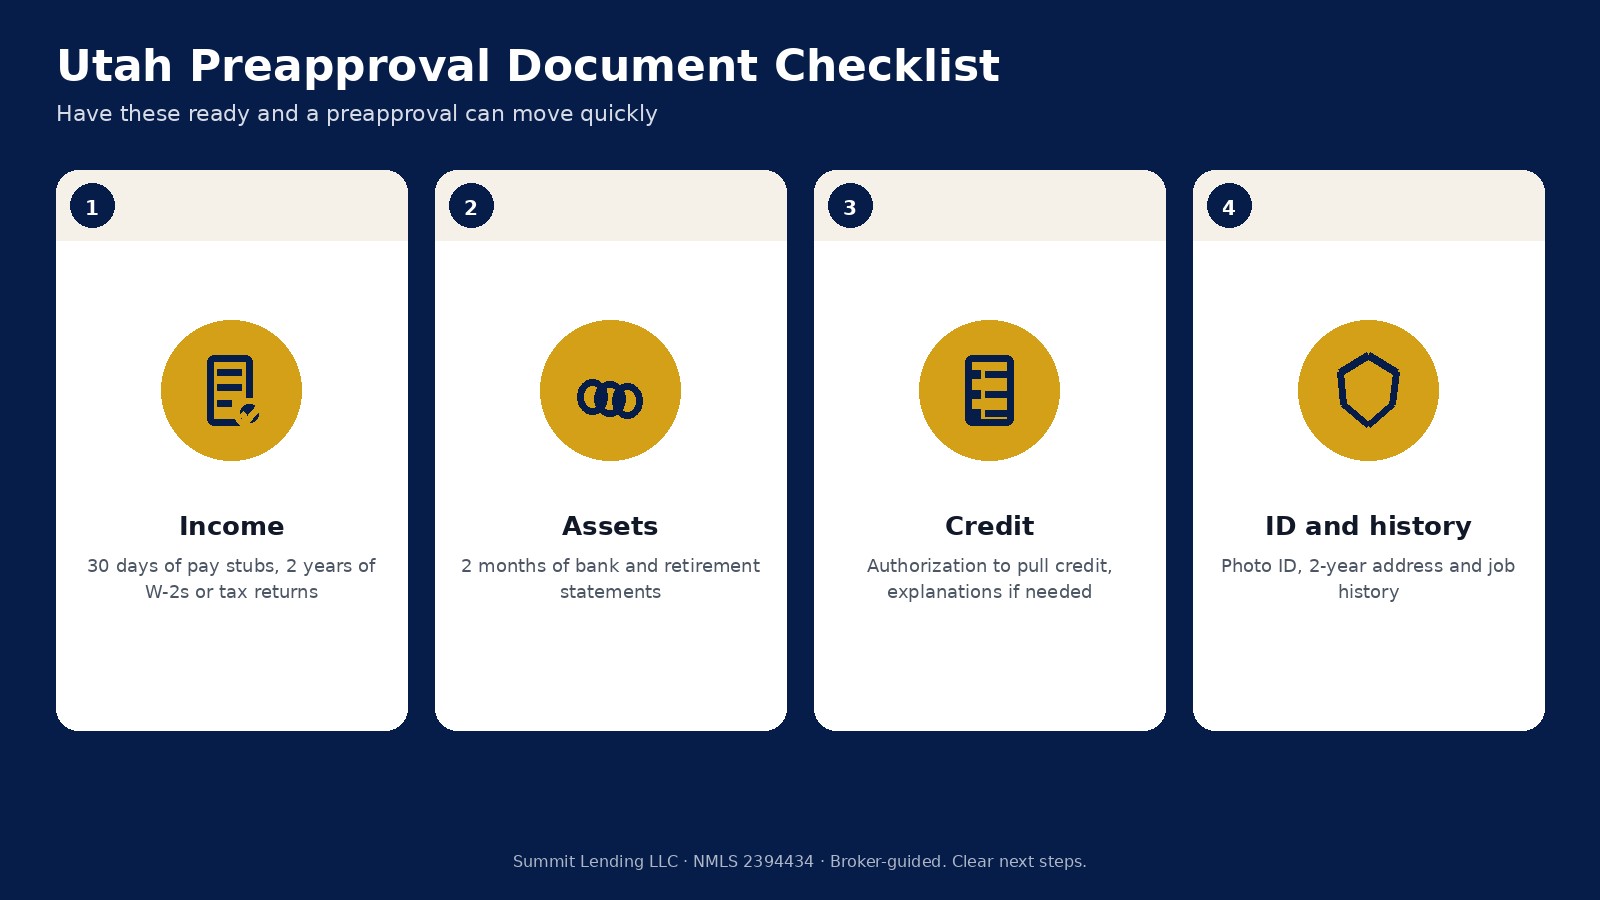
- Pay stubs covering the most recent 30 days
- W-2s for the last two years
- If self-employed, two years of personal and business tax returns, plus a year-to-date profit and loss statement
- Award letters for Social Security, pension, VA disability, or other benefit income
Assets
- Two months of statements for checking, savings, and investment accounts
- Retirement account statements if you plan to use them for reserves
- A gift letter if family is helping with the down payment
Credit and history
- Your authorization to pull credit
- Photo ID and two years of address and employment history
- Explanations for any recent late payments, collections, or large deposits
- For veterans, your Certificate of Eligibility or the information to request it (VA eligibility)
How the credit check works while you shop
A mortgage credit check shows up as an inquiry, which typically has a small effect on your scores. The CFPB explains that multiple credit checks from mortgage lenders within a 45-day window are recorded as a single inquiry, so you can compare preapprovals and Loan Estimates without stacking up damage (CFPB on credit checks). What does hurt is opening other new credit, like a car loan or credit card, during the process.
What determines your preapproval amount
- Debt-to-income ratio. Lenders compare your monthly debts, including the new housing payment, with your gross monthly income (CFPB on DTI).
- Credit score. It drives program eligibility and pricing. FHA allows 3.5% down at 580 or higher (HUD), and Utah Housing's FirstHome loan requires 660 (UHC).
- Down payment and reserves. More down can mean lower mortgage insurance and a lower payment.
- The rate environment. Freddie Mac's survey average for a 30-year fixed was 7.28% for the week of October 1, 2026, up from 7.03% a week earlier (Freddie Mac PMMS). When rates move, the same income supports a different loan amount, which is why letters get refreshed.
- Taxes, insurance, and HOA dues. These belong in the payment, and they vary a lot from a Salt Lake condo to a rural Box Elder County home.
A preapproval for the maximum is not the same as a comfortable budget. We will show you the payment at a few price points so you choose the ceiling yourself.
Preapproval with Utah programs and limits in mind
If you plan to use Utah Housing Corporation down payment assistance, tell us before we write the letter. UHC assistance comes as a second loan of up to 6% of the first mortgage, capped at $27,500, or a deferred version of up to 3.5% (UHC down payment assistance), and those programs have income and price limits. First-time buyers purchasing a newly built home may also qualify for up to $20,000 under a separate state program while funds last (UHC new construction program).
Loan limits shape your options at higher prices. The 2026 conforming limit is $832,750 in most Utah counties and $1,150,000 in Summit and Wasatch counties (FHFA). The FHA one-unit floor is $541,287 (HUD). Shopping above those numbers means a jumbo or high-balance loan, and we set the letter up accordingly.
Context helps too. The statewide median sales price was about $525,000 in August 2026 according to the Utah Association of REALTORS (UAR). Your range will depend on where you buy and how much you put down.
How long a preapproval lasts
Most letters are refreshed after about 60 to 90 days, or sooner if your income, debts, or the rate market change. Updating is usually quick: new pay stubs and bank statements, and sometimes a credit refresh. Keep your finances steady between preapproval and closing.
After your offer is accepted
- You formally apply on the property, and the lender sends a Loan Estimate within three business days (CFPB on Loan Estimates).
- The appraisal, title work, and underwriting begin. Final approval depends on the property as well as you.
- You receive the Closing Disclosure at least three business days before closing (CFPB on Closing Disclosures).
The CFPB's free buying guide is a good companion along the way (CFPB Buying a House).
Utah preapproval by city and county
We preapprove buyers across Utah, including Salt Lake City, West Jordan, South Jordan, Lehi, American Fork, Orem, Provo, Ogden, and Layton. County guides cover Salt Lake County, Utah County, Davis County, Weber County, Cache County, Box Elder County, and Washington County. Smaller markets include Tremonton, Brigham City, Heber City, Park City, and Cedar City.
Related pages
Compare loan types on Utah purchase loans, explore Utah first-time home buyer programs, or plan a build with Utah construction loans. The state overview is at Utah mortgage loans. Buying elsewhere? See preapproval guides for Idaho, Texas, and Wyoming, or the main preapproval page.
Sources
- CFPB, prequalification vs. preapproval
- CFPB, when a lender checks your credit
- CFPB, debt-to-income ratio
- HUD, Let FHA loans help you
- Utah Housing Corporation, down payment assistance
- Utah Housing, First-Time Homebuyer Assistance Program (new construction)
- VA home loan eligibility
- Freddie Mac PMMS, Oct 1, 2026 release
- FHFA, 2026 conforming loan limits
- HUD No. 25-145, 2026 FHA loan limits
- Utah Association of REALTORS market activity
- CFPB, What is a Loan Estimate?
- CFPB, What is a Closing Disclosure?
- CFPB, Buying a House
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.