Utah Mortgage Refinance

Utah mortgage refinancing, with the math shown
A refinance replaces the mortgage you have with a new one. Done for the right reason, it can lower your payment, shorten your payoff date, remove mortgage insurance, or turn home equity into cash for a project. Done for the wrong reason, it just restarts the clock and adds closing costs. Summit Lending LLC (NMLS 2394434) is a Utah mortgage broker based in Garland, and our job is to show you which one you are looking at before you pay for an appraisal.
We compare refinance pricing from multiple wholesale lenders for Utah homeowners from Logan to St. George. Below you will find the refinance types we use most, where rates are this fall, the break-even test we run on every file, and Utah-specific details worth knowing. If you would rather start with your own numbers, open the Utah loan calculator.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
Where refinance rates are in fall 2026
Freddie Mac's weekly survey showed the average 30-year fixed rate at 7.28% for the week of October 1, 2026, compared with 7.03% a week earlier and 6.34% a year ago. The 15-year fixed averaged 6.60% (Freddie Mac PMMS release; long-run history on FRED). These are national averages for strong-credit borrowers, so treat them as a weather report, not a quote.
Here is the honest read. With averages above 7%, a refinance purely to lower the rate mostly makes sense for Utah homeowners whose current rate is meaningfully higher than today's market, or who are moving from an adjustable rate that is about to reset. Many homeowners who refinance this year are doing it for other reasons: cash for a remodel or debt payoff, removing FHA mortgage insurance, taking a co-borrower off the loan after a divorce, or moving to a 15-year term to finish sooner. Those goals can still pencil out even when rates are not falling.
Refinance options for Utah homeowners
Rate and term refinance
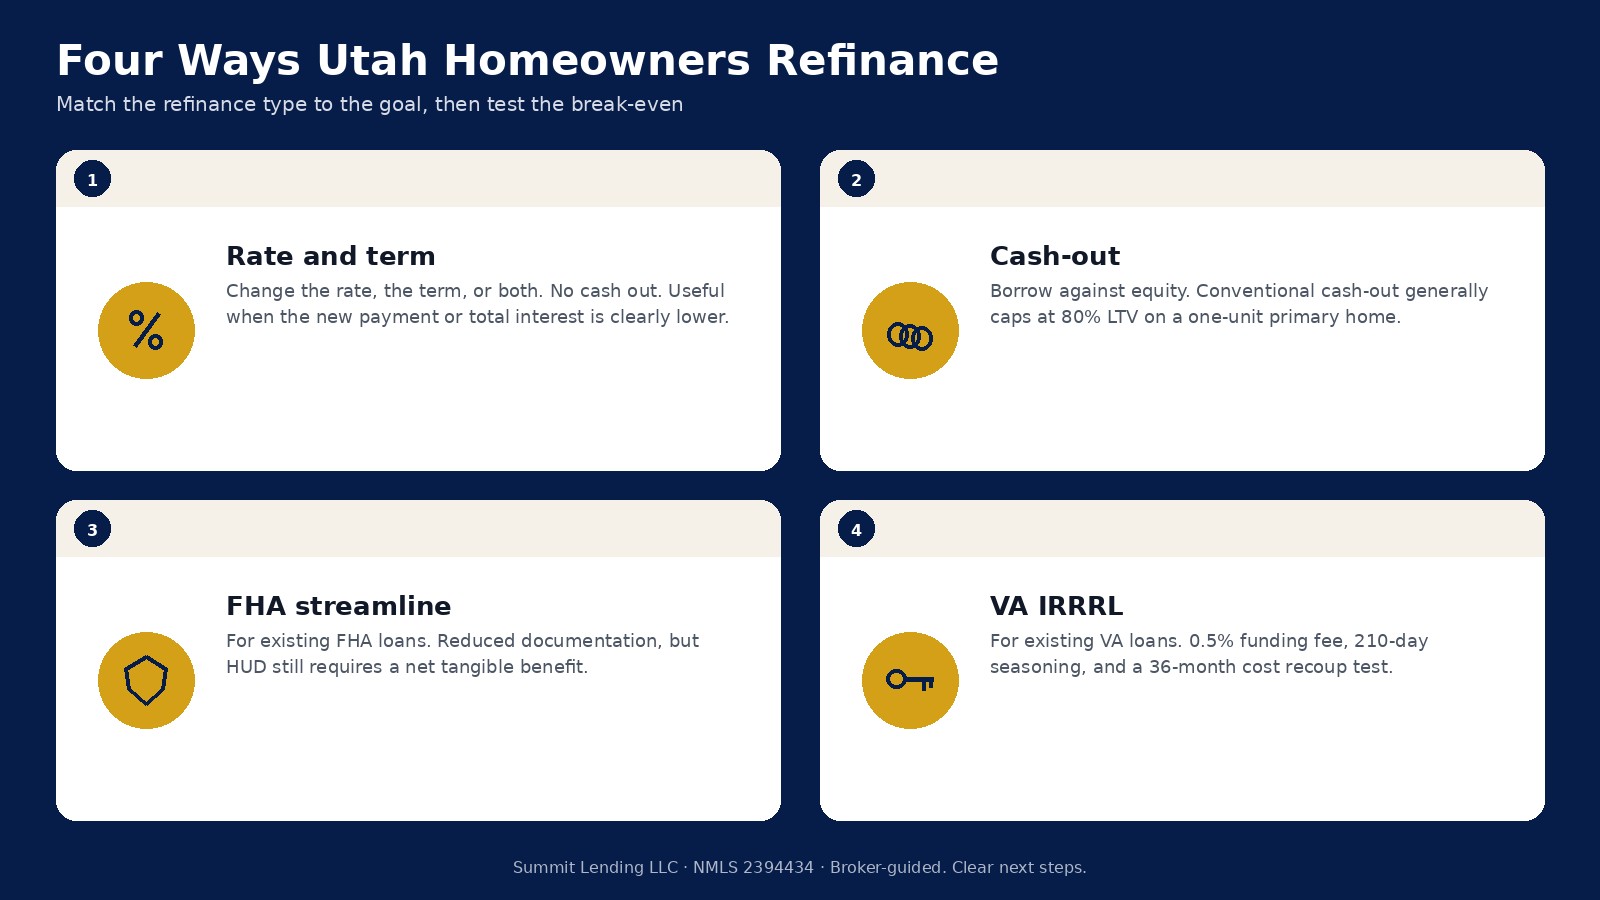
A rate and term refinance changes your rate, your loan term, or both, without taking meaningful cash out. It is the cleanest way to lower a payment when the rate gap is large enough, or to move from 30 years to 15 or 20. Shortening the term often raises the monthly payment but can save a large amount of total interest.
Cash-out refinance
A cash-out refinance replaces your mortgage with a bigger one and pays you the difference. The CFPB notes that you are converting home equity into debt secured by your home, so the stakes are higher than with an unsecured loan (CFPB on cash-out refinancing). On conventional loans, Fannie Mae's eligibility matrix generally caps cash-out on a one-unit primary residence at 80% of the home's value (Fannie Mae Eligibility Matrix). Before you replace a low first mortgage with a higher-rate one, we will also compare a home equity line or second mortgage, which can leave your existing rate untouched.
FHA streamline refinance
If you have an FHA loan now, an FHA streamline refinance can reduce paperwork and sometimes skip the appraisal. HUD still requires that the refinance deliver a net tangible benefit to you, such as a lower combined rate and mortgage insurance payment or a move from an adjustable to a fixed rate. The rules are in HUD's single family handbook (HUD Handbook 4000.1).
VA Interest Rate Reduction Refinance Loan (IRRRL)
Veterans with an existing VA loan can use an IRRRL to lower the rate or move from an adjustable to a fixed rate. The VA funding fee on an IRRRL is 0.5% of the loan amount unless you are exempt (VA funding fee). VA also requires that the loan be seasoned, generally at least six monthly payments and 210 days from the first payment, and that closing costs be recouped within 36 months (VA IRRRL rules). Veterans who want cash can look at a VA cash-out refinance instead, which works more like a new loan.
Removing mortgage insurance
Conventional PMI can usually be cancelled when you reach 80% of the original value and generally ends automatically at 78% (CFPB on PMI). FHA mortgage insurance often lasts much longer. If Utah prices have built equity in your home since you bought, refinancing from FHA to conventional can drop that monthly insurance. We check whether the savings beat the cost.
The break-even test, step by step
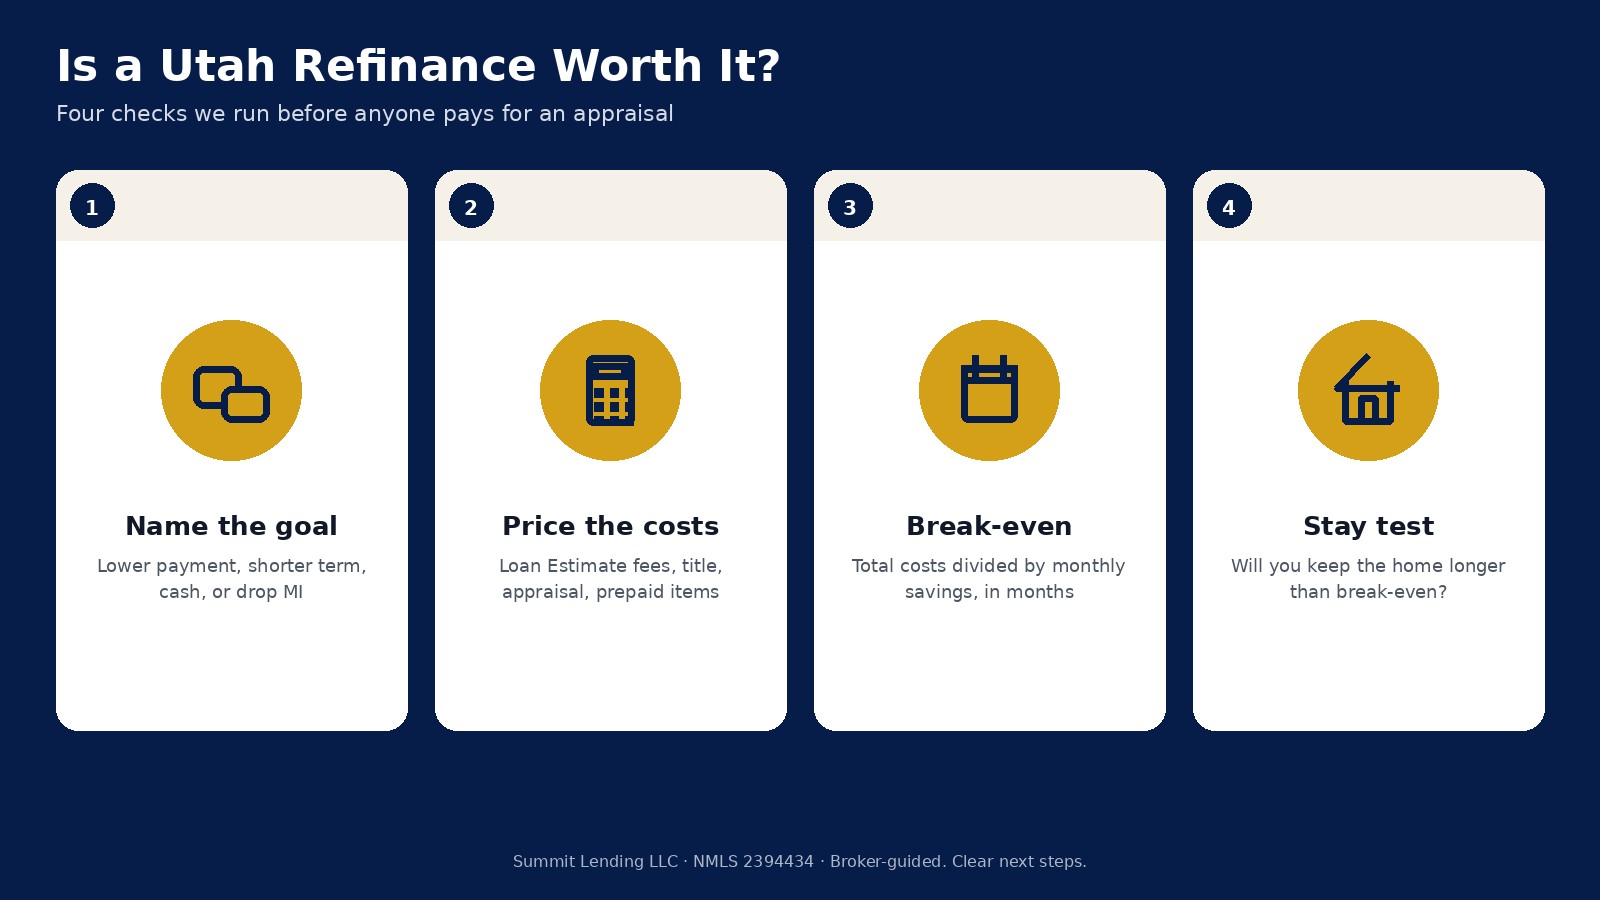
Every refinance has costs: lender fees, appraisal, title insurance, recording, and prepaid interest and escrow. You will see them itemized on your Loan Estimate, which the lender must provide within three business days of application (CFPB on Loan Estimates). The simplest test is this:
- Add up the true costs of the new loan, excluding escrow money that is simply moving from your old account to the new one.
- Find the monthly savings on principal and interest plus mortgage insurance.
- Divide costs by monthly savings. That is your break-even in months.
- Compare that with how long you realistically expect to keep the home and this loan.
As a simple illustration, if a refinance costs $6,000 and saves $200 a month, break-even is 30 months. If you plan to move in two years, it probably is not worth it. If you plan to stay ten years, it may be. We also show you the total interest over the remaining life of the loan, because a lower payment over a longer term can still cost more overall.
Utah details that affect a refinance
- Home values have held up. The Utah Association of REALTORS reported a statewide median of about $525,000 in August 2026, essentially flat from a year earlier (UAR market activity). For many owners who bought several years ago, that means enough equity to drop mortgage insurance or qualify for cash out. Owners who bought at the peak with a small down payment may have less room.
- Loan limits by county. The 2026 conforming limit is $832,750 for most Utah counties, and $1,150,000 in Summit and Wasatch counties (FHFA, county file). A balance above the limit in your county is a jumbo refinance, priced differently.
- Utah Housing loans. If your current mortgage includes a Utah Housing Corporation down payment assistance second loan, that lien has to be paid off or handled during the refinance. UHC explains that its deferred assistance becomes due when you refinance (UHC down payment assistance).
- Property taxes and insurance. Your new escrow account will be built on current taxes and premiums, which may be higher than when you bought. We include that so the new payment is not a surprise.
What we need to start a Utah refinance
- Your most recent mortgage statement and homeowners insurance declarations page
- Recent pay stubs and two years of W-2s, or two years of tax returns if self-employed
- Two months of bank and retirement statements
- Your goal in one sentence: lower payment, shorter term, cash amount, or removing mortgage insurance
We will pull credit with your permission (CFPB on credit checks), price the options, and tell you plainly whether we think you should wait. When you do move forward, you will receive a Closing Disclosure at least three business days before signing (CFPB on Closing Disclosures).
Refinancing across Utah
We help homeowners refinance in Salt Lake City, West Jordan, South Jordan, Lehi, American Fork, Orem, Provo, Spanish Fork, Ogden, and Layton, along with county pages for Salt Lake County, Utah County, Davis County, Weber County, and Cache County.
Closer to home in Northern Utah, see Box Elder County, Brigham City, Tremonton, and Garland. In mountain and southern markets, see Park City, Summit County, Heber City, Washington County, and Cedar City.
Related pages
If you are 62 or older and want to stop making a monthly mortgage payment, compare a refinance with a Utah reverse mortgage. If you are buying your next home instead, see Utah purchase loans and Utah preapproval. Planning a build on land you own? See Utah construction loans. For investment and business property, see Utah commercial loans. The statewide overview lives at Utah mortgage loans, and the general refinance page covers every state we serve, including Idaho, Texas, and Wyoming.
Sources
- Freddie Mac PMMS, Oct 1, 2026 release
- FRED, 30-Year Fixed Rate Mortgage Average
- CFPB, cash-out refinance
- Fannie Mae Eligibility Matrix
- HUD Single Family Housing Policy Handbook 4000.1
- VA funding fee and closing costs
- VA Interest Rate Reduction Refinance Loan
- VA cash-out refinance loan
- CFPB, private mortgage insurance
- CFPB, What is a Loan Estimate?
- CFPB, What is a Closing Disclosure?
- CFPB, when a lender checks your credit
- Utah Association of REALTORS market activity
- FHFA, 2026 conforming loan limits
- FHFA 2026 county loan limit list
- Utah Housing Corporation, down payment assistance
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.
Related Articles

Top Reasons to Refinance Your Mortgage and Why It Works
A 2026 refinance guide aligned to 6% normalization: when payment relief, ARM-to-fixed, PMI removal, cash-out, or term changes make sense, plus break-even math and when to wait.
Mortgage Rates Above 7%: What Utah Buyers Should Do Now (Sept 2026)
Freddie Mac’s 30-year fixed averaged 7.03% the week of September 24, 2026, after the Fed’s mid-month hike. Here is how Utah buyers and homeowners can plan payments, use improving Salt Lake County inventory, and keep the 6% normalization mindset honest when headlines sit above 7%.