Home Purchase Loans with Clear Payment and Cash-to-Close Numbers
Purchase loans with a broker who compares the options before you offer
Buying a home is not one product. A first home with 3.5% down, a move-up with 20% equity, a VA purchase near a base, and a USDA purchase on the edge of town all solve different problems. Summit Lending LLC (NMLS 2394434) is a mortgage broker. Our job is to put workable purchase programs side by side, show payment and cash to close, and help you choose with numbers instead of guesses.
We are based at 4542 W 14800 N, Garland, UT 84312, and we help borrowers across Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected] when you want a clear purchase path before you tour.
What a purchase loan needs to solve
A purchase mortgage funds the home you are buying and is secured by that home. Beyond the sticker price, you need a payment you can live with (principal, interest, taxes, insurance, and any mortgage insurance or HOA dues), enough cash to close, and a program the property and your credit can support. That is why we start with a preapproval instead of a casual online estimate.
Freddie Mac's Primary Mortgage Market Survey put the U.S. 30-year fixed average at 7.28% for the week of October 1, 2026 (6.34% a year earlier). Survey averages are modeling context for well-qualified borrowers putting 20% down. They are not Summit Lending quotes. Your rate depends on credit, loan type, down payment, points, and the day you lock.
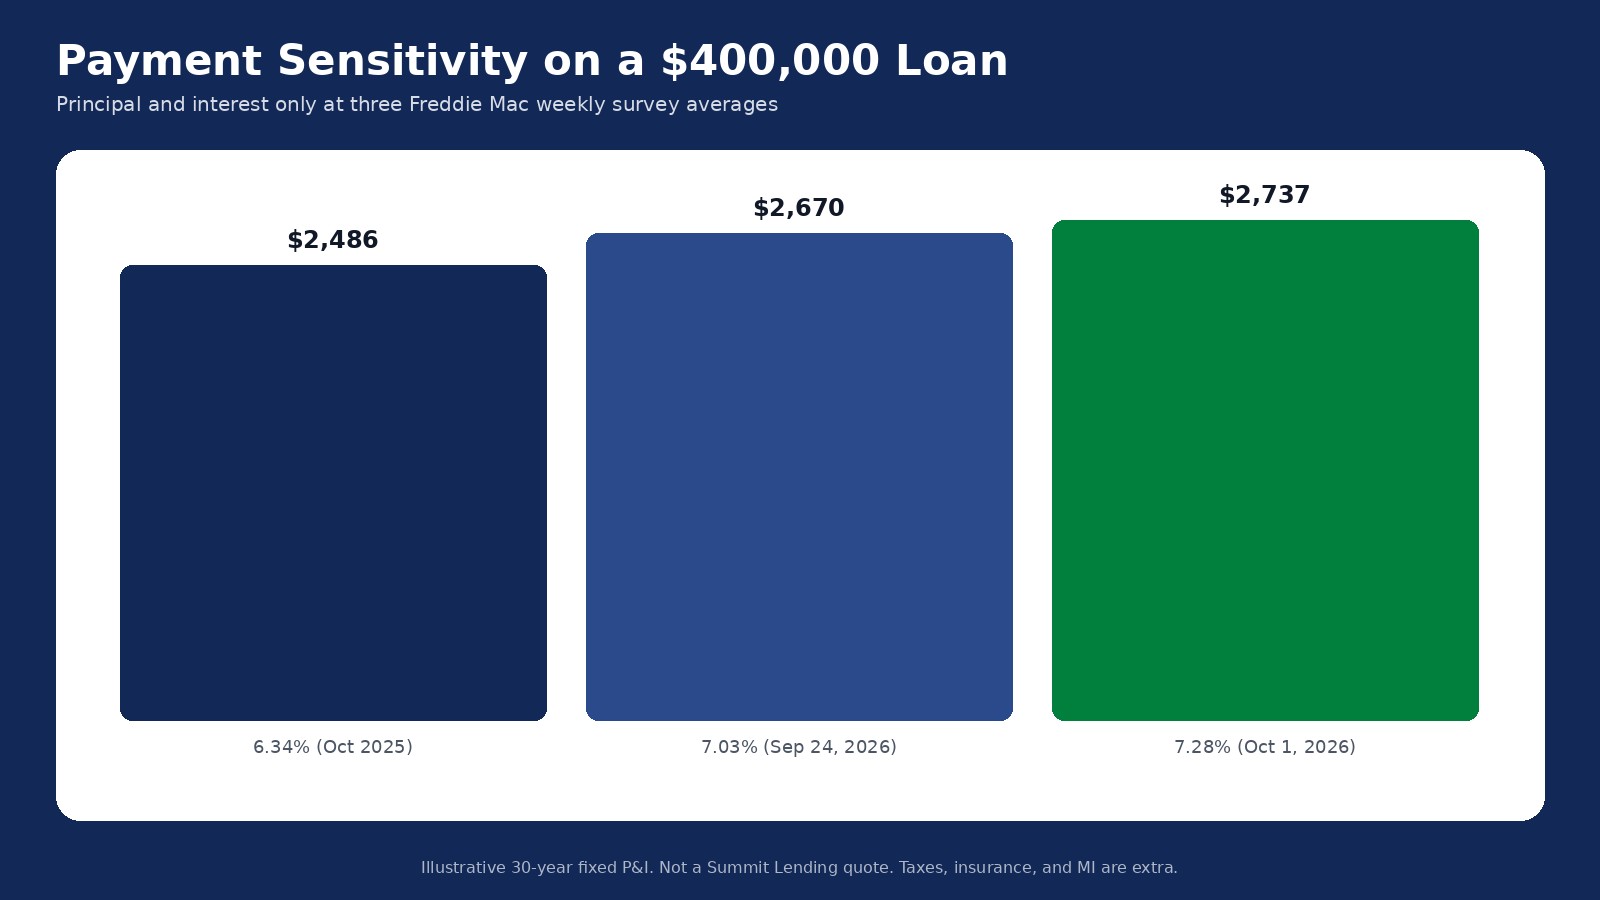
On a $400,000 loan, moving from 6.34% to 7.28% adds roughly $251 a month in principal and interest. Use the mortgage calculator for a first pass, then let us check the full payment against your actual file.
Purchase programs we help compare
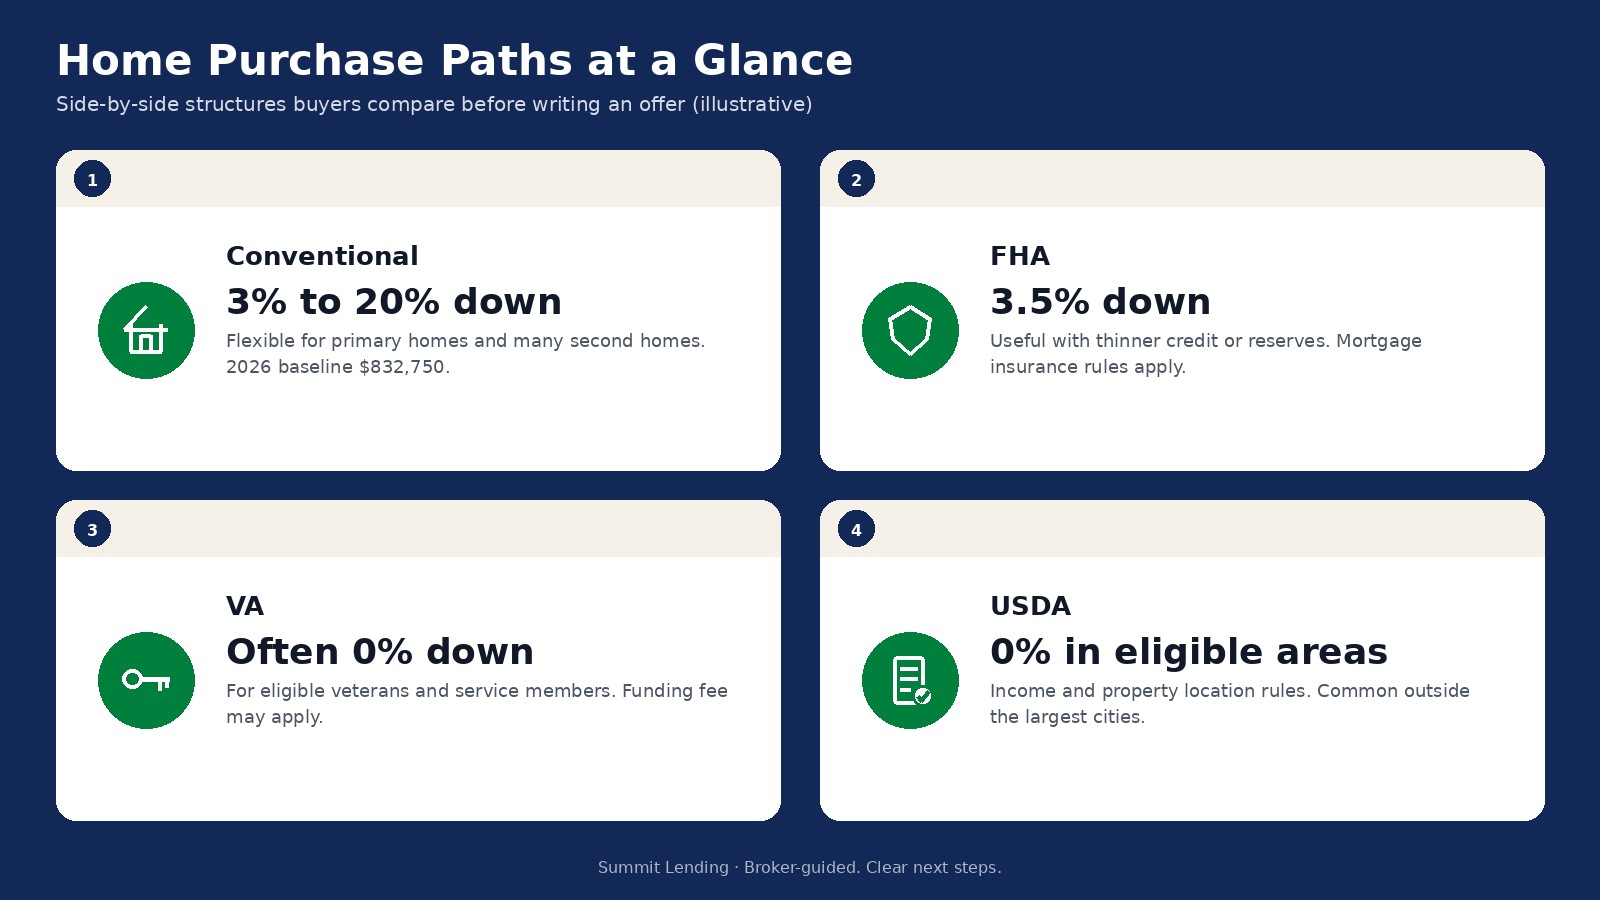
- Conventional loans. Often the first stop when credit and reserves are solid. Down payments commonly run from about 3% to 20%+ for a primary home. FHFA set the 2026 one-unit conforming limit at $832,750 in most counties (high-cost ceiling $1,249,125). Larger loans usually move into jumbo territory.
- FHA loans. Useful when credit is thinner or cash is tight. Typical minimum down payment is 3.5% when you qualify, with mortgage insurance rules that differ from conventional.
- VA loans. For eligible veterans, service members, and some surviving spouses. Often 0% down, with a funding fee that may be financed. See how we frame offers on the state purchase hubs below.
- USDA Rural Development. 0% down can be available in eligible locations when household income and property rules fit. Many areas outside the largest cities qualify on location alone.
State and local down payment assistance can stack with some of these programs. We compare assistance honestly with a plain conventional or FHA file so you see the true payment and restrictions. First-time buyers should also read first-time home buyer.
Where we help buyers purchase
Start with your state, then drill into the county or city you are shopping:
- Utah: Utah purchase loans, plus Utah mortgages, Salt Lake County, Utah County, Davis County, Weber County, and Washington County.
- Texas: Texas purchase loans, Texas mortgages, Harris County, Dallas County, Tarrant County, Travis County, Bexar County, and Collin County.
- Idaho: Idaho purchase loans, Idaho mortgages, Ada County, and Canyon County.
- Wyoming: Wyoming purchase loans and Wyoming mortgages.
Arkansas and Arizona are part of our licensed footprint as well. Ask us which local pages fit your search.
Steps that keep a purchase on track
- Get preapproved with verified income and credit. Soft online "prequal" letters rarely convince a listing agent.
- Model the full payment. Taxes, insurance, mortgage insurance, and HOA dues can add hundreds a month.
- Line up cash to close and reserves. Down payment is only part of the check you write.
- Compare two or three programs on the same house. The cheapest rate is not always the cheapest loan over the years you expect to own it.
- Keep credit quiet until you close. New cars, furniture financing, and large cash transfers create underwriting friction.
Related Summit Lending pages
Browse the full mortgage loans menu, refinance if you already own, construction loans if you are building, reverse mortgages for later-life options, and commercial loans for business-use property. Builders can start in the Builder Portal.
Talk with a purchase loan broker
Tell us the markets you are shopping, your timeline, and how much cash you want to bring. We will map a few purchase options and a document checklist so the underwriting path is clear before you write an offer.
Cash to close, beyond the down payment
Buyers often budget for down payment and forget the rest. Closing costs, prepaid taxes and insurance, HOA transfer fees, and the first months of utilities and furniture can add thousands. If a family member is gifting funds, get the gift letter and paper trail ready before underwriting asks. If you are selling another home to buy, we map timing risk so you are not forced into a bridge you did not plan for.
Mortgage insurance deserves a plain explanation too. FHA mortgage insurance and Conventional PMI are not the same product. We show when PMI can be removed on Conventional loans and how FHA rules differ, so a low down payment does not create a surprise you only notice after the first escrow statement.
For a second home or investment purchase, expect larger down payments and tighter overlays. Start on the state purchase hubs linked above, or talk through investor needs on commercial loans when the property no longer fits a consumer box.
Offer strategy when rates sit near survey highs
With the Freddie Mac 30-year survey near 7.28% in early October 2026, payment comfort matters more than winning every bidding war. A clean preapproval, flexible closing dates, and realistic appraisal gaps often beat an inflated price that breaks your budget. If inventory is softer in your county, you may have room to negotiate repairs or closing cost help. If the neighborhood is still hot, speed and certainty matter more.
We also talk rate-lock strategy once you are under contract. Locking too early on a long close can be expensive; locking too late creates stress. The right call depends on your contract timelines and risk tolerance, not a social media tip.
Property types and occupancy
Most purchase files are owner-occupied single-family homes. Townhomes and warrantable condos can work when project guidelines pass. Manufactured housing, unique acreage, and non-warrantable condos need earlier screening. Second homes and investment purchases usually require more down payment and stronger reserves. Tell us occupancy up front so we do not waste a week on a program the property cannot use.
If you are buying land only, or buying a home you intend to rebuild, the better doorway may be construction loans rather than a standard purchase mortgage.
Information on this page is for general education. It is not a commitment to lend. Loan availability, terms, and pricing depend on your credit, income, assets, property, and lender overlays. Summit Lending LLC, NMLS 2394434.
Related Articles
Mortgage Rates Above 7%: What Utah Buyers Should Do Now (Sept 2026)
Freddie Mac’s 30-year fixed averaged 7.03% the week of September 24, 2026, after the Fed’s mid-month hike. Here is how Utah buyers and homeowners can plan payments, use improving Salt Lake County inventory, and keep the 6% normalization mindset honest when headlines sit above 7%.
Utah Seller Concessions and Rate Buydowns in a Higher-Inventory Fall Market (Oct 2026)
With Salt Lake County at 4.2 months of supply and sellers offering more credits nationally (Redfin via Deseret News, Sept 22, 2026), Utah buyers can negotiate closing cost help and rate buydowns on resale homes. Here is how to structure the ask without guessing.
Texas Property Taxes and Home Insurance: Budgeting the Real Mortgage Payment (Oct 2026)
Texas property tax bills go out in October, Harris and Dallas counties just raised rates, and TDI shows insurers filing for lower rates on average. Here is how the $140,000 homestead exemption, escrow, and insurance shape the payment you will actually make.
ARM or Fixed at 7.28%? An Idaho Homebuyer's Guide (October 2026)
Freddie Mac's 30-year fixed hit 7.28% on Oct. 1, 2026, and ARMs climbed to 10.3% of applications. Here is how a 5-year ARM really compares with a fixed loan on a $595,000 Ada County home, including resets, caps, and the qualifying rule most buyers miss.
Wyoming Low Down Payment Loans at 7.49%: FHA, VA, USDA, and WCDA Compared (Oct 2026)
MBA's 30-year rate hit 7.49% this week, and FHA purchase applications fell the most. Here is how FHA, VA, USDA, conventional 3% down, and WCDA's Home$tretch help compare on a $386,000 Cheyenne home, including cash to close and the full monthly payment.
Texas Buyer's Market at 7.40%: How to Negotiate Price Cuts, Seller Credits, and Buydowns (Oct 2026)
Freddie Mac's 30-year average hit 7.40% on Oct. 8, while 69% of Texas Realtors say their buyers faced no competing offers this year. Here is how a price cut, seller credit, and rate buydown compare on an Austin-area home, plus the Texas contract tools that protect you.
How Much Income Do You Need to Buy a Utah Home at 7.40%? (Oct 2026)
Freddie Mac's 30-year average hit 7.40% on Oct. 8 while Wasatch Front sellers cut prices at some of the fastest rates in the country. Here is the income a lender would look for on $400,000 to $700,000 Utah homes, including the $569,900 statewide median ask, and the levers that lower it.
New Construction vs. Resale in Idaho at 7.40%: How to Compare Builder Incentives (Oct 2026)
Freddie Mac's 30-year average hit 7.40% on Oct. 8, and September MLS data put Ada County's new construction median about $61,600 above resale. Here is how to price a builder's rate buydown or cash credit against a resale home, with Treasure Valley numbers and the Idaho tax rules that change a new-build budget.
What Does a $475,000 Phoenix Home Cost at 7.40%? Full PITI (Oct 2026)
Freddie Mac's 30-year average hit 7.40% on Oct. 8 as Greater Phoenix pending sales plunged about 40% in September. Here is what a $475,000 Valley home really costs each month once you add taxes, insurance, HOA, and mortgage insurance, and how a price cut changes that number more than a closing credit.
Arkansas Mortgage Payments at 7.40%: Bentonville vs. Little Rock vs. Jonesboro (Oct 2026)
Freddie Mac's 30-year average held at 7.40% on Oct. 15, but an Arkansas payment depends on much more than the rate. Here is the full monthly cost of typical homes in Bentonville, Fayetteville, Little Rock, and Jonesboro, how school district millage and the new $675 homestead credit change it, and where ADFA down payment help fits.
Wyoming Prop 1 Property Tax Vote: What It Means for Your Mortgage Payment at 7.40% (Oct 2026)
Wyoming voters decide Prop 1 on November 3. It would exempt 50% of a primary home's dwelling value, but not the land, so it is not half off your tax bill. Here is how it compares with today's 25% homeowner exemption, what it does to payments in Cheyenne, Casper, and Gillette at 7.40%, and what buyers closing this fall should file now.
Texas Down Payment Assistance at 7.40%: What TDHCA and TSAHC Help Really Costs (Oct 2026)
Texas down payment assistance is still available with rates at 7.40%, but the help usually comes with a higher rate. Using the TDHCA and TSAHC rate sheets from Oct. 19, 2026, here is what 2% to 5% assistance really costs each month on a $325,000 home, when it must be repaid, how the 15% MCC works, and which program fits your plans.
Utah Housing's New FirstHome Conventional Loan: Payment Math at 7.40% and the $20,000 New-Build Help (Oct 2026)
Utah Housing Corporation opened FirstHome Conventional on October 19: a lower-rate conventional option for first-time buyers with no upfront mortgage insurance and reduced MI at or below 80% AMI. Here is how it compares with 7.40% market loans on a $440,000 new build, the county limits, and how to use the state's $20,000 new-construction money.
Buying in Tucson at 7.32%: The $370,000 Payment, Pima County's 4% Help, and the Phoenix Gap (Oct 2026)
Freddie Mac's average dipped to 7.32% on Oct. 22, and Realtor.com says Tucson and Phoenix are tilting toward buyers. Here is the full monthly cost of the $370,000 Tucson median on FHA, conventional, and VA loans, what each tier of Pima County's forgivable down payment help costs in rate, why the Edge option often wins, and the real gap with Phoenix.Frequently Asked Questions
Everything you need to know about home mortgage loansYour ideal loan depends on several factors like your financial situation, long term goals, and risk tolerance. Fixed rate mortgages offer stability, while adjustable rate loans may save you money initially. Government-backed options can be great for those with lower credit scores. At Summit Lending, we’ll guide you through the options to find a perfect fit.