Buying your first home?
3% down on conventional loans, 3.5% with FHA
We line up down payment assistance, credit prep and pre-approval for first-time buyers, so you know your payment and cash to close before you make an offer.
See first-time buyer optionsWyoming home purchase loans, compared across lenders
Buying a home in Wyoming looks different depending on where you are. A starter home in Casper or Gillette, a newer build in Cheyenne, and a property near Jackson in Teton County can need completely different loans. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed in Wyoming. We compare purchase loans from multiple wholesale lenders so you can see real differences in rate, fees, down payment, and mortgage insurance before you write an offer.
Below is a practical guide to Wyoming purchase options, 2026 limits, help from the Wyoming Community Development Authority, and how the process works with us. To test a payment first, use the Wyoming mortgage calculator.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
The Wyoming market this fall
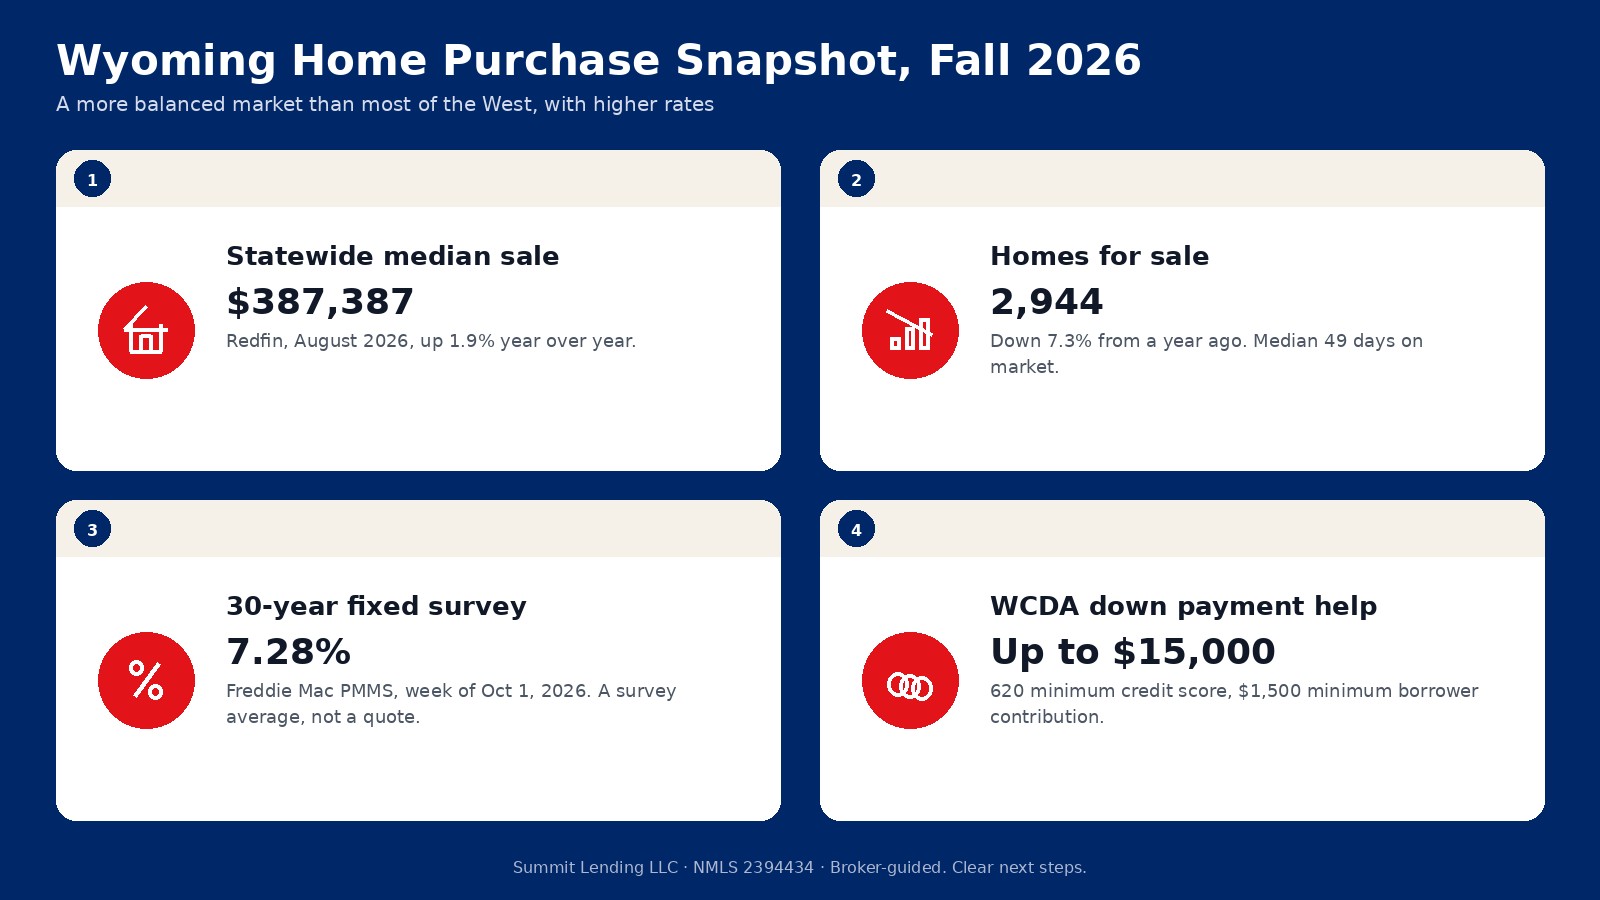
Redfin put Wyoming's statewide median sale price at about $387,387 for August 2026, up 1.9% from a year earlier. Sales picked up, with about 653 homes sold, up 15.5%, and the typical home sold in about 49 days. Supply got tighter at roughly 2,944 homes for sale, down 7.3% (Redfin Wyoming data). With fewer listings and more sales, a buyer who already has a preapproval in hand is in a better spot to act when the right house appears.
Freddie Mac's weekly survey put the average 30-year fixed rate at 7.28% for the week of October 1, 2026, up from 7.03% a week earlier and 6.34% a year ago (Freddie Mac PMMS; history on FRED). On a $348,300 loan, that is about $2,383 a month in principal and interest, versus about $2,165 at last year's rate. These are national averages, not a quote, so we price your scenario directly.
Purchase loan options for Wyoming buyers
Conventional
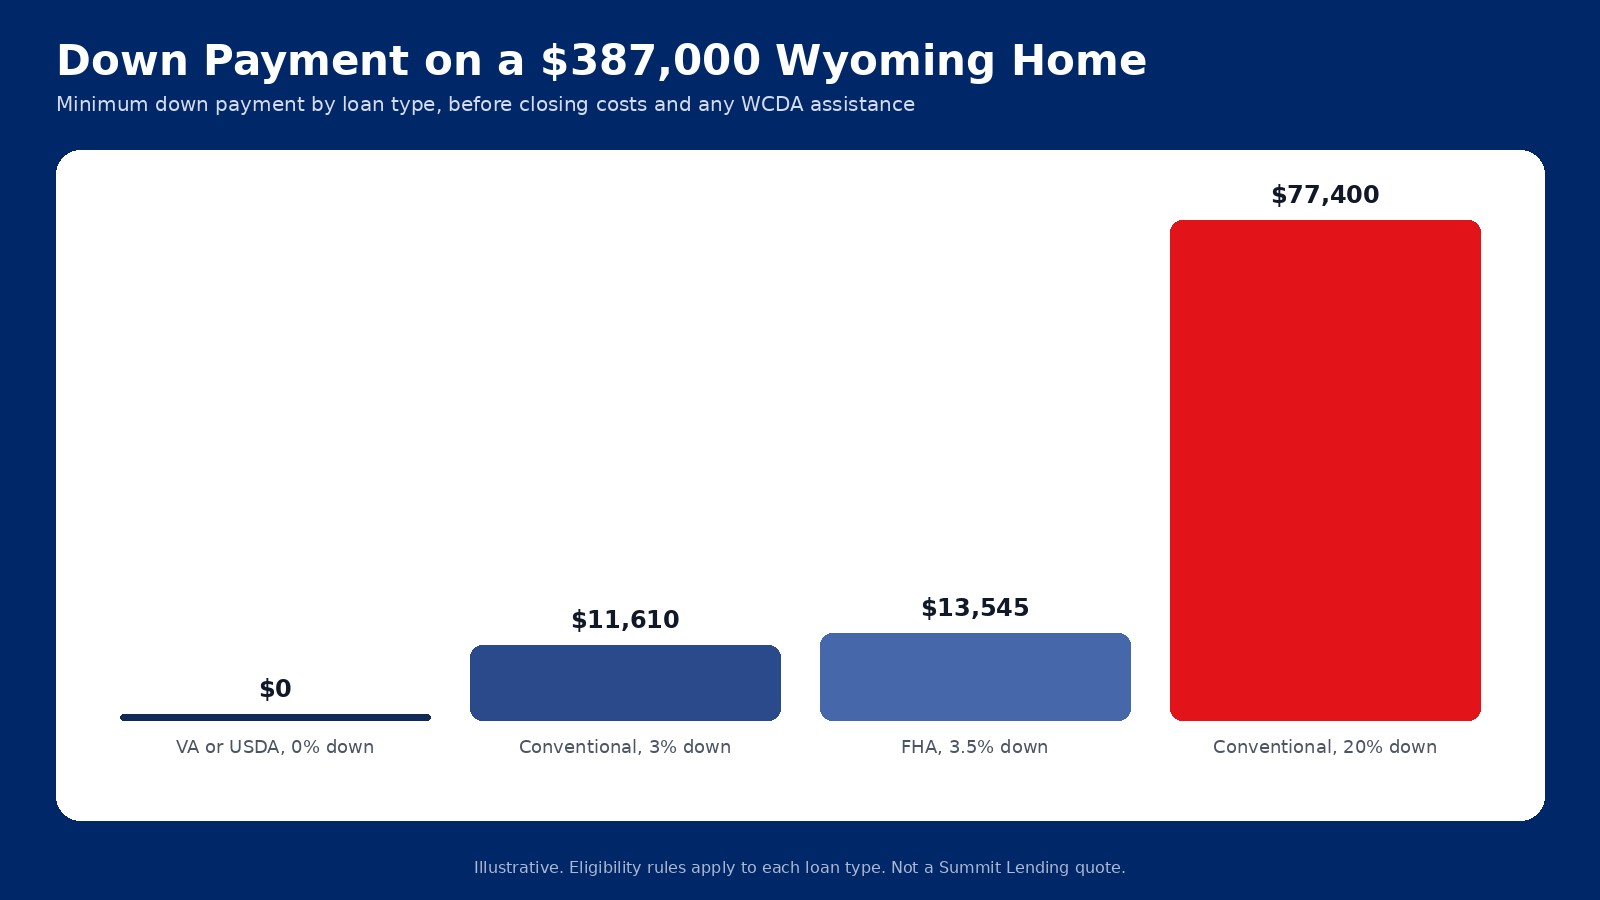
Qualified buyers can put as little as 3% down on a one-unit primary home (Fannie Mae eligibility matrix), which is about $11,610 on a $387,000 home. Private mortgage insurance applies below 20% down, and you can request cancellation once you reach 80% of the original value (CFPB on PMI). Putting 20% down, about $77,400 at that price, avoids PMI entirely.
FHA
FHA loans allow 3.5% down, about $13,545 on $387,000, with a 580 or higher credit score, and they are more flexible on credit history (HUD FHA overview). FHA adds a 1.75% upfront premium, usually financed, and an annual premium of 0.55% for most loans with less than 5% down (HUD Mortgagee Letter 2023-05).
VA
Eligible veterans and service members can buy with no down payment and no monthly mortgage insurance (VA purchase loans). A funding fee of 2.15% applies on first use with less than 5% down, dropping to 1.5% with 5% down and 1.25% with 10% down, unless you are exempt (VA funding fee). If you are stationed at F.E. Warren Air Force Base in Cheyenne, or you are a veteran anywhere in the state, check your VA eligibility early.
USDA
USDA guaranteed loans allow no down payment in eligible rural areas for households under the income limits (USDA guaranteed loans). Much of Wyoming is rural, so it is worth checking an address on the USDA eligibility map.
Jumbo
Loans above the conforming limit are jumbo loans with their own pricing and down payment rules. In Wyoming, that mostly comes up in and around Jackson.
2026 loan limits in Wyoming
The 2026 conforming limit for a one-unit home is $832,750 in 22 of Wyoming's 23 counties, and $1,249,125 in Teton County (FHFA announcement, FHFA county file). For FHA, 21 of 23 counties sit at the national floor of $541,287. Teton County is at the $1,249,125 ceiling, and Uinta County (the Evanston area) is $579,600 (HUD announcement, HUD lookup).
WCDA help for Wyoming buyers
The Wyoming Community Development Authority is the state housing finance agency, and its programs are offered through participating lenders. WCDA down payment assistance can provide up to $15,000 with a 620 minimum credit score and a $1,500 minimum borrower contribution, and its Home$tretch option offers 0% interest assistance for eligible buyers (WCDA homebuyers). Purchase price and income limits apply by county (WCDA limits). WCDA reports helping more than 62,000 Wyoming families buy homes (WCDA annual report). Our Wyoming first-time home buyer page covers the details.
Wyoming costs to plan for
- Property tax and the homeowner exemption. A 2025 law exempts 25% of fair market value on the first $1,000,000 for owner-occupied single-family homes, if you have lived in the home at least eight months and file an affidavit (SF0069; Wyoming Department of Revenue). A seller's tax bill may include an exemption you will not receive in your first year.
- Insurance. Wind and hail, and wildfire risk on some rural parcels, can affect cost and availability. Get a quote on the address early.
- Wells, septic, and access. Rural properties may need well and septic inspections and confirmation of legal access. Some loan programs require them.
- HOA dues. Dues count toward your debt-to-income ratio (CFPB on DTI).
- No state income tax. Wyoming does not have a state individual income tax (Wyoming Department of Revenue), which can help a monthly budget.
How a Wyoming purchase works with Summit
- Budget and preapproval. We review credit, income, and assets and issue a letter you can send with offers. Lenders use prequalification and preapproval differently, so what matters is what was verified (CFPB comparison). Multiple mortgage credit checks within 45 days count as one inquiry (CFPB).
- Offer and Loan Estimate. Once you are under contract, your Loan Estimate arrives within three business days of application (CFPB on Loan Estimates).
- Appraisal, title, and underwriting. We clear conditions and keep your agent informed.
- Closing. Your Closing Disclosure arrives at least three business days before signing (CFPB on Closing Disclosures).
Where we help Wyoming buyers
Cities: Cheyenne, Casper, Laramie, Gillette, Rock Springs, Evanston, and Cody. Counties: Laramie County, Natrona County, Campbell County, Sweetwater County, Albany County, Sheridan County, Park County, Fremont County, Teton County, Uinta County, and Lincoln County.
Related pages
Start a Wyoming preapproval, compare Wyoming refinance options, or read about Wyoming reverse mortgages and Wyoming construction financing in Cheyenne and Casper. The Wyoming mortgage overview and the national purchase loans page cover the rest, including Utah, Idaho, and Texas.
Sources
- Redfin, Wyoming housing market
- Freddie Mac PMMS, Oct 1, 2026 release
- FRED, 30-Year Fixed Rate Mortgage Average
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- HUD, Let FHA loans help you
- HUD Mortgagee Letter 2023-05, FHA annual MIP (PDF)
- VA purchase loan
- VA funding fee and closing costs
- VA home loan eligibility
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- FHFA, 2026 conforming loan limits
- FHFA 2026 county loan limit list
- HUD No. 25-145, 2026 FHA loan limits
- HUD FHA mortgage limits lookup
- Wyoming Community Development Authority, homebuyers
- WCDA purchase price and income limits
- WCDA 2025 annual report (PDF)
- Wyoming SF0069 (2025), homeowner tax exemption (PDF)
- Wyoming Department of Revenue, homeowner exemption
- CFPB, debt-to-income ratio
- Wyoming Department of Revenue
- CFPB, prequalification vs. preapproval
- CFPB, when a lender checks your credit
- CFPB, What is a Loan Estimate?
- CFPB, What is a Closing Disclosure?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.
Have a construction project?
See our construction loan calculator and pricing options for one-time and two-time close loans.
Explore construction loansRelated Articles
Wyoming Low Down Payment Loans at 7.49%: FHA, VA, USDA, and WCDA Compared (Oct 2026)
MBA's 30-year rate hit 7.49% this week, and FHA purchase applications fell the most. Here is how FHA, VA, USDA, conventional 3% down, and WCDA's Home$tretch help compare on a $386,000 Cheyenne home, including cash to close and the full monthly payment.
Wyoming Prop 1 Property Tax Vote: What It Means for Your Mortgage Payment at 7.40% (Oct 2026)
Wyoming voters decide Prop 1 on November 3. It would exempt 50% of a primary home's dwelling value, but not the land, so it is not half off your tax bill. Here is how it compares with today's 25% homeowner exemption, what it does to payments in Cheyenne, Casper, and Gillette at 7.40%, and what buyers closing this fall should file now.Frequently Asked Questions
Everything you need to know about home mortgage loans in WyomingYour ideal loan depends on several factors like your financial situation, long term goals, and risk tolerance. Fixed rate mortgages offer stability, while adjustable rate loans may save you money initially. Government-backed options can be great for those with lower credit scores. At Summit Lending, we’ll guide you through the options to find a perfect fit.