Wyoming Mortgage Refinance
Refinancing a Wyoming home: when it pays and when it does not
A refinance replaces your current mortgage with a new one. Wyoming homeowners do it to lower a rate, shorten a term, drop mortgage insurance, take cash out for a project, or move off an adjustable rate. With rates higher this fall than a year ago, not every refinance makes sense, and part of our job is telling you when waiting is the better move. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed in Wyoming, based in Garland, Utah. We price your refinance with multiple wholesale lenders and show you the break-even math before anyone orders an appraisal.
Want to check the payment first? Use the Wyoming mortgage calculator.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
Where rates stand this fall
Freddie Mac's weekly survey put the average 30-year fixed rate at 7.28% for the week of October 1, 2026, up from 7.03% a week earlier and 6.34% a year ago. The 15-year average was 6.60% (Freddie Mac PMMS; history on FRED). These are national averages for strong-credit borrowers, updated every Thursday (PMMS page), not a Wyoming quote.
If you bought or refinanced in the last year, today's rates probably do not beat yours. If your rate is meaningfully higher, the math can work. As a hypothetical, on a $280,000 balance, moving from 8.00% to 7.25% on a new 30-year loan cuts principal and interest from about $2,055 to about $1,910, saving about $144 a month. Whether that is worth it depends on the costs and how long you stay, which we cover below.
Types of refinance in Wyoming
Rate-and-term refinance
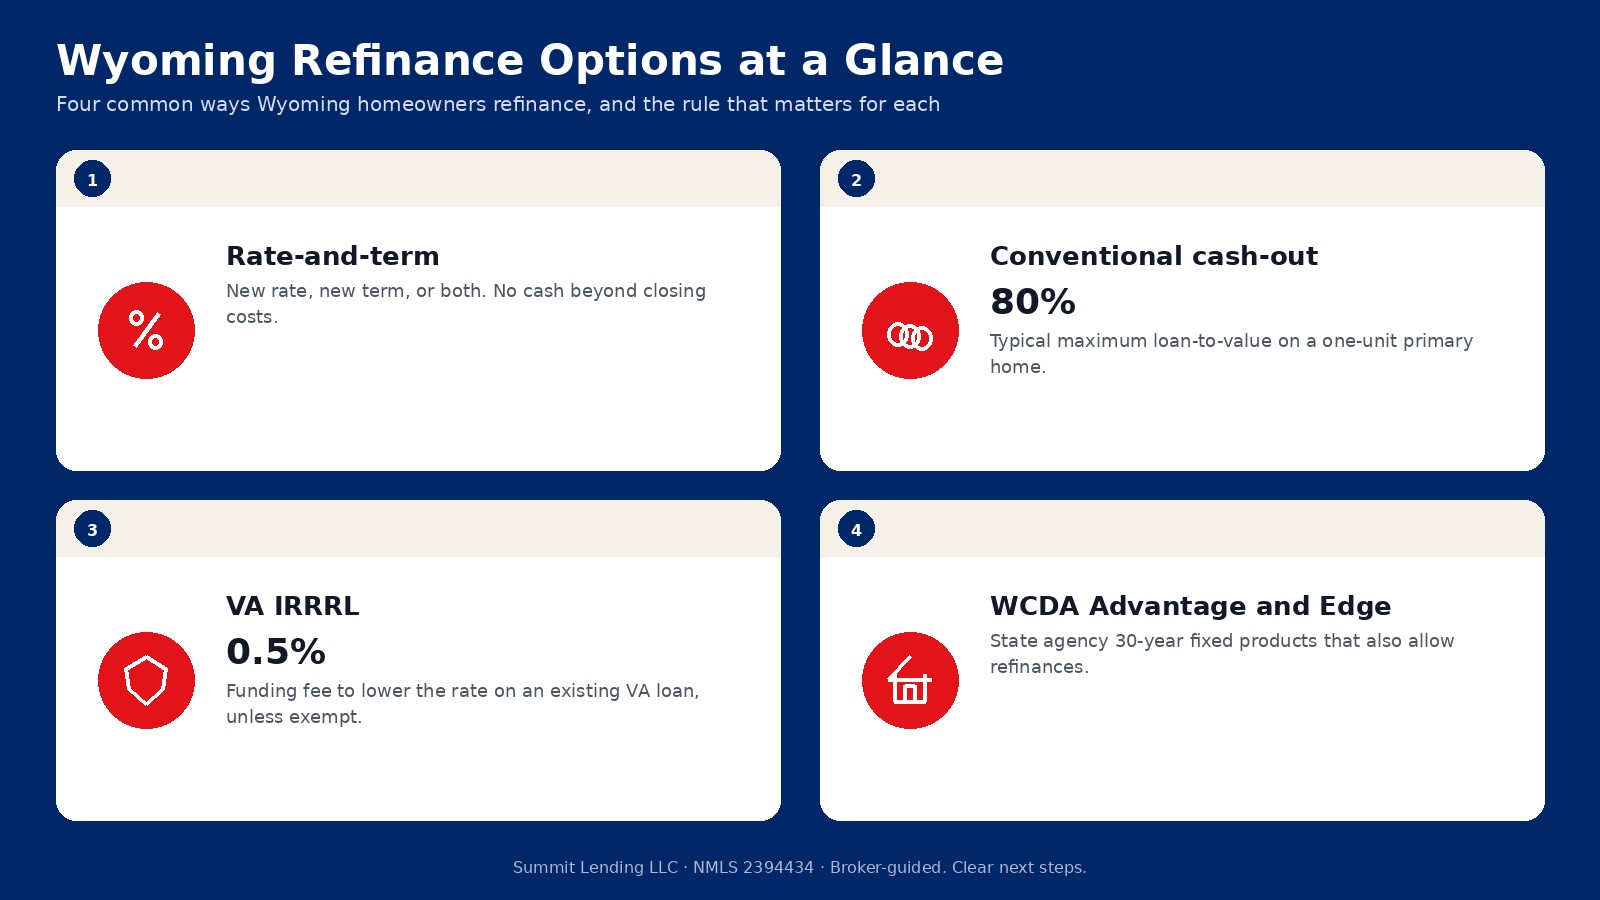
You replace your loan to change the rate, the term, or both, without taking cash beyond closing costs. It is the most common choice when rates fall, and the right one when you want to go from a 30-year to a 15-year. At 6.60%, a 15-year payment on $280,000 is about $2,455 a month.
Cash-out refinance
The CFPB describes a cash-out refinance as replacing your mortgage with a larger loan and taking the difference in cash (CFPB on cash-out refinancing). For a conventional loan on a one-unit primary home, the maximum loan-to-value for cash-out is generally 80% (Fannie Mae eligibility matrix). FHA also offers cash-out refinances, generally up to 80% of value for owner-occupants under its handbook rules (HUD Handbook 4000.1).
FHA Streamline
If you have an FHA loan now, an FHA Streamline refinance can lower your rate with reduced documentation and often no appraisal, as long as the new loan produces a net tangible benefit under HUD's rules (HUD Handbook 4000.1).
VA refinances
Veterans with a VA loan can use the Interest Rate Reduction Refinance Loan (IRRRL) to lower the rate, with a 0.5% funding fee unless exempt (VA IRRRL, VA funding fee). A VA cash-out refinance can replace any loan type for eligible borrowers (VA cash-out). Wyoming has a meaningful military community around F.E. Warren Air Force Base and Cheyenne.
WCDA refinances
The Wyoming Community Development Authority is known for first-time buyer programs, but its Advantage and Edge loans also allow refinances, with no first-time buyer requirement and a 620 minimum credit score (WCDA). Income limits apply (WCDA limits). If your existing loan is a WCDA loan, ask about it specifically.
How much cash can you take?
Say your Wyoming home is worth $390,000, close to the statewide median of about $387,387 that Redfin reported for August 2026 (Redfin Wyoming data). Eighty percent of that is $312,000, the most a conventional cash-out loan would typically allow. If you owe $250,000, the new loan pays it off and leaves up to $62,000 before closing costs. Lenders may set tighter limits by credit score and property type, and homes on larger acreage can have their own appraisal and eligibility rules, so we check your real number against several lenders.
Is a Wyoming refinance worth it? Four checks
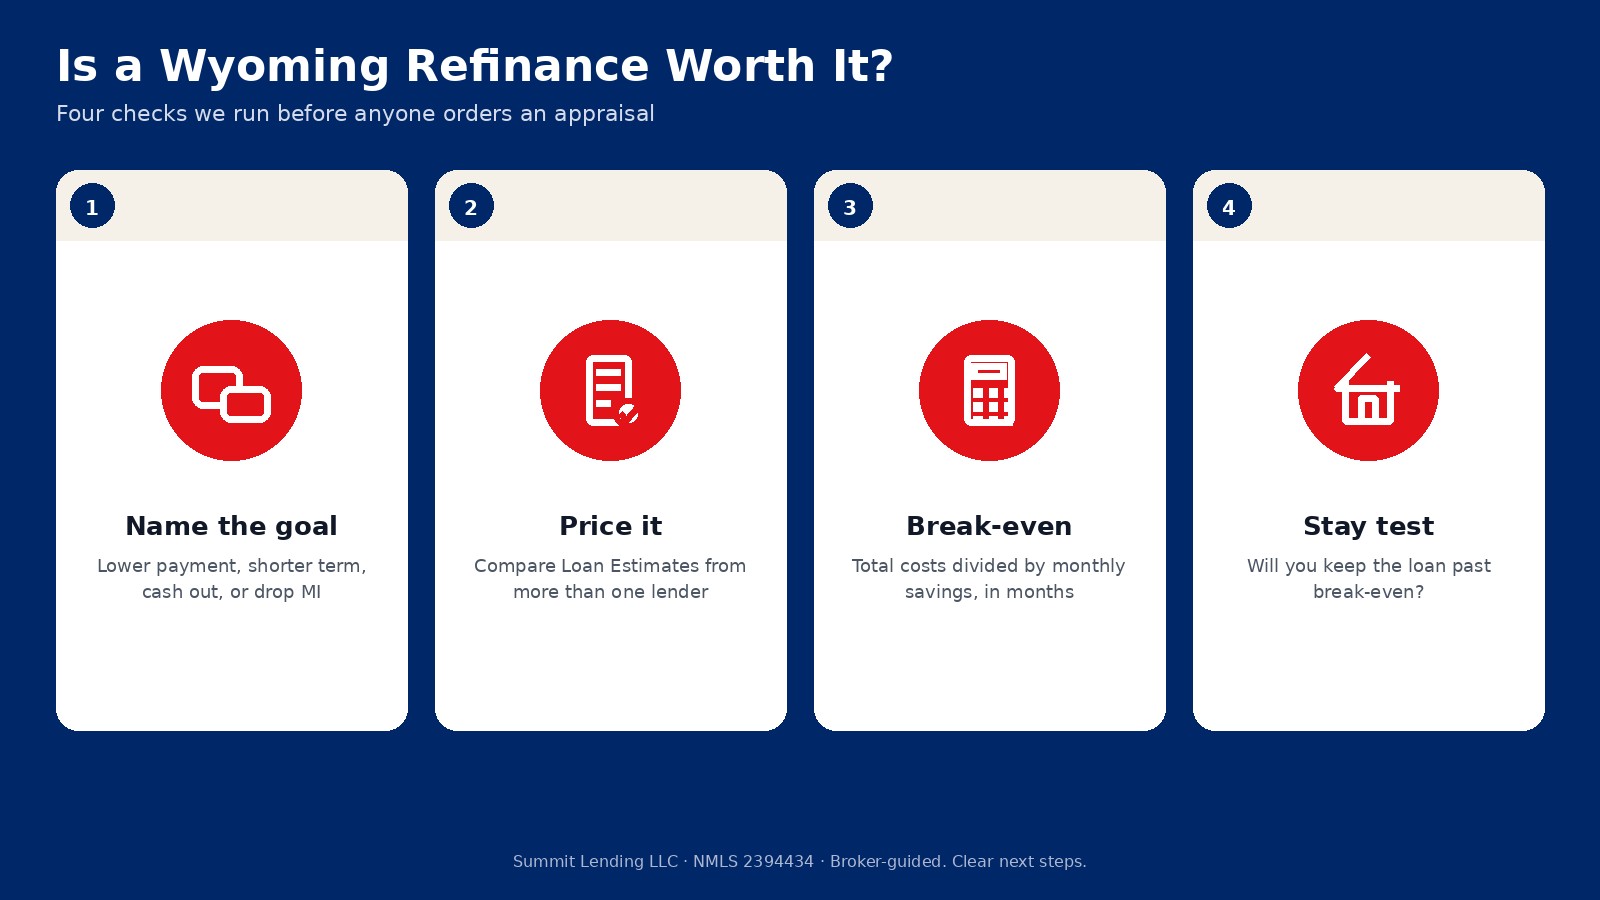
- Name the goal. A lower payment, a shorter term, cash for a project, dropping mortgage insurance, or changing who is on the loan. Each points to a different product.
- Price it. Compare Loan Estimates from more than one lender on the same day (CFPB on Loan Estimates).
- Figure the break-even. Divide total costs by monthly savings. In the hypothetical above, if the refinance costs $6,000 and saves about $144 a month, it takes about 42 months to break even.
- Decide how long you will stay. If you will likely sell or refinance again before the break-even point, the refinance probably costs more than it saves.
One caution: restarting a 30-year term can lower the payment while raising total interest. If you are 8 years into your current loan, ask us to price a 20-year or 25-year term too, or plan to pay extra principal.
Dropping mortgage insurance
If home values have risen since you bought, you may be able to drop PMI on a conventional loan without refinancing at all. Under federal rules, PMI generally ends automatically when your balance is scheduled to reach 78% of the original value, and you can ask to remove it once you reach 80% if you meet the requirements, which can include a current appraisal (CFPB on removing PMI). FHA annual premiums work differently and often last for the life of the loan, which is why some Wyoming homeowners refinance from FHA to conventional once they have 20% equity.
Wyoming costs and details to plan for
- Appraisal. Most cash-out loans need one. Some rate-and-term and streamline programs do not.
- Title and recording. A lender's title policy and county recording fees.
- Escrow reset. The new loan may need a fresh escrow deposit for taxes and insurance. Your old escrow balance is refunded by the prior servicer afterward.
- Homeowner exemption. Wyoming's 2025 law created a homeowner exemption of 25% of fair market value on the first $1,000,000 of value for qualifying owner-occupied homes, with an affidavit required (SF0069; Wyoming Department of Revenue). A refinance does not change your eligibility, but make sure it is on file so your escrow is set on the right tax amount.
- Loan limits. The 2026 conforming limit is $832,750 for a one-unit home in most of Wyoming and $1,249,125 in Teton County (FHFA). FHA limits vary by county (HUD lookup).
- Right to cancel. When you refinance your primary home with a new lender, federal rules generally give you three business days after closing to cancel, so funds are released after that period (Regulation Z 1026.23).
How a Wyoming refinance works with Summit
- Quick review. Your current loan, goal, estimated value, and credit. Several mortgage credit checks within 45 days count as one inquiry for most scoring models (CFPB).
- Compare lenders. We price your scenario with multiple wholesale lenders. Your Loan Estimate comes within three business days of application.
- Appraisal and underwriting. We order what the program requires and clear conditions.
- Closing. Your Closing Disclosure arrives at least three business days before signing (CFPB on Closing Disclosures), then the rescission period runs before funding.
Where we help Wyoming homeowners refinance
Cities: Cheyenne, Casper, Laramie, Gillette, Rock Springs, Evanston, Cody, Lander, Rawlins, Powell, and F.E. Warren AFB. Counties: Laramie County, Natrona County, Campbell County, Sweetwater County, Albany County, Sheridan County, Park County, Fremont County, Teton County, Uinta County, and Lincoln County.
Related pages
See the Wyoming mortgage overview, Wyoming purchase loans, Wyoming preapproval, Wyoming first-time home buyer guide, and Wyoming reverse mortgages. We also help homeowners refinance in Utah, Idaho, and Texas.
Sources
- Freddie Mac PMMS, Oct 1, 2026 release
- FRED, 30-Year Fixed Rate Mortgage Average
- Freddie Mac Primary Mortgage Market Survey
- CFPB, cash-out refinance
- Fannie Mae Eligibility Matrix
- HUD Single Family Housing Policy Handbook 4000.1
- VA Interest Rate Reduction Refinance Loan
- VA funding fee and closing costs
- VA cash-out refinance loan
- Wyoming Community Development Authority, homebuyers
- WCDA purchase price and income limits
- Redfin, Wyoming housing market
- CFPB, What is a Loan Estimate?
- CFPB, how to get rid of PMI
- Wyoming SF0069 (2025), homeowner tax exemption (PDF)
- Wyoming Department of Revenue, homeowner exemption
- FHFA, 2026 conforming loan limits
- HUD FHA mortgage limits lookup
- CFPB, Regulation Z 1026.23, right of rescission
- CFPB, when a lender checks your credit
- CFPB, What is a Closing Disclosure?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.