Wyoming Mortgage Loans
Wyoming mortgage loans, from Cheyenne to Jackson
Wyoming is a big state with a small population, and its housing market behaves like a collection of very different towns: a capital city tied to the Colorado Front Range, energy communities in Gillette and Rock Springs, a university town in Laramie, ranch country, and Teton County, one of the most expensive housing markets in the country. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed in Wyoming and based in Garland, Utah. We compare loans from multiple wholesale lenders for Wyoming purchases and refinances, so you get options matched to your town, your property, and your finances.
This page is the hub for everything Summit offers in Wyoming: purchase loans, refinancing, first-time buyer help, preapproval, reverse mortgages, and commercial lending. To try numbers first, open the Wyoming loan calculator.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
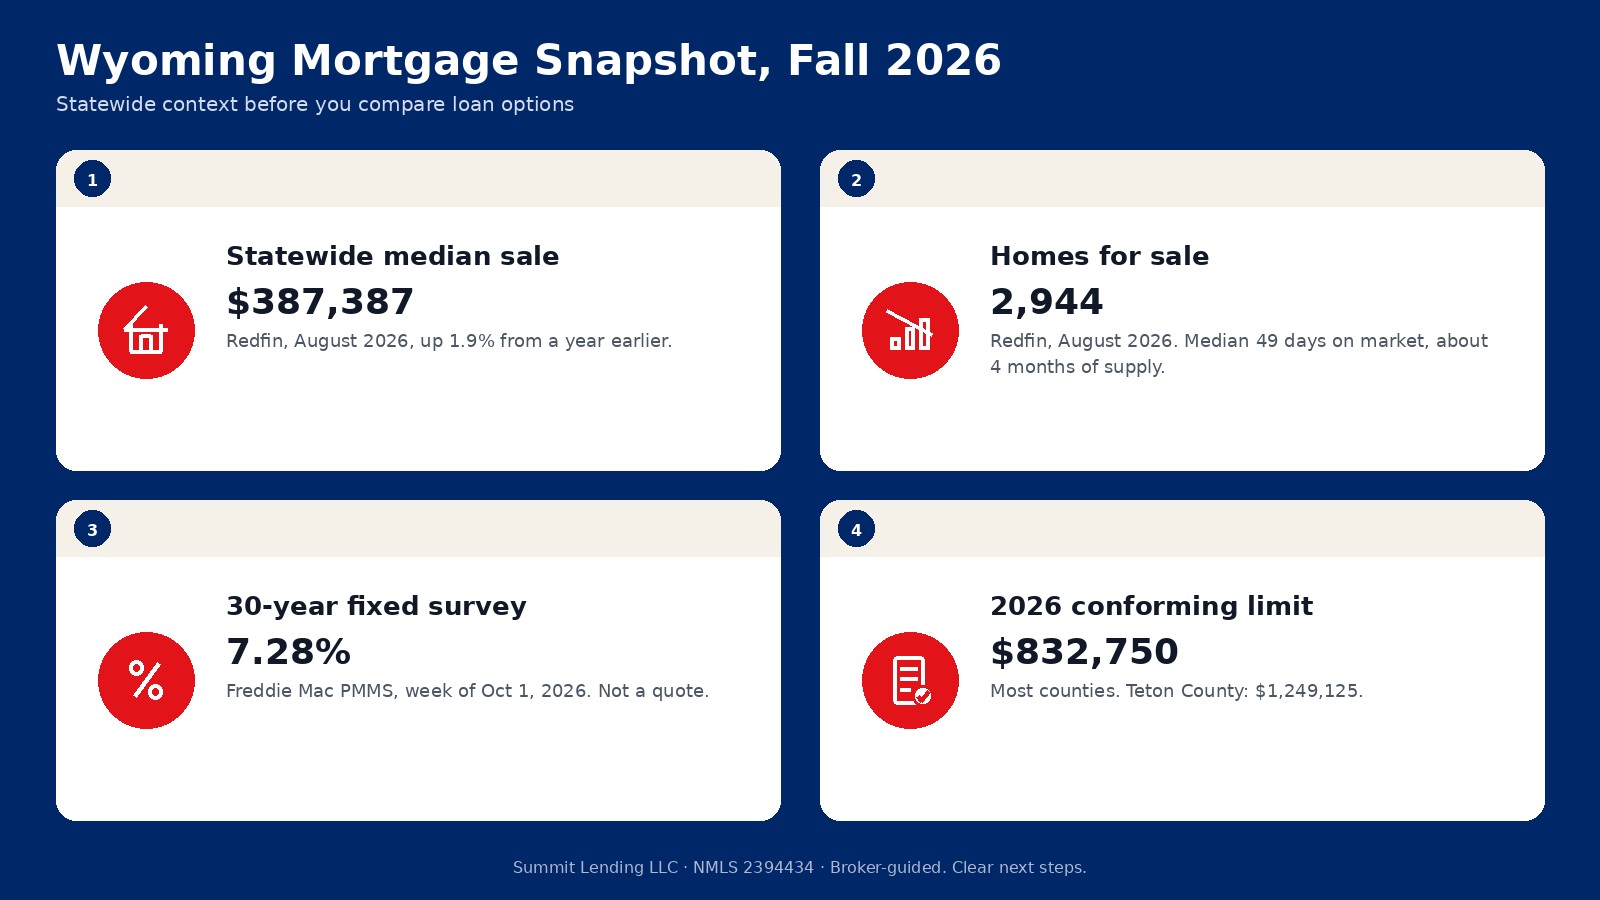
The Wyoming market this fall
Redfin reported a Wyoming median sale price of about $387,387 for August 2026, up 1.9% from a year earlier. Homes sold rose 15.5% to 653, inventory fell 7.3% to about 2,944 homes for sale, and the median home spent 49 days on market, roughly four months of supply (Redfin Wyoming data). That is a more balanced market than many Western states, which gives buyers room to negotiate on inspection items and seller-paid closing costs.
Rates are the headwind. Freddie Mac's survey put the average 30-year fixed rate at 7.28% for the week of October 1, 2026, compared with 7.03% a week earlier and 6.34% a year ago (Freddie Mac PMMS; history on FRED). Those are national averages, not quotes. Your rate depends on credit, down payment, loan type, and property.
Wyoming has no state personal income tax (Wyoming Department of Revenue). That does not change how lenders calculate qualifying income, but it does help many households' monthly budgets, which matters when you decide how much house is comfortable.
Loan options for Wyoming buyers and owners
Purchase loans
- Conventional: as little as 3% down for qualified buyers on a one-unit primary home; Fannie Mae allows up to 97% loan-to-value on eligible fixed-rate purchases (Fannie Mae Eligibility Matrix). PMI applies under 20% down and can be cancelled later (CFPB on PMI).
- FHA: 3.5% down at a 580 or higher credit score, with more flexible credit and debt guidelines (HUD FHA overview).
- VA: no down payment and no monthly mortgage insurance for eligible veterans and service members (VA purchase loans). Families connected to F.E. Warren Air Force Base in Cheyenne use VA loans often.
- USDA: much of rural Wyoming qualifies for no-down-payment USDA guaranteed loans for households under the income limits (USDA guaranteed loans, eligibility map).
- Jumbo: needed above the conforming limit, which mostly comes up in Teton County.
Details for each option live on Wyoming purchase loans.
Refinancing
Rate and term, cash-out, FHA streamline, and VA IRRRL refinances are all available. A VA IRRRL carries a 0.5% funding fee unless you are exempt and requires that costs be recouped within 36 months (VA funding fee, VA IRRRL). Conventional cash-out on a one-unit primary home generally tops out at 80% of value (Fannie Mae matrix). See Wyoming refinance options for the break-even test we use.
Reverse and commercial
Homeowners 62 and older can explore Wyoming reverse mortgages. Investors and business owners can review Wyoming commercial loans.
2026 loan limits in Wyoming
The 2026 one-unit conforming limit is $832,750 in 22 of Wyoming's 23 counties. Teton County is $1,249,125 (FHFA announcement, FHFA county file). HUD's 2026 FHA floor is $541,287 and its high-cost ceiling is $1,249,125 (HUD announcement); look up each county on the HUD limits tool. In most of the state, limits are not the constraint. In Jackson and the rest of Teton County, they often are.
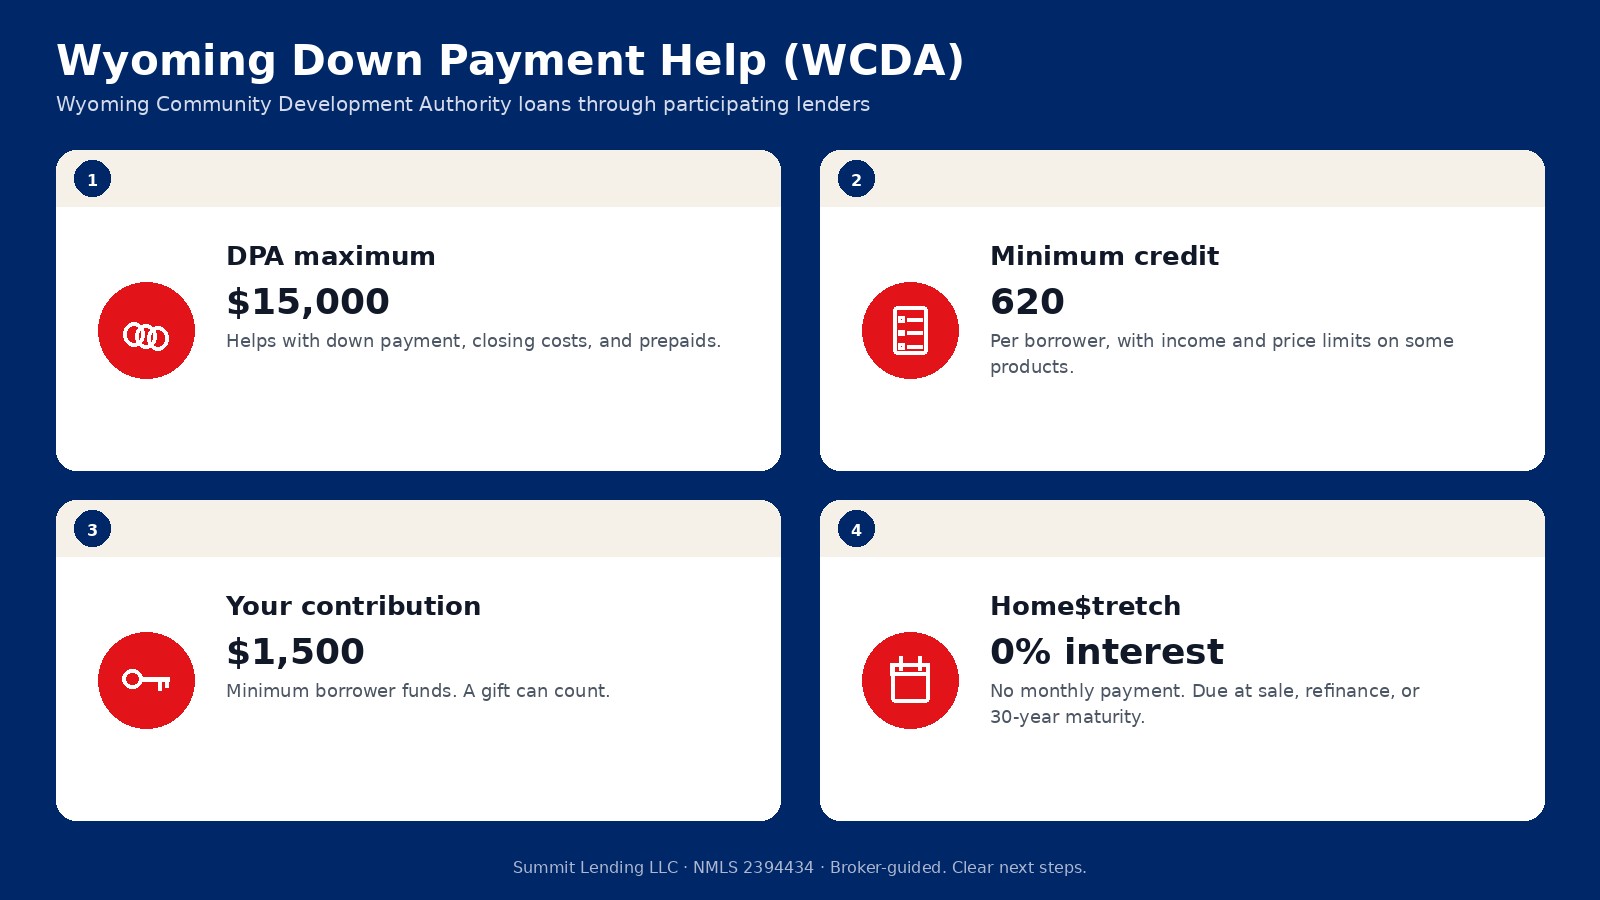
Down payment help from WCDA
The Wyoming Community Development Authority (WCDA) is the state housing finance agency. It offers first mortgages and down payment assistance through a network of participating lenders, with income and purchase price limits by county (WCDA homebuyers, WCDA limits). Key terms include:
- Down payment assistance of up to $15,000, usable for down payment, closing costs, and prepaid items.
- A minimum credit score of 620 and a minimum borrower contribution of $1,500.
- Home$tretch, a 0% second loan with no monthly payment, repaid when you sell, refinance, or reach the 30-year maturity. It is aimed at first-time buyers who complete homebuyer education.
- An amortizing assistance option paired with WCDA's Advantage loan.
WCDA's 2025 annual report says it has helped more than 62,000 Wyoming families buy homes (WCDA 2025 annual report). WCDA loans must go through one of its participating lenders. Ask us which WCDA paths we can arrange for your scenario, and if a different lender is a better fit for that program, we will tell you. More on first-time buyer options is on Wyoming first-time home buyer programs.
Wyoming details worth planning for
- Rural properties. Acreage, wells, septic systems, and outbuildings affect appraisal and program eligibility. Some loans limit the land value relative to the home.
- Energy-market towns. In communities tied to oil, gas, coal, or trona, lenders look closely at job history and income stability. Overtime and bonus income generally need a track record.
- Insurance and weather. Hail, wind, and wildfire exposure can affect homeowners insurance. Get a quote before you finalize your budget.
- Debt-to-income. Lenders compare your monthly debts and new housing payment with gross income (CFPB on DTI).
How the process works
- Preapproval. We verify credit, income, and assets. Lenders use the words prequalification and preapproval differently, so what matters is what was verified (CFPB comparison). Start on Wyoming preapproval.
- Loan Estimate. After you apply on a property, the lender sends a Loan Estimate within three business days (CFPB). Mortgage credit checks within 45 days count as one inquiry, so comparing lenders is safe (CFPB).
- Underwriting, appraisal, title. We clear conditions and keep everyone updated.
- Closing. Your Closing Disclosure arrives at least three business days before signing (CFPB).
Wyoming cities and counties we serve
Local pages cover Cheyenne, Casper, Laramie, Gillette, Rock Springs, Evanston, and Cody. County pages include Laramie County, Natrona County, Albany County, Campbell County, Sweetwater County, Sheridan County, Park County, Fremont County, Lincoln County, Uinta County, and Teton County. Southwest Wyoming towns like Evanston and the Lincoln and Uinta county communities are a short drive from our Northern Utah base.
Related pages
Start with Wyoming purchase loans, Wyoming refinancing, first-time buyer help, or preapproval. For the full list of loan types see mortgage loans. We also serve neighboring Utah and Idaho, plus Texas.
Sources
- Redfin, Wyoming housing market
- Freddie Mac PMMS, Oct 1, 2026 release
- FRED, 30-Year Fixed Rate Mortgage Average
- Wyoming Department of Revenue
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- HUD, Let FHA loans help you
- VA purchase loan
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- VA funding fee and closing costs
- VA Interest Rate Reduction Refinance Loan
- FHFA, 2026 conforming loan limits
- FHFA 2026 county loan limit list
- HUD No. 25-145, 2026 FHA loan limits
- HUD FHA mortgage limits lookup
- Wyoming Community Development Authority, homebuyers
- WCDA purchase price and income limits
- WCDA 2025 annual report (PDF)
- CFPB, debt-to-income ratio
- CFPB, prequalification vs. preapproval
- CFPB, What is a Loan Estimate?
- CFPB, when a lender checks your credit
- CFPB, What is a Closing Disclosure?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.
Frequently Asked Questions
Everything you need to know about home mortgage loans in WyomingYour ideal loan depends on several factors like your financial situation, long term goals, and risk tolerance. Fixed rate mortgages offer stability, while adjustable rate loans may save you money initially. Government-backed options can be great for those with lower credit scores. At Summit Lending, we’ll guide you through the options to find a perfect fit.
Related Articles
Wyoming Low Down Payment Loans at 7.49%: FHA, VA, USDA, and WCDA Compared (Oct 2026)
MBA's 30-year rate hit 7.49% this week, and FHA purchase applications fell the most. Here is how FHA, VA, USDA, conventional 3% down, and WCDA's Home$tretch help compare on a $386,000 Cheyenne home, including cash to close and the full monthly payment.