Idaho Mortgage Refinance
Refinancing an Idaho mortgage, with the numbers in front of you
Idaho homeowners have built a lot of equity over the past several years. Redfin's statewide median sale price was about $512,859 in August 2026, up 7.9% from a year earlier (Redfin Idaho data). That equity opens doors: dropping mortgage insurance, funding a remodel, consolidating higher-rate debt, or changing the loan term. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed in Idaho and based in Garland, Utah. We compare refinance offers from multiple lenders and show you the break-even before you spend money on an appraisal.
This page covers the main refinance types, where rates are this fall, the break-even test, and Idaho details that affect a refinance. To run your own numbers first, use the Idaho loan calculator.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
Refinance rates in fall 2026
Freddie Mac's weekly survey put the average 30-year fixed rate at 7.28% for the week of October 1, 2026, up from 7.03% a week earlier and 6.34% a year ago. The 15-year fixed averaged 6.60% (Freddie Mac PMMS; history on FRED). These are national averages for strong-credit borrowers. Your quote depends on your credit, equity, loan size, property type, and the day you lock.
In plain terms: with rates above 7%, a refinance just for a lower rate works mainly for owners whose current rate is well above the market, or whose adjustable rate is about to reset higher. Many Idaho homeowners refinancing this year are doing it for equity, term, or mortgage insurance reasons instead. Those can still make sense even when rates are higher than last year.
Refinance options for Idaho homeowners
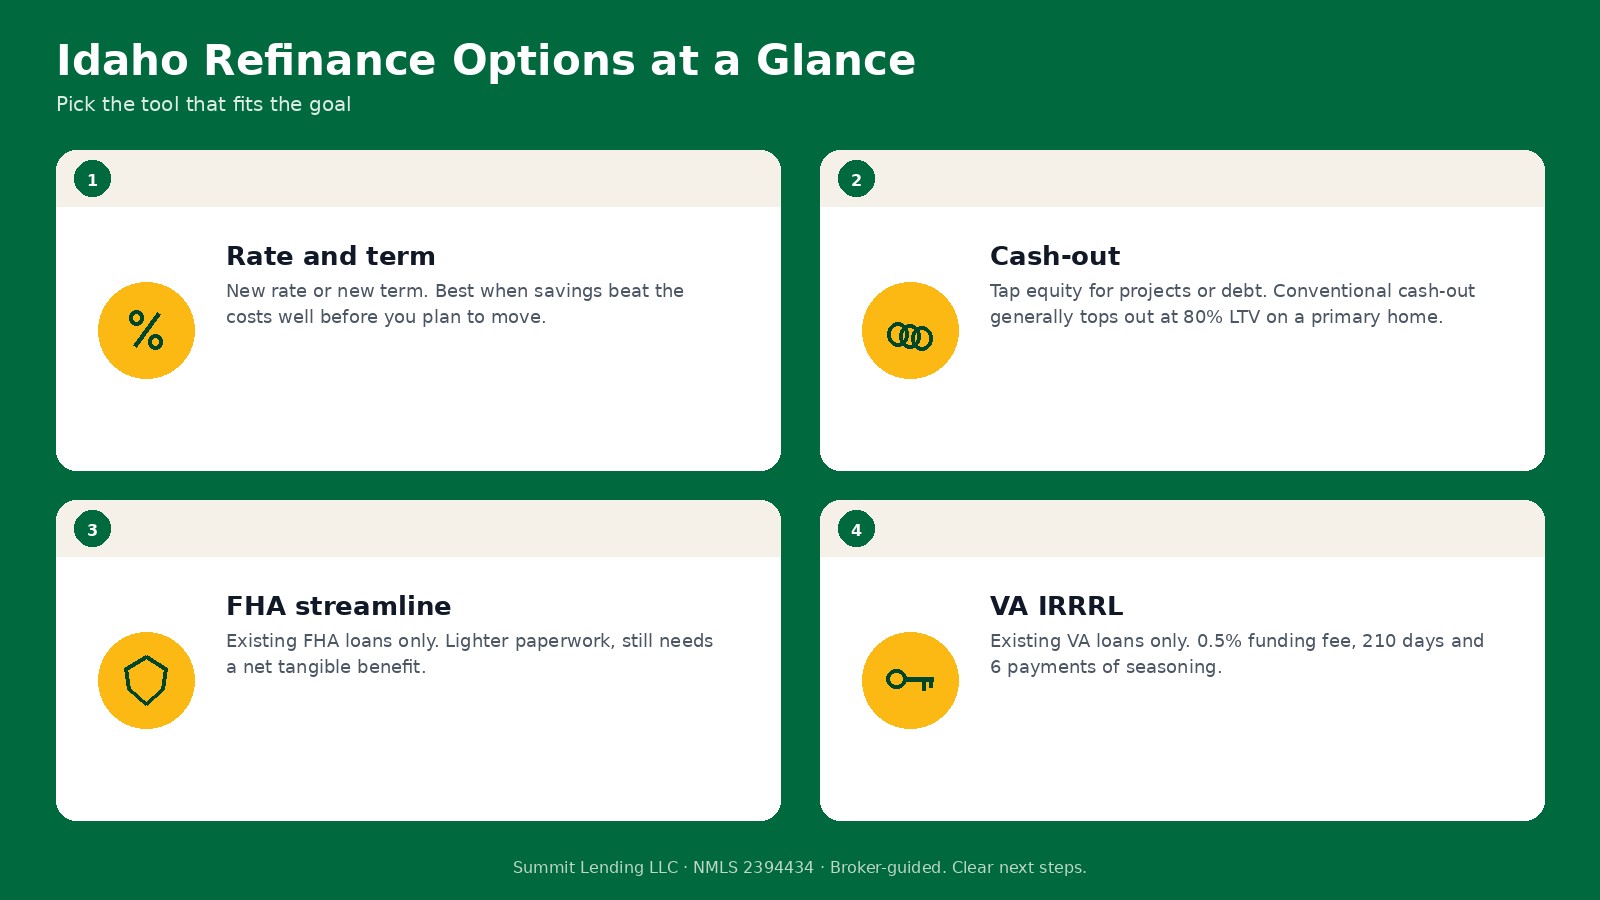
Rate and term
Replace your loan with a new rate, a new term, or both, without meaningful cash out. Moving from 30 years to 15 usually raises the payment but can cut total interest sharply.
Cash-out
A cash-out refinance replaces your mortgage with a larger one and pays you the difference in cash. The CFPB reminds borrowers that this converts equity into debt secured by the home (CFPB on cash-out refinancing). On conventional loans, Fannie Mae generally limits cash-out on a one-unit primary residence to 80% of the home's value (Fannie Mae Eligibility Matrix). If your current first mortgage has a low rate, we will also price a second mortgage or home equity line, which keeps that rate in place.
FHA streamline
Existing FHA borrowers may qualify for a streamline refinance with reduced documentation. HUD requires a net tangible benefit, such as a lower combined rate and insurance payment (HUD Handbook 4000.1).
VA IRRRL and VA cash-out
Veterans with a VA loan can use an Interest Rate Reduction Refinance Loan. The funding fee is 0.5% unless you are exempt (VA funding fee). VA requires seasoning of at least six payments and 210 days, and closing costs must be recouped within 36 months (VA IRRRL). If you want cash, compare the VA cash-out refinance.
Dropping mortgage insurance
Conventional PMI can be cancelled at 80% of the original value and generally ends at 78% (CFPB on PMI). FHA mortgage insurance often lasts much longer, so refinancing from FHA to conventional after prices rise can remove it. We check whether the monthly savings beat the costs.
The break-even test
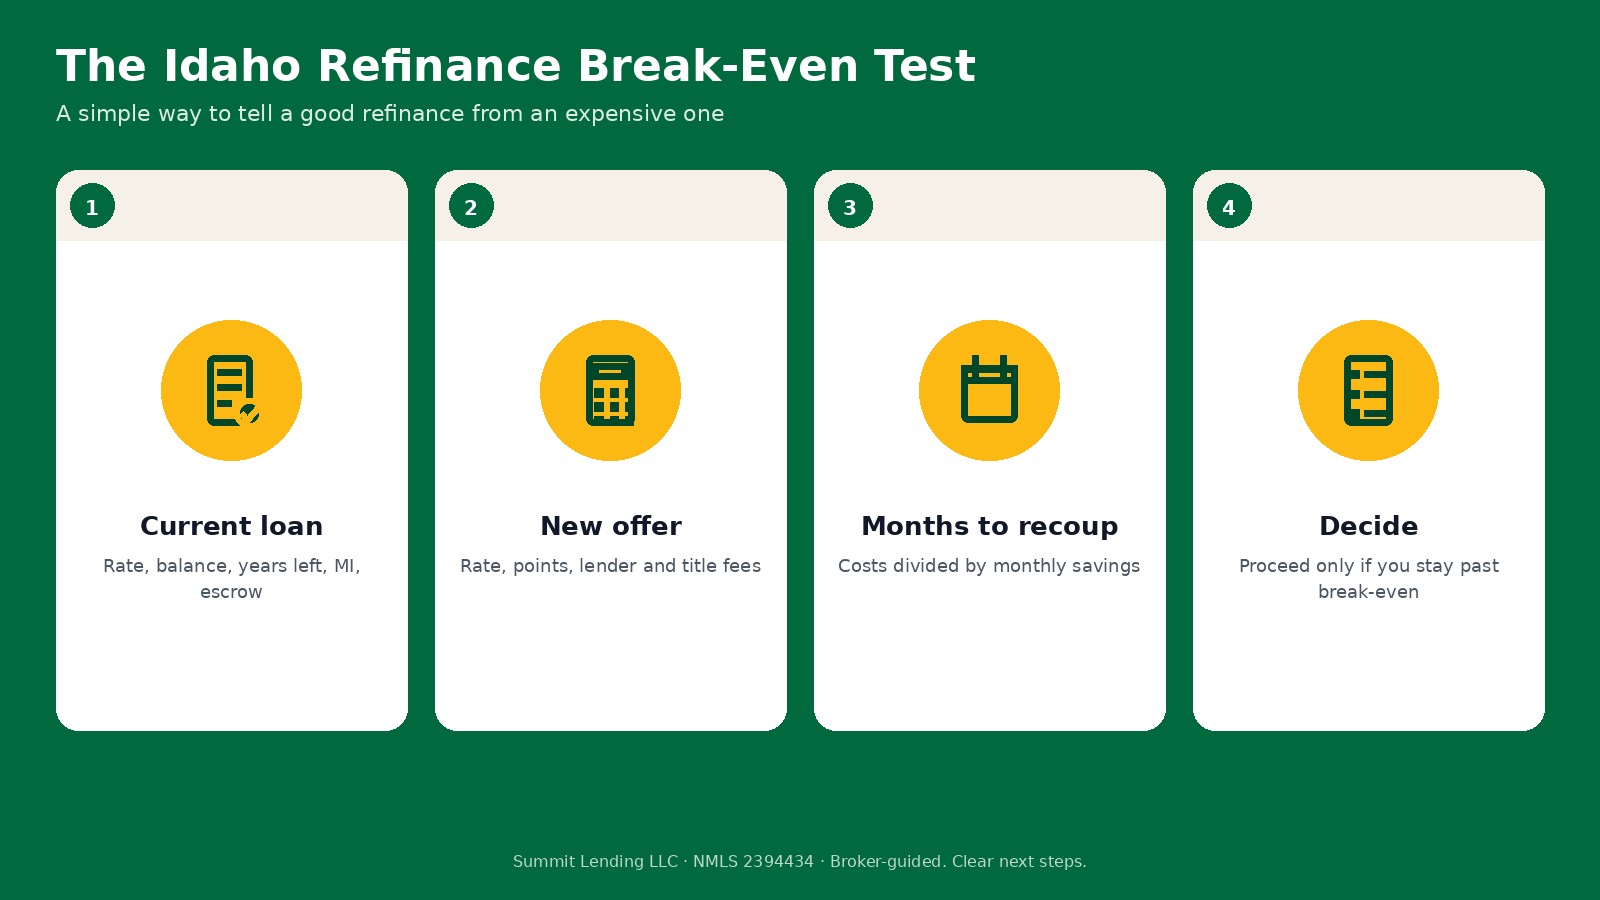
Your Loan Estimate, which lenders must send within three business days of your application (CFPB on Loan Estimates), lists every cost. Here is how we use it:
- Total the real costs of the new loan: lender fees, points, appraisal, title, and recording. Leave out escrow money that is simply moving from your old account.
- Calculate your monthly savings in principal, interest, and mortgage insurance.
- Divide costs by savings to get the break-even in months.
- Decide whether you will keep the home and loan longer than that.
For example, $5,000 in costs and $125 in monthly savings means a 40-month break-even. That works if you plan to stay five years or more. It does not work if you are likely to move in two. We also compare total interest over the remaining term, since a lower payment over a longer term can cost more in the end.
Idaho details that affect a refinance
- Equity varies by region. In Ada County, Boise Regional REALTORS reported an August 2026 single-family median of $595,000 (Boise Regional REALTORS). Owners who bought before the run-up generally have more room than those who bought at the 2022 peak with a small down payment.
- Loan limits. The 2026 conforming limit is $832,750 in 43 of 44 counties, and $1,249,125 in Teton County (FHFA, county file). Above those numbers, the refinance is jumbo.
- Homeowner's exemption. Your primary-residence exemption stays with the home through a refinance, but confirm it is on file with your county. It removes 50% of the home and up to one acre from taxable value, capped at $125,000 (Idaho State Tax Commission). That affects your new escrow payment.
- IHFA second loans. If you used Idaho Housing down payment assistance, that second loan typically has to be paid off or subordinated when you refinance. Tell us early so we can plan for it (IHFA assistance).
What to have ready
- Current mortgage statement and homeowners insurance declarations page
- Recent pay stubs, W-2s, or two years of tax returns if self-employed
- Two months of bank and retirement statements
- Your goal in one sentence
Shopping more than one lender is smart, and the CFPB notes that multiple mortgage credit checks within 45 days count as a single inquiry (CFPB). Before closing you will get a Closing Disclosure at least three business days ahead (CFPB on Closing Disclosures).
Refinancing across Idaho
We work with homeowners in Boise, Nampa, Caldwell, Star, Kuna, Ada County, and Canyon County; in Idaho Falls, Rexburg, Pocatello, Twin Falls, Bonneville County, and Bannock County; in North Idaho, Coeur d'Alene, Post Falls, Sandpoint, and Kootenai County; and in resort areas such as Ketchum, Hailey, Blaine County, and Teton County.
Related pages
Buying your next home? See Idaho purchase loans and Idaho preapproval. Homeowners 62 and older can compare a refinance with an Idaho reverse mortgage. Building on land you own? See Idaho construction loans. The state overview is at Idaho mortgage loans, and the national refinance page links to Utah, Texas, and Wyoming.
Sources
- Redfin, Idaho housing market
- Boise Regional REALTORS, Ada County August 2026 (PDF)
- Freddie Mac PMMS, Oct 1, 2026 release
- FRED, 30-Year Fixed Rate Mortgage Average
- CFPB, cash-out refinance
- Fannie Mae Eligibility Matrix
- HUD Single Family Housing Policy Handbook 4000.1
- VA funding fee and closing costs
- VA Interest Rate Reduction Refinance Loan
- VA cash-out refinance loan
- CFPB, private mortgage insurance
- CFPB, What is a Loan Estimate?
- FHFA, 2026 conforming loan limits
- FHFA 2026 county loan limit list
- Idaho State Tax Commission, homeowner's exemption
- Idaho Housing and Finance Association, down payment help
- CFPB, when a lender checks your credit
- CFPB, What is a Closing Disclosure?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.