Idaho Reverse Mortgages
Reverse mortgages in Idaho: what a HECM does and what it costs
A reverse mortgage lets an Idaho homeowner who is 62 or older turn part of their home equity into cash without a monthly mortgage payment. For retirees in Boise, Coeur d'Alene, Idaho Falls, and smaller towns who bought years ago, that equity can be substantial. A reverse mortgage is still a loan, though. Interest and insurance are added to the balance every month, and you keep paying property tax, insurance, and upkeep for as long as you live in the home. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed in Idaho, based in Garland, Utah, close to the Idaho line. We explain the federal rules and the Idaho tax programs that interact with them, and we encourage families to be part of the conversation.
Most reverse mortgages are Home Equity Conversion Mortgages, or HECMs, insured by the Federal Housing Administration. This page focuses on HECMs and uses the 2026 federal limits.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
The basics
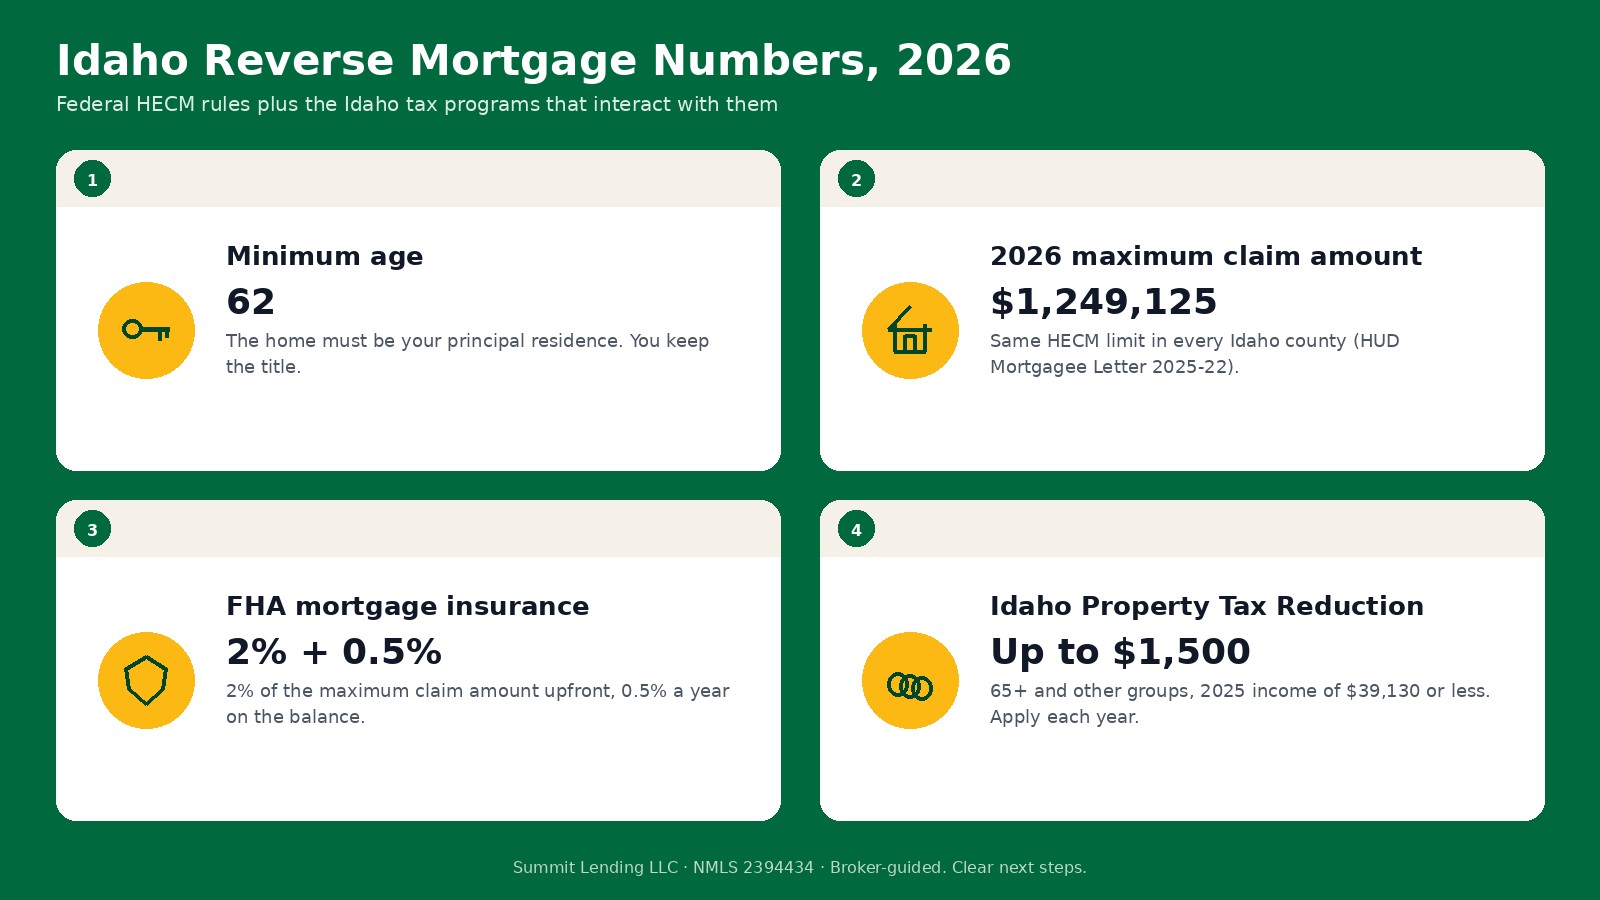
- Age and occupancy. At least one borrower must be 62 or older, and the home must be your principal residence (CFPB on reverse mortgages).
- No monthly mortgage payment. Interest and mortgage insurance are added to the balance instead, so what you owe grows over time.
- You keep the title. You still own the home and remain responsible for property tax, homeowners insurance, HOA dues, and maintenance. Falling behind on those can put the loan in default (CFPB).
- When it is repaid. The loan usually comes due when the last borrower sells, moves out permanently, or passes away. The home can be sold to repay it, or heirs can pay it off and keep the home.
2026 HECM limits and insurance
For 2026, the HECM maximum claim amount is $1,249,125 in every county, up from $1,209,750 in 2025 (HUD Mortgagee Letter 2025-22). The maximum claim amount is the lower of your appraised value or that limit. FHA charges an upfront mortgage insurance premium of 2% of the maximum claim amount and an annual premium of 0.5% of the outstanding balance (HUD Mortgagee Letter 2017-12).
Some Idaho examples. On a Boise area home appraised at $595,000, close to the August 2026 single-family median in Ada County (Boise Regional REALTORS), the upfront premium would be about $11,900. On a home in Blaine County appraised above the limit, the premium is capped at 2% of $1,249,125, about $24,982. Most borrowers finance the premium and other closing costs into the loan, which reduces the cash available but avoids paying them out of pocket.
How much you can receive depends on the age of the youngest borrower (or eligible non-borrowing spouse), the expected interest rate, and the maximum claim amount. Older borrowers and lower rates generally mean more available proceeds. With rates higher than last year, with the 30-year fixed survey average at 7.28% on October 1, 2026 (Freddie Mac PMMS), proceeds are generally lower than they would have been a year ago for the same home and age.
How you can take the money
Federal HECM rules set out the payment options (24 CFR 206, Subpart B):
- Term. Equal monthly payments for a fixed number of months.
- Tenure. Equal monthly payments for as long as the loan stays in good standing and you live in the home.
- Line of credit. You draw money when you want it, up to your available limit.
- Modified term or modified tenure. Monthly payments combined with a line of credit.
- Single lump sum. One payment at closing. This is the only option for a fixed-rate HECM.
Any existing mortgage must be paid off from the proceeds first. If required repairs are found, the lender sets aside 150% of the estimated cost. If the financial assessment shows a risk that taxes or insurance could go unpaid, the lender can set aside part of your funds, called a Life Expectancy Set Aside, to pay them for you (24 CFR 206.19).
Idaho property tax programs and how a reverse mortgage affects them
Idaho has three property tax programs that older homeowners should understand before choosing a reverse mortgage, because one of them is not available if you have one.
- Homeowner's exemption. A primary home is exempt from tax on the lesser of $125,000 or 50% of its value, including up to one acre (Idaho State Tax Commission). A reverse mortgage does not change this, as long as the home remains your primary residence.
- Property Tax Reduction. For 2026, the program can reduce the tax on your home by $250 to $1,500 if your 2025 income, after medical expenses, was $39,130 or less and you are 65 or older or in another qualifying group (such as widowed, blind, or disabled). You apply with your county assessor each year, generally from January 1 through April 15 (Idaho Property Tax Reduction; 2026 program publication).
- Property Tax Deferral. This program lets qualifying homeowners postpone property taxes, with the deferred tax and interest becoming a lien that is repaid when the home is sold or the last claimant dies. For 2026 it required 2025 income of $61,674 or less and an application between January 1 and September 8, 2026. It is not available if the home has a reverse mortgage or a home equity line of credit (Idaho Property Tax Deferral; 2026 program publication).
So if your main goal is to stop paying property tax out of pocket, compare the deferral program with a reverse mortgage before you apply. They do different things, and you cannot use both on the same home. A HUD-approved counselor can walk through this with you.
What families should understand
The CFPB puts it plainly: a reverse mortgage is not free money. The balance rises while equity falls, and the loan is usually repaid by selling the home once the last borrower no longer lives there (CFPB). Any equity left after repayment belongs to you or your heirs. The CFPB also warns about scams, including contractors who push a reverse mortgage to pay for repairs they are selling. A legitimate HECM always starts with independent counseling.
How an Idaho reverse mortgage moves
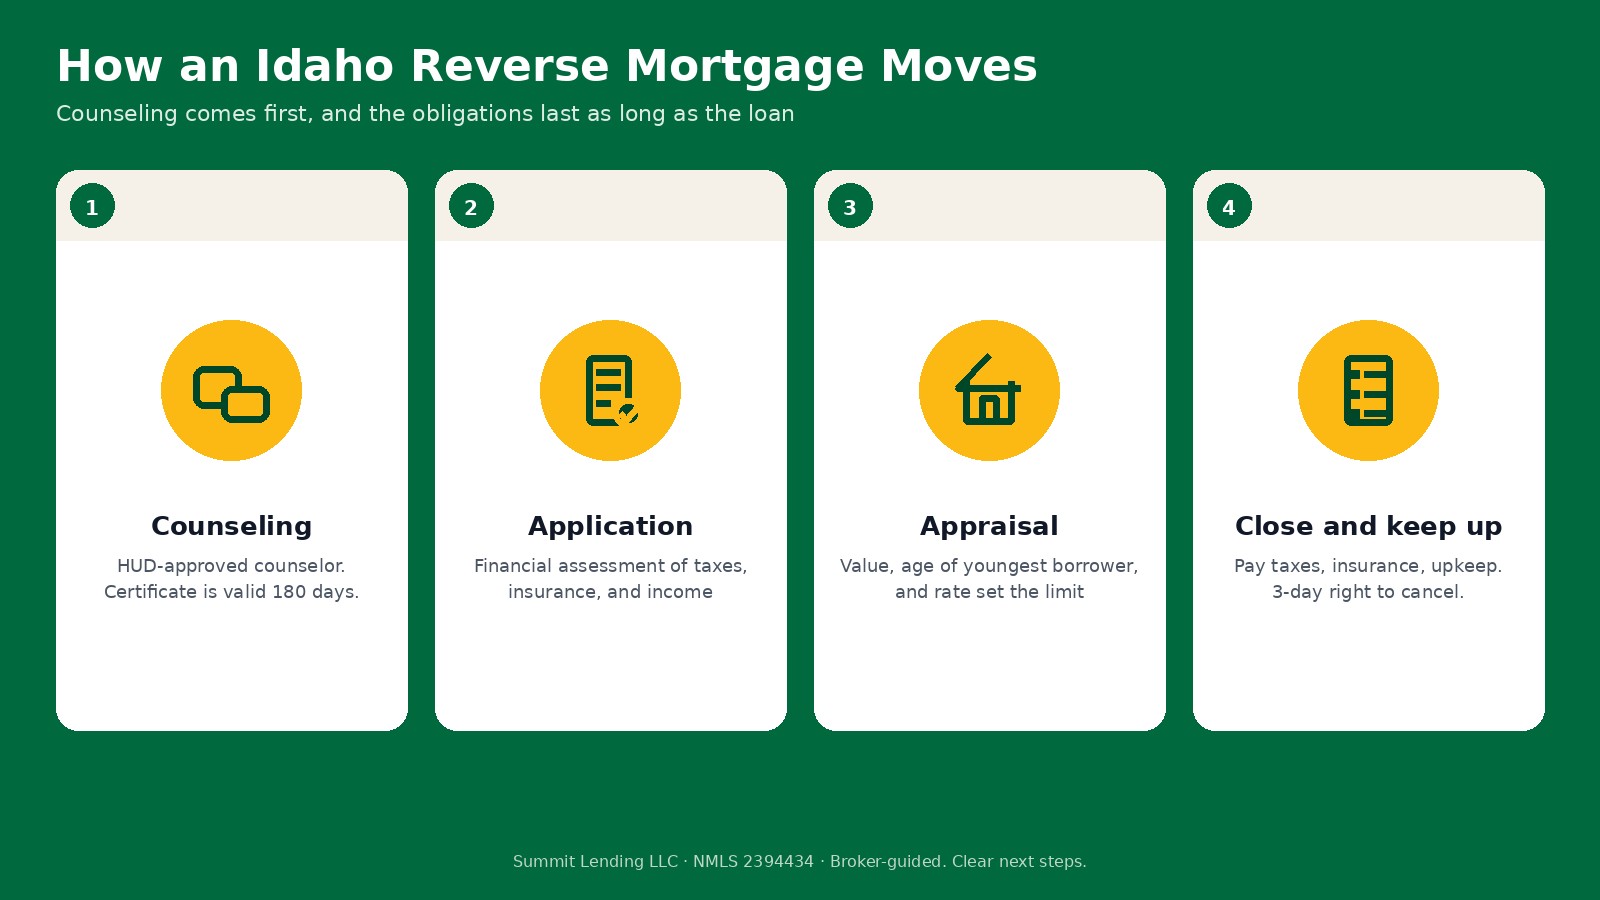
- Counseling. You meet with a HUD-approved HECM counselor who is independent of the lender. The certificate is generally valid for 180 days (HUD HECM overview; find counselors through HUD housing counseling).
- Application and financial assessment. The lender reviews credit, income, and your ability to keep paying taxes and insurance.
- Appraisal. An FHA appraisal sets the value. With the youngest borrower's age and the rate, it determines how much is available.
- Closing and the right to cancel. For most reverse mortgages you have three business days after closing to cancel (CFPB). After that, you keep up with taxes, insurance, and maintenance for the life of the loan.
Other Idaho details
- Wildfire and insurance. Homeowners insurance must stay in force. In parts of the state where wildfire risk has raised premiums, budget for that, since a lapse can create a default. Flood insurance is required if the home is in a high-risk flood zone.
- Manufactured homes. Some can qualify for a HECM if they meet FHA standards, including a permanent foundation and being taxed as real property. Ask before you start counseling.
- Rural property. Homes on larger acreage can be eligible, but the appraisal focuses on the residence and a typical homesite.
- Veterans. The VA does not offer reverse mortgages. Veterans who want one use a HECM or a private product.
Is a reverse mortgage right for you?
It can make sense if you plan to stay in your home for many years, have significant equity, and want to reduce monthly costs or build a cushion. It may not fit if you expect to move soon, want to leave the full value of the home to heirs, or would struggle to keep paying taxes and insurance. Alternatives include downsizing, a traditional Idaho refinance, Idaho's tax deferral program, or a home equity loan. Talk to us and to a counselor before deciding (CFPB guide).
Where we help Idaho homeowners
Treasure Valley: Boise, Nampa, Caldwell, Ada County, and Canyon County. Eastern and Southern Idaho: Idaho Falls, Pocatello, Twin Falls, Bonneville County, Bannock County, and Twin Falls County. North Idaho: Coeur d'Alene, Post Falls, Sandpoint, and Kootenai County. Mountain areas: McCall, and Blaine County.
Related pages
See Utah reverse mortgages, Wyoming reverse mortgages, Texas reverse mortgages, or the national reverse mortgage page. For Idaho, the Idaho mortgage overview, Idaho mortgage calculator, and Idaho purchase loans cover the rest.
Sources
- CFPB, What is a reverse mortgage?
- HUD Mortgagee Letter 2025-22, 2026 HECM limits (PDF)
- HUD Mortgagee Letter 2017-12, HECM premiums (PDF)
- HUD HECM origination and servicing overview (PDF)
- 24 CFR Part 206, Subpart B, HECM eligibility and payment options (PDF)
- HUD housing counseling
- Freddie Mac Primary Mortgage Market Survey
- Boise Regional REALTORS, Ada County August 2026 (PDF)
- Idaho State Tax Commission, homeowner's exemption
- Idaho State Tax Commission, Property Tax Reduction
- Idaho Property Tax Reduction Program 2026 (PDF)
- Idaho State Tax Commission, Property Tax Deferral
- Idaho Property Tax Deferral Program 2026 (PDF)
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.