Idaho Home Purchase Loans
Idaho home purchase loans, compared across lenders
Idaho has been one of the fastest growing states in the country for years, and its housing market shows it. Prices in the Treasure Valley, Eastern Idaho, and North Idaho have climbed well beyond where they were a decade ago, and this fall buyers are also dealing with mortgage rates back above 7%. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed to serve Idaho from our home base in Garland, Utah, just across the state line. We compare purchase loans from multiple wholesale lenders so you can see real differences in rate, fees, down payment, and mortgage insurance before you make an offer.
Below is a plain-language guide to Idaho purchase loan options, 2026 limits, Idaho Housing and Finance Association help, and how the process works with us. Ready to shop? Start an Idaho preapproval or test a payment in the Idaho loan calculator.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
The Idaho market in numbers
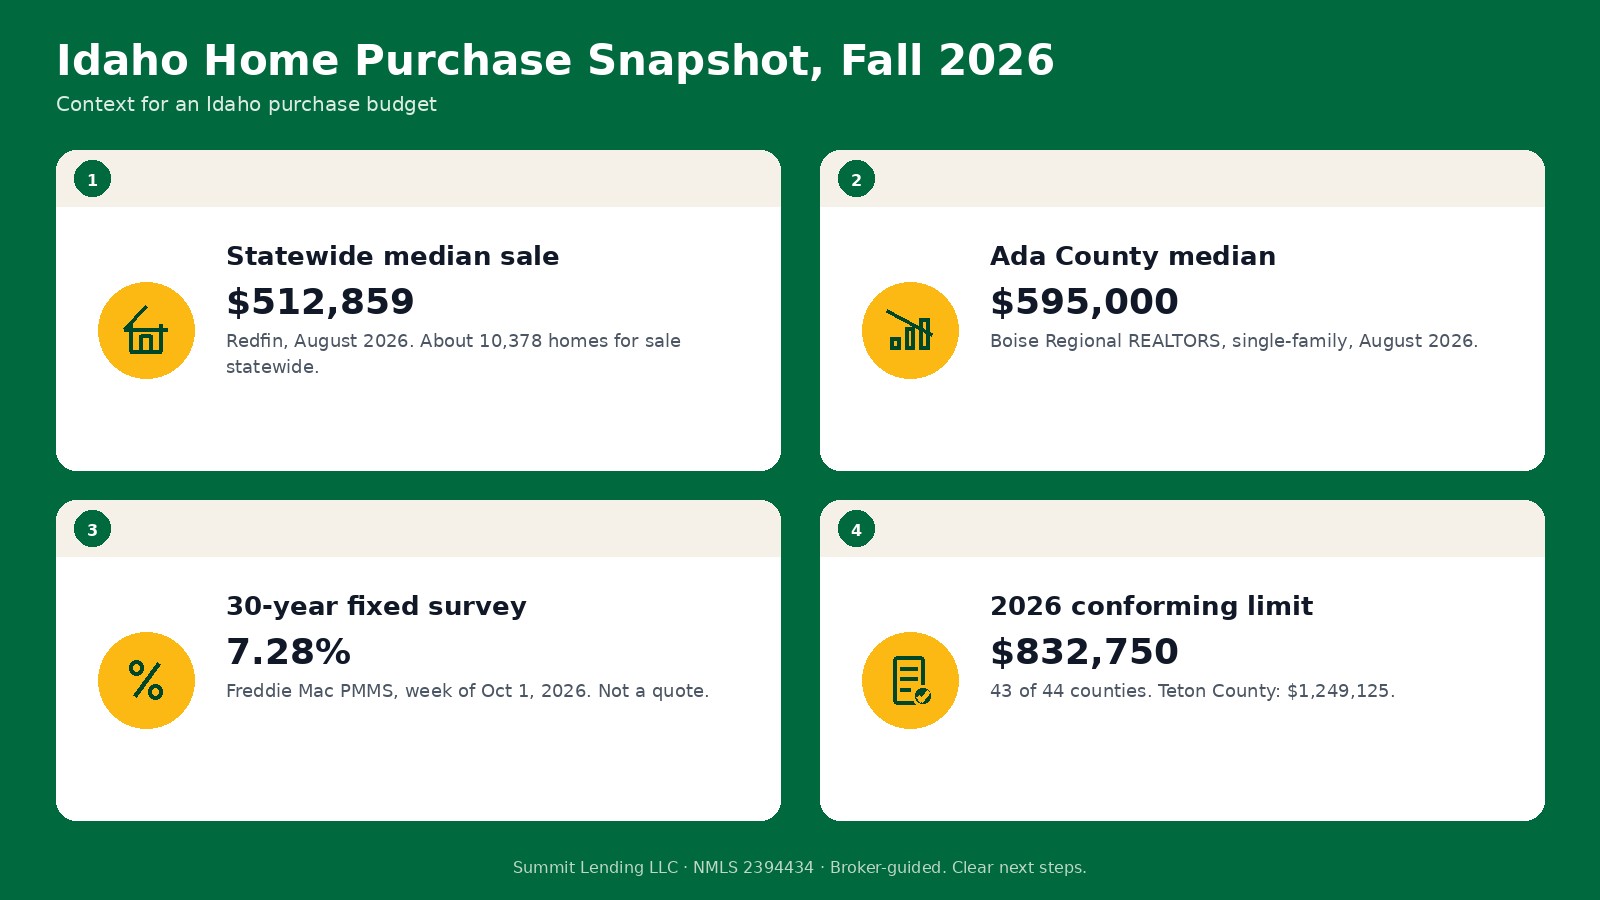
Redfin reported a statewide median sale price of about $512,859 for August 2026, up 7.9% from a year earlier, with roughly 10,378 homes for sale, down 16.1% (Redfin Idaho data). In Ada County, Boise Regional REALTORS put the August single-family median at $595,000 (Boise Regional REALTORS report). Fewer homes for sale and rising prices mean well-priced listings can still move quickly, especially in Boise, Meridian, Eagle, and the faster-growing parts of Canyon County.
Rates moved the wrong way for buyers this fall. Freddie Mac's survey put the average 30-year fixed rate at 7.28% for the week of October 1, 2026, compared with 7.03% a week earlier and 6.34% a year ago (Freddie Mac PMMS; history on FRED). These are national averages for strong-credit borrowers, not a quote.
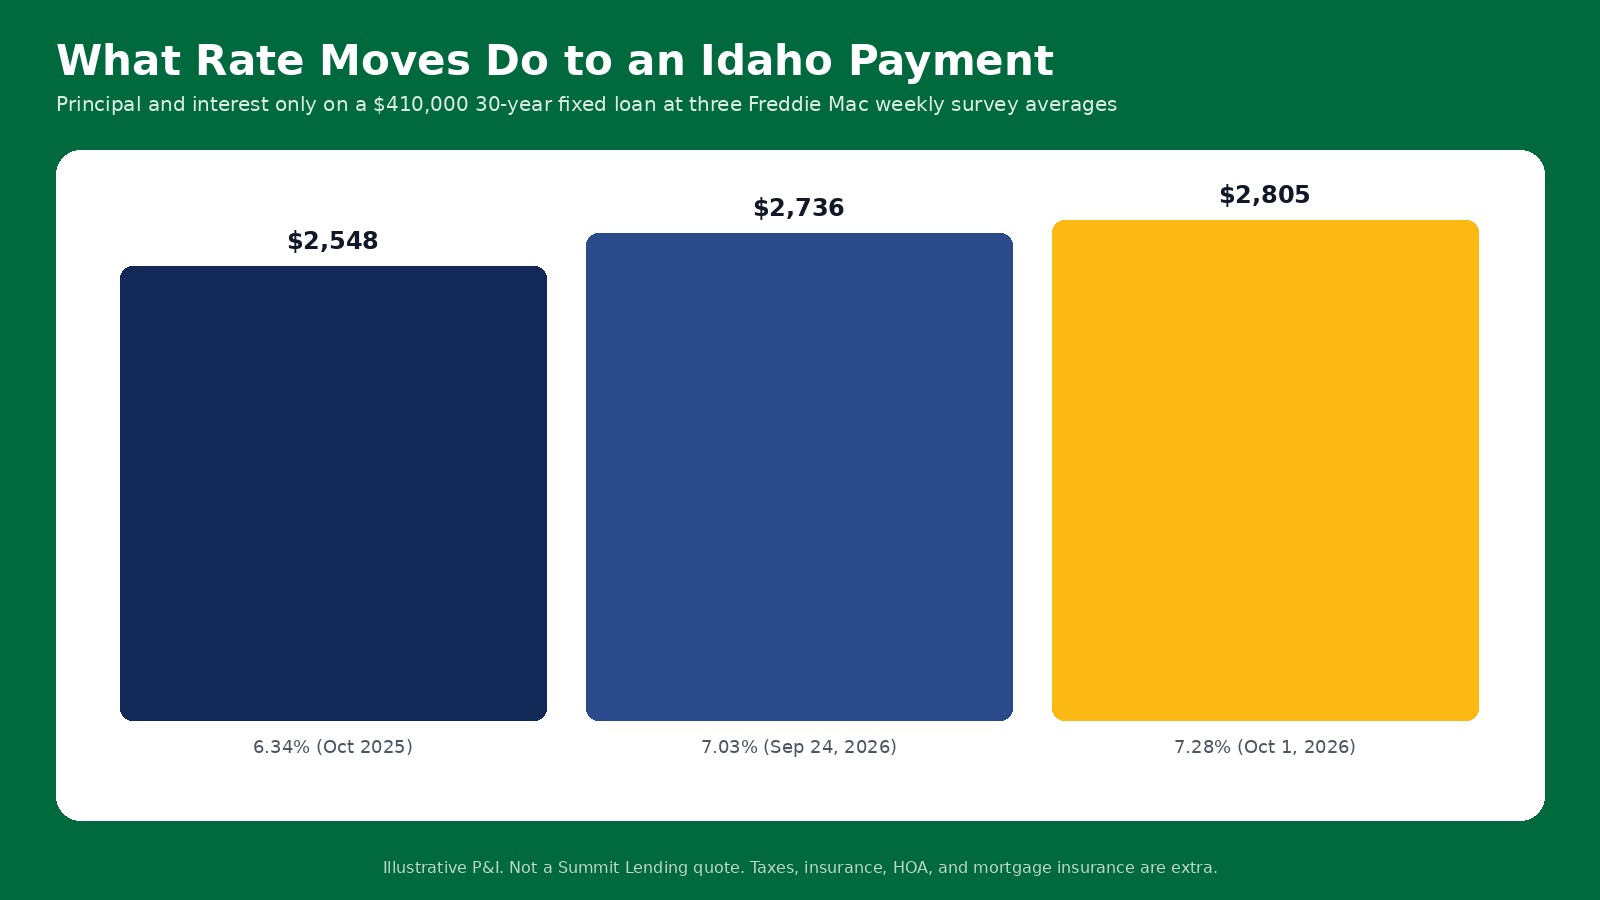
On a $410,000 30-year fixed loan, principal and interest comes to roughly $2,548 a month at 6.34%, about $2,736 at 7.03%, and about $2,805 at 7.28%. That gap of more than $250 a month is before property taxes, homeowners insurance, HOA dues, and mortgage insurance. We always quote the full payment so the budget is realistic.
Purchase loan options for Idaho buyers
Conventional
Conventional loans allow as little as 3% down for qualified buyers on a one-unit primary home; Fannie Mae's eligibility matrix permits up to 97% loan-to-value on eligible fixed-rate purchases (Fannie Mae Eligibility Matrix). Private mortgage insurance applies below 20% down and can be cancelled once you reach 80% of the original value (CFPB on PMI).
FHA
FHA loans allow 3.5% down with a 580 or higher credit score and are more flexible on credit history and debt ratios (HUD FHA overview). They are a common fit for first homes in Nampa, Caldwell, and Pocatello.
VA
Eligible veterans and service members can buy with no down payment and no monthly mortgage insurance, as long as the price does not exceed the appraised value (VA purchase loans). A one-time funding fee applies unless you are exempt (VA funding fee). Mountain Home Air Force Base keeps VA lending busy in southwest Idaho.
USDA
Much of rural Idaho can qualify for USDA guaranteed loans, which allow no down payment for households under the income limits (USDA guaranteed loans). Check a specific address on the USDA eligibility map, since boundaries around growing towns change.
Jumbo
Loans above the conforming limit are jumbo loans with their own pricing and down payment rules. Buyers in Teton County, Blaine County (including Ketchum and Hailey), and parts of Kootenai County and Sandpoint run into jumbo territory most often.
2026 loan limits in Idaho
The 2026 one-unit conforming limit is $832,750 in 43 of Idaho's 44 counties. Teton County, next to Jackson, Wyoming, is the exception at $1,249,125 (FHFA announcement, FHFA county file). Interestingly, Blaine County is at the baseline for conforming loans even though prices there are high, so many Sun Valley area purchases need jumbo financing.
For FHA, HUD's 2026 one-unit floor is $541,287 and the ceiling is $1,249,125 (HUD announcement). Each county's FHA limit is on the HUD lookup tool.
Idaho Housing and Finance Association help
The Idaho Housing and Finance Association (IHFA) is the state housing finance agency, and its loans are offered through participating lenders. IHFA's down payment and closing cost assistance can provide up to 8% of the purchase price, with a minimum borrower contribution of $500 (IHFA assistance, IHFA homebuyers). Its First Loan is aimed at first-time buyers (the first-time requirement does not apply in targeted areas), and its Preferred loan is open to repeat buyers as well. Income and price limits apply. We cover the details on our Idaho first-time home buyer page.
Idaho costs to plan for
- Homeowner's exemption. Once the home is your primary residence, Idaho's homeowner's exemption can remove 50% of the value of the home and up to one acre of land from property taxes, capped at $125,000 (Idaho State Tax Commission). Apply with your county assessor after you move in. Your first escrow estimate may be based on taxes without the exemption.
- Insurance. Wildfire exposure in parts of Idaho can affect homeowners insurance availability and cost. Get a quote early on rural or forested properties.
- Wells and septic. Rural homes often need well and septic inspections, which some loan programs require.
- HOA dues. Newer Treasure Valley subdivisions often have HOAs. Dues count in your debt-to-income ratio (CFPB on DTI).
How an Idaho purchase works with Summit
- Budget and preapproval. We review credit, income, and assets and issue a letter. Lenders use the words prequalification and preapproval differently, the CFPB notes, so what matters is what was verified (CFPB comparison). Multiple mortgage credit checks within 45 days count as one inquiry (CFPB).
- Offer and Loan Estimate. Once you are under contract, your Loan Estimate arrives within three business days of application (CFPB on Loan Estimates).
- Appraisal, title, underwriting. We clear conditions and keep your agent updated.
- Closing. Your Closing Disclosure comes at least three business days before signing (CFPB on Closing Disclosures).
Where we help Idaho buyers
In the Treasure Valley: Boise, Nampa, Caldwell, Star, Kuna, Ada County, and Canyon County. In Eastern and Southern Idaho: Idaho Falls, Rexburg, Pocatello, Twin Falls, Bonneville County, Bannock County, Madison County, and Twin Falls County. In North Idaho: Coeur d'Alene, Post Falls, Sandpoint, and Kootenai County.
Related pages
See Idaho refinance options, Idaho construction loans, Idaho reverse mortgages, and the Idaho mortgage overview. The national purchase loans page covers every state we serve, including Utah, Texas, and Wyoming.
Sources
- Redfin, Idaho housing market
- Boise Regional REALTORS, Ada County August 2026 (PDF)
- Freddie Mac PMMS, Oct 1, 2026 release
- FRED, 30-Year Fixed Rate Mortgage Average
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- HUD, Let FHA loans help you
- VA purchase loan
- VA funding fee and closing costs
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- FHFA, 2026 conforming loan limits
- FHFA 2026 county loan limit list
- HUD No. 25-145, 2026 FHA loan limits
- HUD FHA mortgage limits lookup
- Idaho Housing and Finance Association, down payment help
- Idaho Housing and Finance Association, homebuyers
- Idaho State Tax Commission, homeowner's exemption
- CFPB, debt-to-income ratio
- CFPB, prequalification vs. preapproval
- CFPB, when a lender checks your credit
- CFPB, What is a Loan Estimate?
- CFPB, What is a Closing Disclosure?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.
Related Articles
ARM or Fixed at 7.28%? An Idaho Homebuyer's Guide (October 2026)
Freddie Mac's 30-year fixed hit 7.28% on Oct. 1, 2026, and ARMs climbed to 10.3% of applications. Here is how a 5-year ARM really compares with a fixed loan on a $595,000 Ada County home, including resets, caps, and the qualifying rule most buyers miss.
New Construction vs. Resale in Idaho at 7.40%: How to Compare Builder Incentives (Oct 2026)
Freddie Mac's 30-year average hit 7.40% on Oct. 8, and September MLS data put Ada County's new construction median about $61,600 above resale. Here is how to price a builder's rate buydown or cash credit against a resale home, with Treasure Valley numbers and the Idaho tax rules that change a new-build budget.
Idaho Housing Down Payment Assistance at 7.32%: What the 8% Second Mortgage Really Costs (Oct 2026)
Freddie Mac's average dipped to 7.32% on Oct. 22, and Idaho buyers are asking about down payment help. Idaho Housing's assistance is an 8% second mortgage at your first rate plus 2%, repaid over 15 years. Here is what it really costs on a $440,000 Nampa home and a $575,000 Ada County home, how First Loan and Idaho Heroes change the math, and when to skip it.Frequently Asked Questions
Everything you need to know about home mortgage loans in IdahoYour ideal loan depends on several factors like your financial situation, long term goals, and risk tolerance. Fixed rate mortgages offer stability, while adjustable rate loans may save you money initially. Government-backed options can be great for those with lower credit scores. At Summit Lending, we’ll guide you through the options to find a perfect fit.