Idaho Construction Loans
Idaho construction loans for custom and new homes
Idaho buyers often build because the house they want simply is not for sale. Redfin counted about 10,378 homes for sale statewide in August 2026, down 16.1% from a year earlier, while the median sale price rose 7.9% to about $512,859 (Redfin Idaho data). Tight inventory makes a build on your own lot, or a new home in a growing subdivision, a practical path. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed in Idaho, based just across the state line in Garland, Utah. We compare construction-to-permanent financing from multiple lenders so you can see down payment, reserves, rate options, and builder requirements side by side.
Builders working with our borrowers can coordinate through the Summit Builder Portal.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
One-time close vs. two-time close
One-time close (construction-to-permanent) means one application, one approval, and one closing. You generally pay interest only on funds drawn during the build, and the loan converts to a permanent mortgage at completion. You get certainty early and one set of closing costs.
Two-time close pairs a short-term construction loan with a separate permanent mortgage. You qualify twice and close twice, which adds cost and risk but lets you shop the permanent loan when the house is done.
Construction-to-permanent loans are available in conventional form and, through participating lenders and approved builders, with FHA and VA options. The CFPB's overview of loan types is a helpful neutral reference (CFPB loan options).
Budgeting an Idaho build
A construction loan is underwritten on the appraised value of the finished home, using your plans, specifications, and builder bid. The more complete the bid, the cleaner the appraisal. Allowances for finishes should be realistic, not placeholders.
- Land. If you own the lot, its equity can often count toward the down payment, subject to appraisal, title, and how long you have owned it. If you are buying the land, the price and closing costs go into the budget.
- Site work. Rural Idaho lots can require wells, septic, long driveways, power extensions, and grading. Get bids before you finalize the loan amount.
- Contingency. Lenders want a reserve for overruns. Change orders after closing usually have to be paid out of pocket or approved by the lender.
- Interest during construction. Interest-only payments on drawn funds start small and grow as the house goes up. Plan for that while you may still be paying rent or a current mortgage.
Idaho rules that matter during a build
Contractor registration
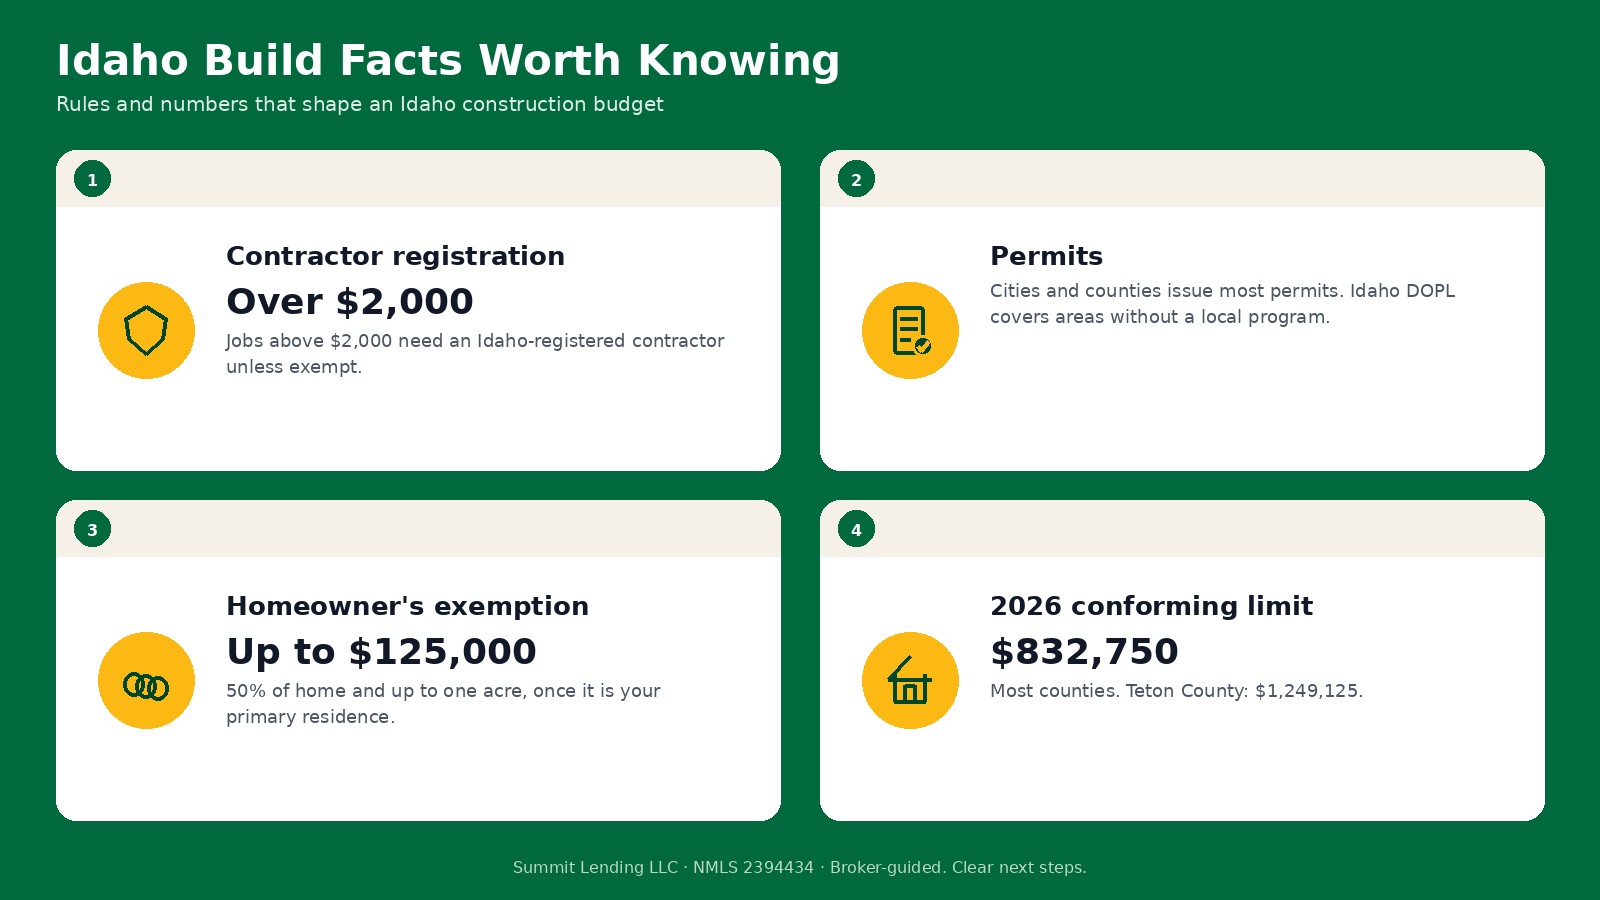
Idaho requires contractors to register with the Idaho Contractors Board, part of the Division of Occupational and Professional Licenses, for construction work over $2,000, with limited exemptions (Idaho Contractors Board; statute in Idaho Code Title 54, Chapter 52). Lenders will ask for your builder's registration number, liability insurance, and often a list of past projects. Plumbing, electrical, and HVAC trades carry their own licenses.
Permits and inspections
Most building permits are issued by cities and counties. The state Building Code program, now part of the Idaho Division of Occupational and Professional Licenses (the former Division of Building Safety), covers areas without local enforcement, and DOPL also licenses the electrical, plumbing, and HVAC trades (Idaho DOPL Building Code program). Your lender's draw inspector is separate from code inspections, so expect both.
Lien waivers
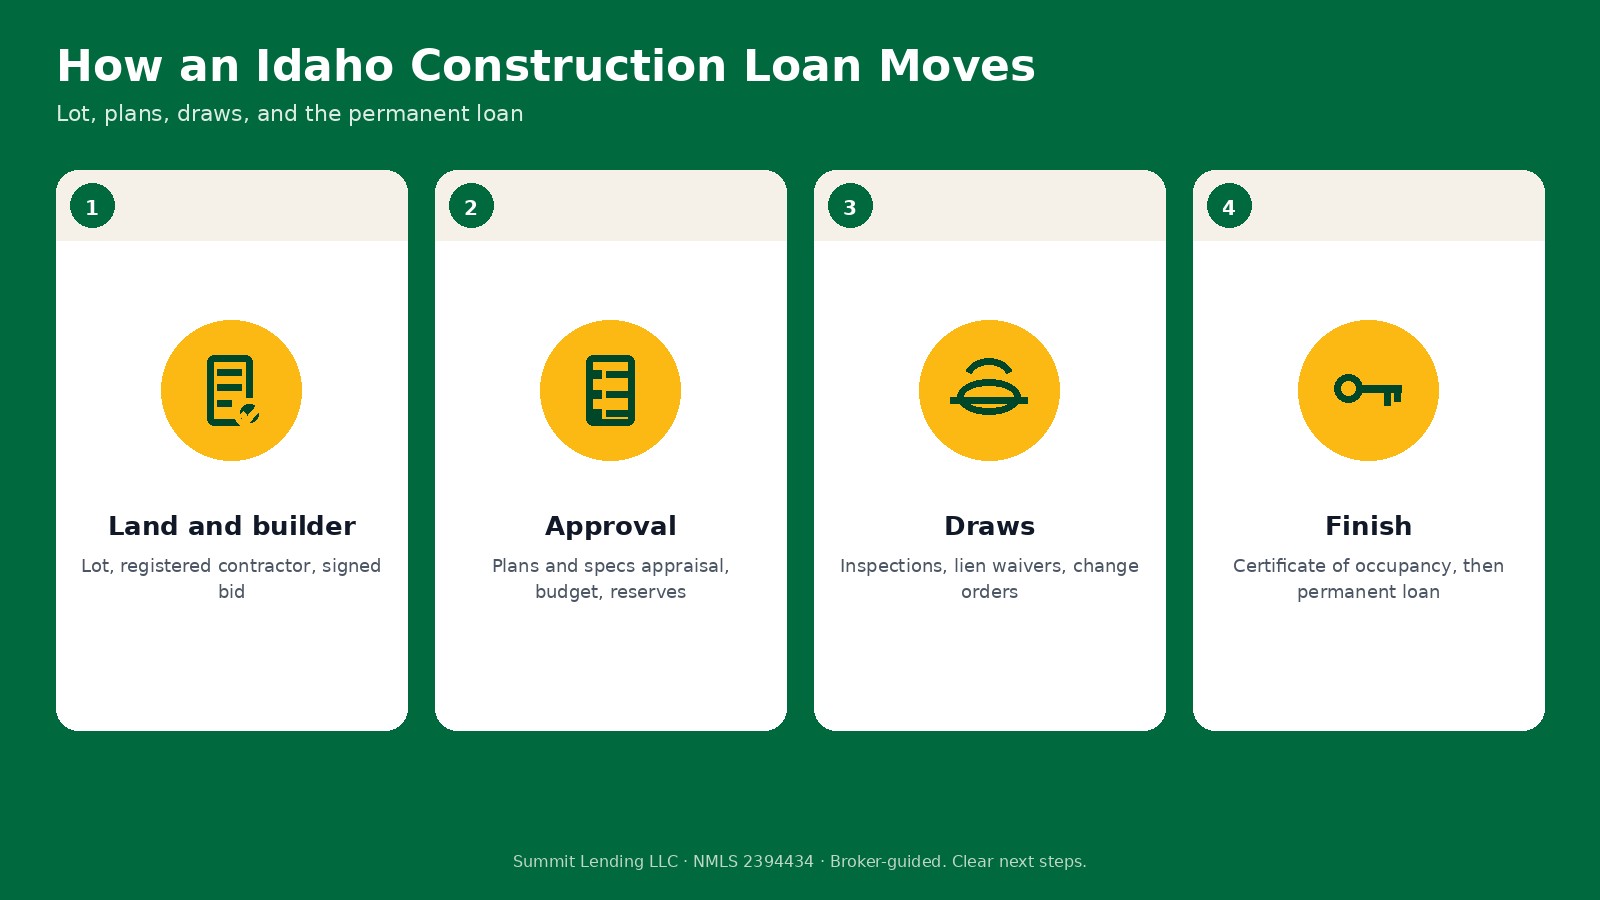
Lenders and title companies want proof that subcontractors and suppliers were paid at each stage. Expect lien waivers to be collected with draws, and ask your builder how they manage them on a larger custom build.
Property taxes after move-in
Once the finished home is your primary residence, apply for Idaho's homeowner's exemption with your county assessor. It removes 50% of the value of the home and up to one acre of land from taxable value, capped at $125,000 (Idaho State Tax Commission). Your first permanent-loan escrow may be estimated before the exemption is applied.
How draws work
Funds are released in stages after the lender's inspector confirms work is complete. A typical sequence is foundation, framing, rough-ins, drywall and finishes, and final completion, with the last draw released after final inspection and a certificate of occupancy where required. Your builder should agree to the draw schedule before closing so nobody is surprised by what the lender will pay and when.
Loan limits and rates for Idaho builds
The 2026 one-unit conforming limit is $832,750 in 43 of Idaho's 44 counties, and $1,249,125 in Teton County (FHFA, FHFA county list). Custom homes in the Wood River Valley, North Idaho lake areas, and Teton Valley can exceed those limits and need jumbo construction financing. HUD's 2026 FHA floor is $541,287 (HUD), with county limits on the HUD lookup tool.
Freddie Mac's survey average for a 30-year fixed was 7.28% for the week of October 1, 2026 (Freddie Mac PMMS). On a one-time close, ask when the permanent rate locks, how long the lock lasts, and what an extension costs if the build runs long.
Where we finance builds in Idaho
We work with borrowers and builders in the Treasure Valley, including Boise, Nampa, Caldwell, Star, Kuna, Ada County, and Canyon County. In Eastern and Southern Idaho we serve Idaho Falls, Rexburg, Pocatello, Twin Falls, and Bonneville County. In North Idaho and resort areas, see Coeur d'Alene, Post Falls, Sandpoint, Kootenai County, Teton County, and Blaine County.
Getting started
- Tell us about your lot, rough budget, and timeline.
- Get an Idaho preapproval before signing a builder contract.
- Share the builder's registration, bid, plans, and specs so we can order the appraisal.
- Review the Loan Estimate, which arrives within three business days of application (CFPB), and the draw schedule.
- Close, break ground, and track draws with us through completion.
Related pages
Prefer an existing home? See Idaho purchase loans. First-time buyers can review Idaho first-time home buyer programs. Planning a major remodel instead? Compare Idaho refinance options. For the national view see construction loans, and for nearby markets see Utah construction loans. The state overview is at Idaho mortgage loans.
Sources
- Redfin, Idaho housing market
- CFPB, loan options
- Idaho Contractors Board registration
- Idaho Code Title 54, Chapter 52 (PDF)
- Idaho DOPL, Building Code program
- Idaho State Tax Commission, homeowner's exemption
- FHFA, 2026 conforming loan limits
- FHFA 2026 county loan limit list
- HUD No. 25-145, 2026 FHA loan limits
- HUD FHA mortgage limits lookup
- Freddie Mac PMMS, Oct 1, 2026 release
- CFPB, What is a Loan Estimate?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.