Utah Construction Loans
Utah construction loans from lot to keys
Building a home in Utah is a financing project before it is a construction project. You need money for the lot (or a plan for the lot you already own), a builder budget that holds up under appraisal, a draw schedule that pays your contractor as work is inspected, and a clean handoff into a permanent mortgage when the house is finished. Summit Lending LLC (NMLS 2394434) is a Utah mortgage broker in Garland, and construction financing is a regular part of our work across the state.
We compare construction-to-permanent programs from multiple lenders so you can see down payment, reserves, rate options, and builder requirements side by side. Builders can also use the Summit Builder Portal to coordinate with us.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
How construction financing works
One-time close (construction-to-permanent)
A one-time close loan uses a single application, approval, and closing. During the build you usually pay interest only on the money that has been drawn. When the home is complete, the loan converts to your permanent mortgage without a second closing. The advantage is certainty: you qualify once and pay one set of closing costs. The tradeoff is less freedom to shop the permanent loan later.
Two-time close
A two-time close pairs a short-term construction loan with a separate permanent mortgage at the end. You qualify twice and close twice. That can make sense if you expect your finances or the rate environment to look different by move-in day, but it adds closing costs and the risk that something changes between the two approvals.
Which loan programs can be used
Construction-to-permanent financing is available in conventional form and, with participating lenders and approved builders, through FHA and VA programs as well. Each has its own down payment, credit, and builder rules. The CFPB's overview of loan options is a useful neutral primer on how the major loan types differ (CFPB loan options). We match the program to your project instead of forcing the project into one program.
Budget, appraisal, and lot equity
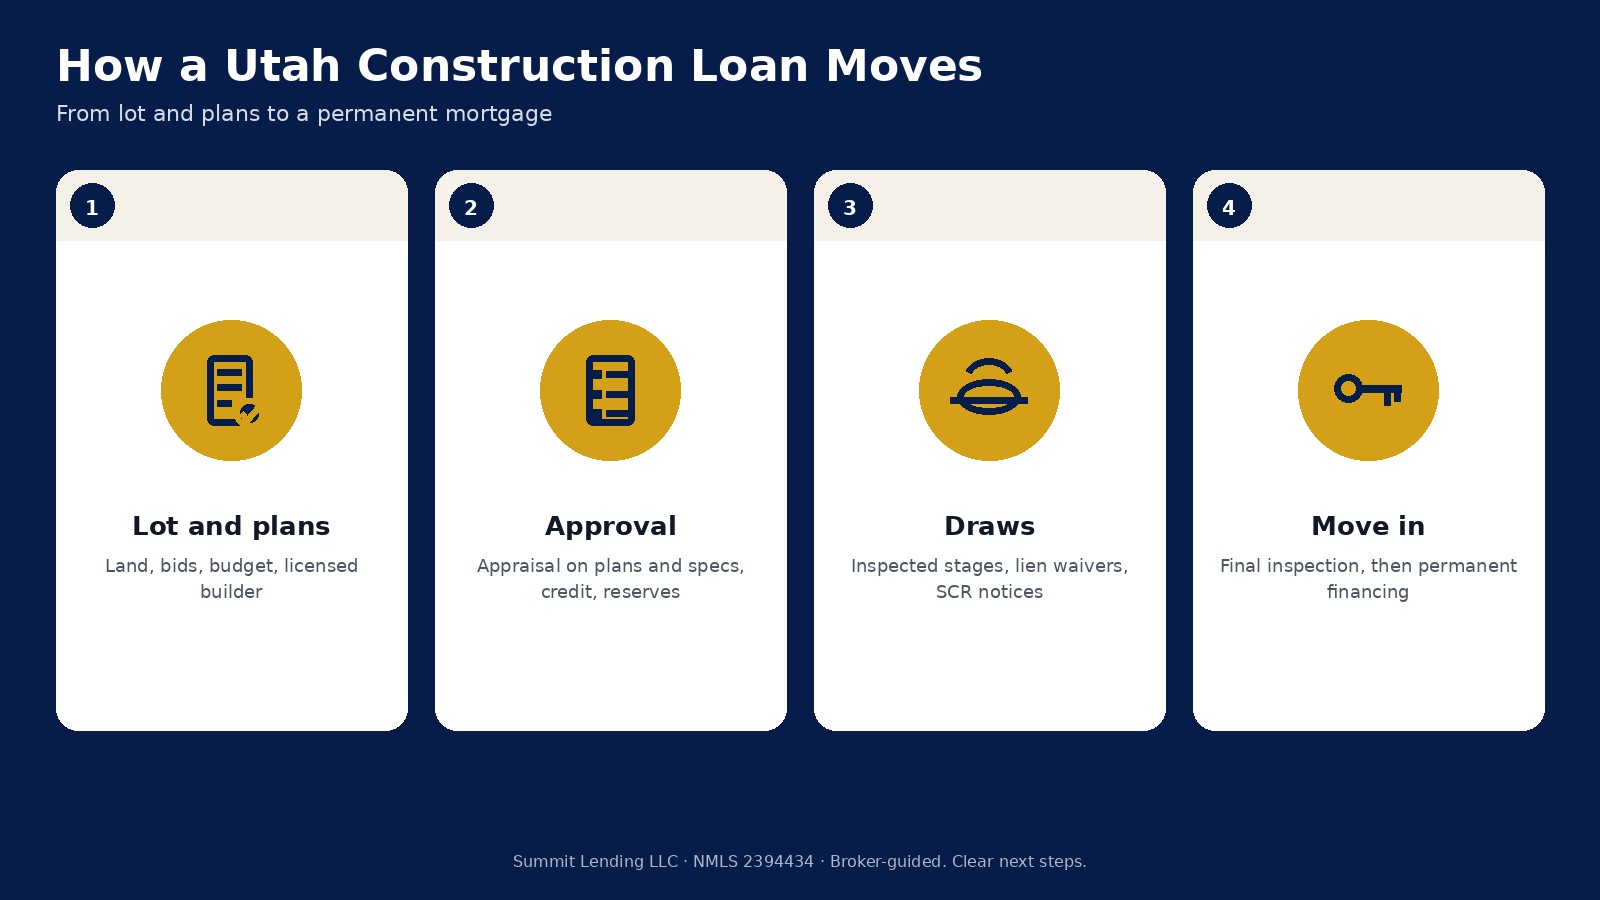
Lenders base a construction loan on an appraisal of the finished home, built from your plans and specifications. That is why a complete builder bid matters: the appraiser needs to know what is actually being built. If the bid includes a large allowance for finishes, expect questions.
If you already own your land, equity in the lot can often count toward your down payment, subject to the appraisal, title, and how long you have owned it. If you are buying the lot as part of the loan, the purchase price, any site work, and utility hookups need to be in the budget. Rural Utah lots can carry real costs for wells, septic systems, and power extensions, so get those bids early.
Plan a contingency as well. Material and labor prices can move mid-build, and change orders you request after closing usually have to be paid out of pocket or approved by the lender. Underwriters notice thin contingencies, and so should you.
Utah rules that matter during a build
The State Construction Registry and lien rights
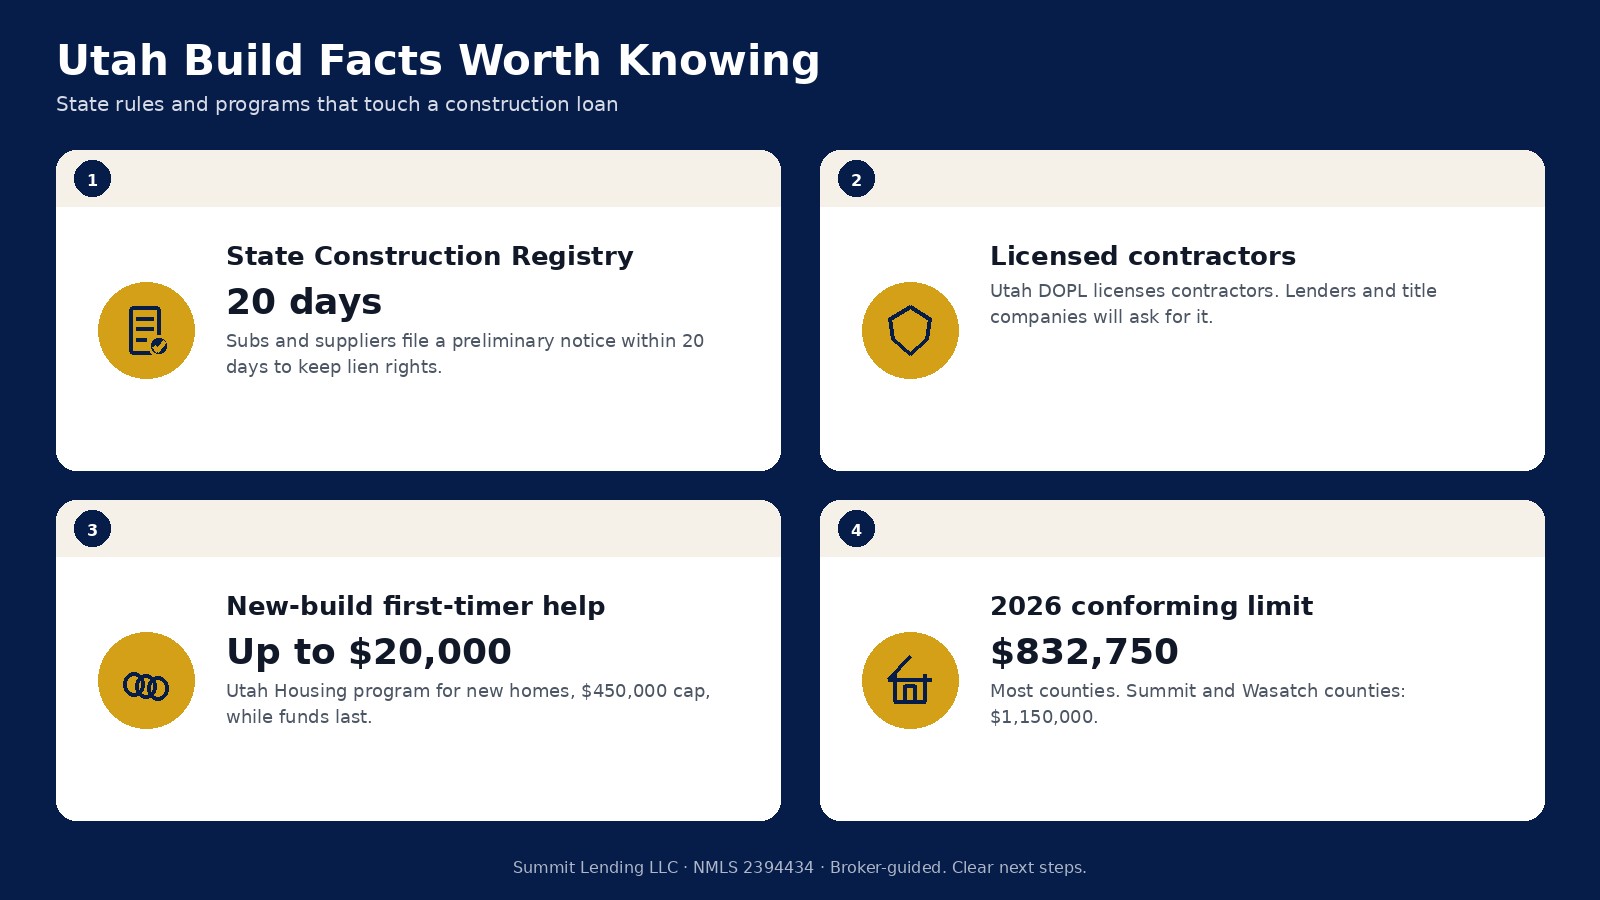
Utah tracks construction lien notices through the State Construction Registry (SCR). Under Utah Code 38-1a-501, subcontractors and suppliers generally must file a preliminary notice with the registry within 20 days after they first provide labor or materials to preserve their lien rights (Utah Code 38-1a-501). Homeowners can look up the notices filed on their property by parcel through the SCR homeowner tools (SCR homeowner information).
This matters to your loan because lenders and title companies want proof that everyone who worked on the house was paid. Expect lien waivers to be collected with each draw. Checking the registry yourself is a good habit, especially on a larger custom build with many subcontractors.
Licensed contractors
Utah contractors are licensed through the Division of Professional Licensing (Utah DOPL). Lenders will ask for your builder's license, insurance, and often references or past projects. Owner-builder construction, where you act as your own general contractor, is harder to finance and is not allowed by many programs. Tell us early if that is your plan.
Help for first-time buyers purchasing new construction
Utah created a first-time homebuyer assistance program for newly constructed homes, administered by Utah Housing Corporation. It offers up to $20,000 toward a newly built home that has not been lived in, with a purchase price of $450,000 or less. The buyer must be a first-time homebuyer, have lived in Utah for at least 12 months, and occupy the home within 60 days (UHC program page, program FAQ, Utah Code 63H-8-501). Funding is limited and available until it runs out, so confirm availability before you build a budget around it. The program fits buyers purchasing a newly built home from a builder; ask us how it applies to your contract.
How draws work
Construction funds are released in stages after the lender's inspector confirms work is complete. A typical schedule follows foundation, framing, rough mechanicals, drywall and finishes, and final completion, though every lender and builder agreement is a little different. You usually pay interest only on the amount drawn so far, which keeps early payments lower. The final draw is released after the final inspection and, in most areas, a certificate of occupancy from the local building department.
Your builder should know the draw schedule before closing. Delays happen when the builder expects money at a stage the lender does not recognize, or when lien waivers are missing. We set the calendar with both of you at the start.
Loan limits for Utah builds
For 2026, the one-unit conforming loan limit is $832,750 in most Utah counties and $1,150,000 in Summit and Wasatch counties (FHFA, FHFA county list). Custom homes in Park City, Heber, or the higher end of Utah County can run above those limits and need jumbo construction financing. HUD's 2026 FHA one-unit floor is $541,287 (HUD); county FHA limits are on HUD lookup tool.
Rates matter during a build too. Freddie Mac's survey average for a 30-year fixed was 7.28% for the week of October 1, 2026 (Freddie Mac PMMS). On a one-time close, ask how and when your permanent rate is locked, and whether a float-down option is available if rates fall before completion.
Where we finance builds in Utah
We work with borrowers and builders statewide, including Salt Lake City, South Jordan, Lehi, American Fork, Provo, Spanish Fork, Ogden, and Layton. County-level pages cover Salt Lake County, Utah County, Davis County, Weber County, Cache County, and Box Elder County.
Rural and resort builds are common too: see Tremonton, Brigham City, Heber City, Park City, Washington County, and Cedar City.
Steps to start a Utah construction loan
- Call or email us with your lot situation, rough budget, and timeline.
- Get a Utah preapproval so you know your price range before signing a builder contract.
- Share the builder's license, bid, plans, and specs so the appraisal can be ordered.
- Review the Loan Estimate and draw schedule. You will get a Loan Estimate within three business days of applying (CFPB).
- Close, break ground, and track draws with us and your builder through completion.
Related pages
Not ready to build? Compare Utah purchase loans for existing homes. First-time buyers should read Utah first-time home buyer programs. Existing owners planning a big remodel can compare Utah refinance options. For the national overview see construction loans, and for other states see Idaho construction loans and Texas construction loans. The full state overview is at Utah mortgage loans.
Sources
- CFPB, loan options
- Utah Code 38-1a-501, preliminary notice
- Utah State Construction Registry, homeowners
- Utah Division of Professional Licensing
- Utah Housing, First-Time Homebuyer Assistance Program (new construction)
- Utah Housing, FTHB assistance FAQ (PDF)
- Utah Code 63H-8-501
- FHFA, 2026 conforming loan limits
- FHFA 2026 county loan limit list
- HUD No. 25-145, 2026 FHA loan limits
- HUD FHA mortgage limits lookup
- Freddie Mac PMMS, Oct 1, 2026 release
- CFPB, What is a Loan Estimate?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.