Idaho First-Time Home Buyers
Get A Mortgage Loan And Unlock Your First Home in Idaho
Buying your first home is life-changing, and it's only natural for you to want to take the big step without any uncertainties. At Summit Lending, we help first-time home buyers navigate the process of finding the best mortgage loan in Idaho.
With us, you won't have to worry about struggling with mortgage payments or refinancing in the future. We help you get it right the first time.
Buying your first home in Idaho
Buying a first home in Idaho this fall takes a bit more planning than it did a few years ago. Prices have kept climbing, homes for sale are scarcer, and mortgage rates are back above 7%. The good news is that Idaho has real help for buyers: a state down payment program that can cover most of your upfront cash, a tax-advantaged savings account for first-time buyers, and a homeowner's exemption that lowers property tax once you move in. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed in Idaho, based just across the line in Garland, Utah. We compare loans from multiple wholesale lenders and help first-time buyers put these pieces together.
If you want to see a payment first, try the Idaho mortgage calculator. When you are ready, start an Idaho preapproval.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
The Idaho market first-time buyers face
Redfin reported Idaho's statewide median sale price at about $512,859 for August 2026, up 7.9% from a year earlier, with roughly 10,378 homes for sale, down 16.1% (Redfin Idaho data). In Ada County, Boise Regional REALTORS put the August single-family median at $595,000 (Boise Regional REALTORS). Freddie Mac's survey put the 30-year fixed average at 7.28% for the week of October 1, 2026, compared with 6.34% a year ago (Freddie Mac PMMS).
Put together, a first home in the Treasure Valley is a big number. On a $510,000 loan, principal and interest at 7.28% is about $3,489 a month before taxes and insurance. That is why first-time buyers in Idaho often look at Nampa, Caldwell, Kuna, Pocatello, or Twin Falls, and why down payment help matters so much.
Idaho Housing down payment assistance
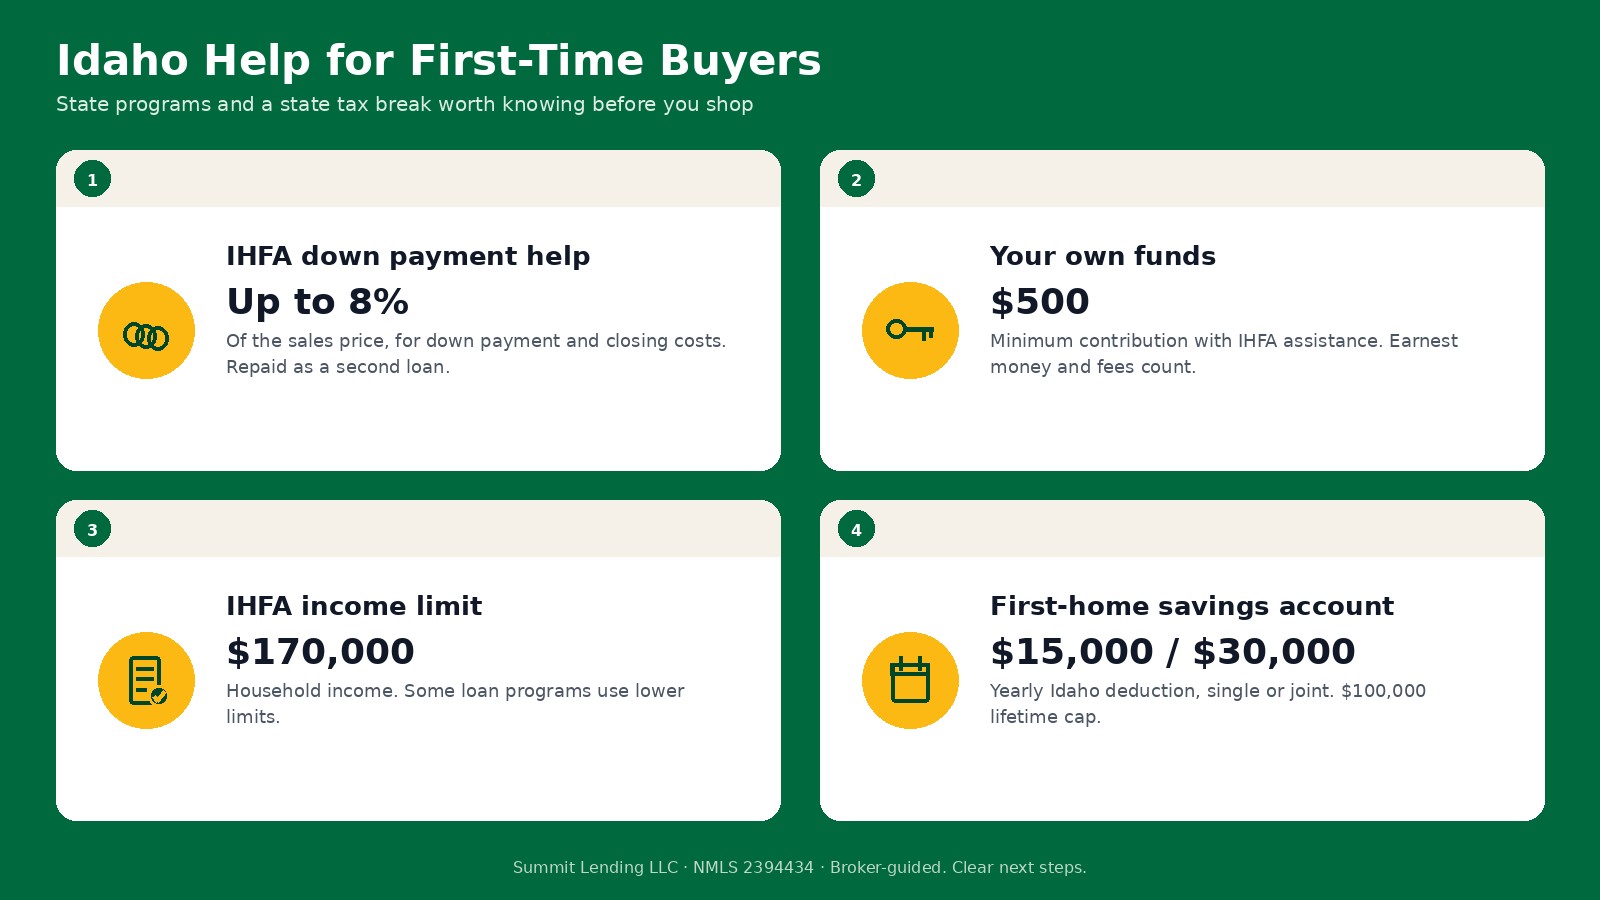
The Idaho Housing and Finance Association (IHFA) is the state housing finance agency. Its down payment assistance provides up to 8% of the sales price toward the down payment, closing costs, or both, and buyers can contribute as little as $500 of their own funds (IHFA down payment assistance). The assistance is a second mortgage that you repay in small monthly payments alongside your main loan.
IHFA gives its own example: on a $400,000 home with an Idaho Housing conventional loan, the minimum down payment would be $12,000 (3%). With down payment assistance, the buyer could bring just $500 and IHFA would finance the rest (IHFA example).
To be eligible, your household income must be at or below $170,000 (some loan programs set lower limits), and you must complete Finally Home! homebuyer education. The assistance is open to all eligible Idaho buyers, not only first-time buyers. You use it through an IHFA-approved lender (IHFA homebuyers).
A quick trade-off to understand: because the assistance is a repayable second loan, it adds a monthly payment. It is often worth it when the alternative is waiting years to save or draining your emergency fund, and we will show you the payment both ways.
Idaho's first-time homebuyer savings account
Idaho lets first-time buyers save for a home in a special account and deduct the contributions on their Idaho income tax return (Idaho State Tax Commission):
- Single filers can contribute and deduct up to $15,000 a year, and married couples filing jointly up to $30,000.
- Deposits cannot exceed $100,000 over the life of the account, including interest.
- You cannot withdraw anything in the first 30 days after opening the account.
- Withdrawals are tax-free when used for the down payment, required buying costs, or a VA funding fee. Other withdrawals are taxable.
- For this account, a first-time homebuyer is someone who has never owned a single-family or multifamily residence anywhere.
If you are a year or two away from buying, opening one of these accounts early can make a real difference. Talk to a tax professional about your own situation.
Loan options for first-time buyers in Idaho
Conventional with 3% down
Qualified buyers can put as little as 3% down on a one-unit primary home (Fannie Mae eligibility matrix). Private mortgage insurance applies below 20% down and can be cancelled once you reach 80% of the original value (CFPB on PMI).
FHA with 3.5% down
FHA allows 3.5% down with a 580 or higher score and is more flexible on credit history (HUD FHA overview). It adds a 1.75% upfront premium and an annual premium, 0.55% for most loans with less than 5% down (HUD Mortgagee Letter 2023-05). In 2026, the one-unit FHA limit is $586,500 in the Boise metro, $572,700 in the Coeur d'Alene area, and $759,000 in the Hailey area (HUD lookup).
VA with 0% down
Eligible veterans and service members can buy with no down payment and no monthly mortgage insurance (VA purchase loans). A one-time funding fee applies unless exempt (VA funding fee).
USDA with 0% down
USDA guaranteed loans allow no down payment in eligible rural areas for households under the income limits (USDA guaranteed loans). Many towns outside the Boise metro can qualify. Check an address on the USDA eligibility map.
The 2026 conforming limit is $832,750 in 43 of Idaho's 44 counties, and $1,249,125 in Teton County (FHFA).
After you move in: the homeowner's exemption
Once the home is your primary residence, apply for Idaho's homeowner's exemption with your county assessor. It removes 50% of the value of your home and up to one acre of land from property taxes, capped at $125,000 (Idaho State Tax Commission). Your first escrow estimate may be based on taxes without the exemption, so filing promptly helps your payment come down at the next escrow review.
First-time buyer steps with Summit
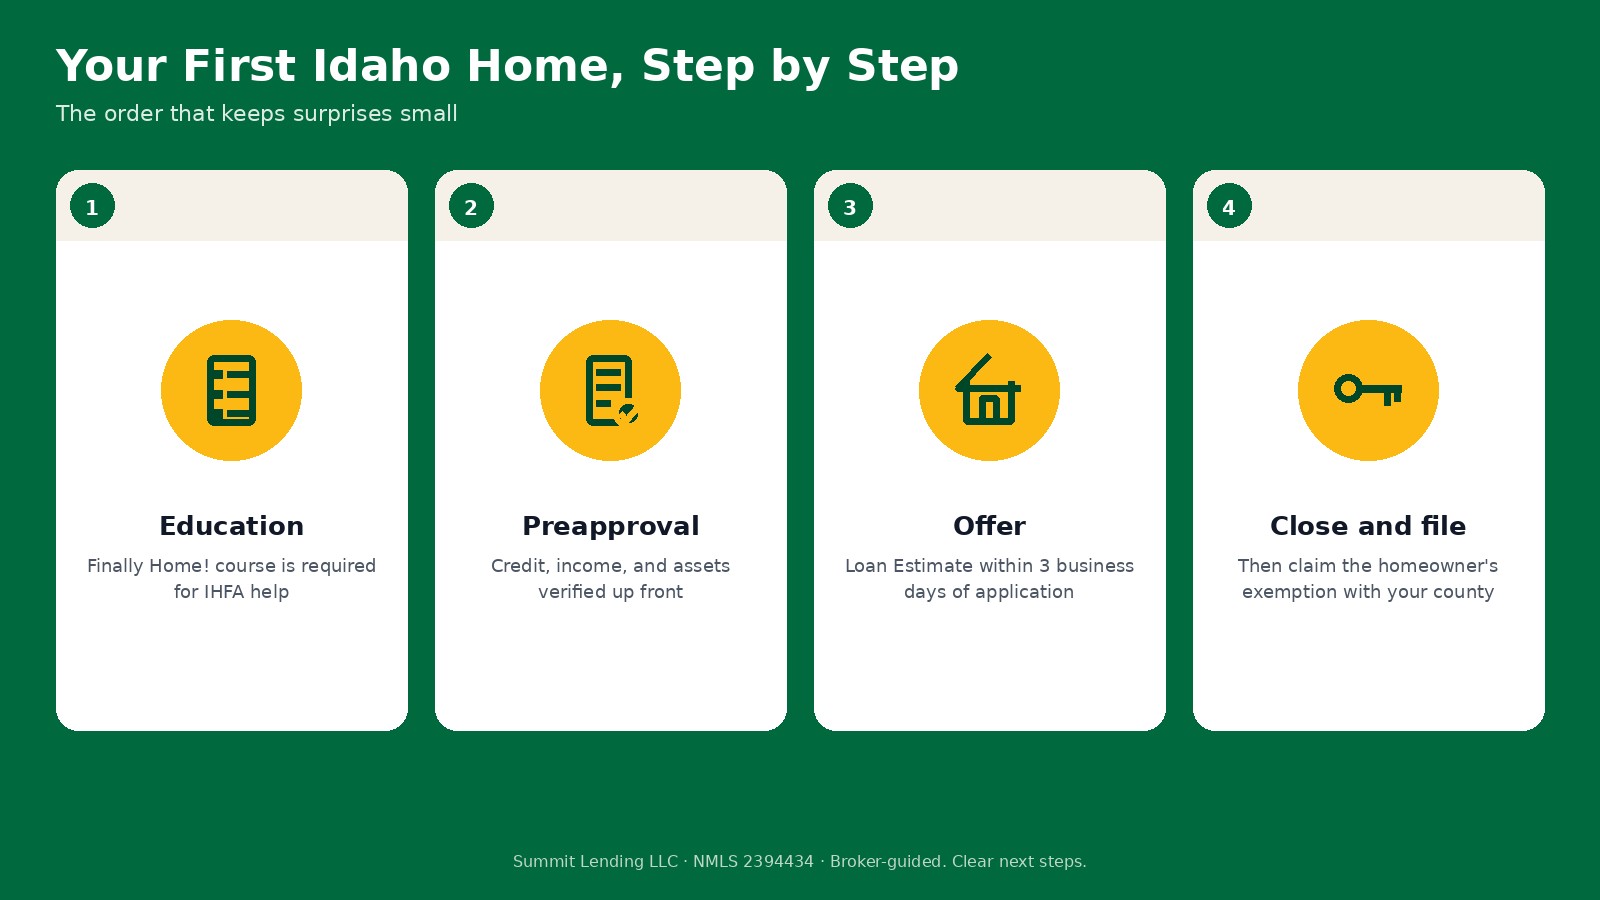
- Take homebuyer education. Finally Home! is required for IHFA assistance and useful even if you do not use it.
- Get preapproved. We verify credit, income, and assets up front. Lenders use prequalification and preapproval differently, so ask what was verified (CFPB comparison). Several mortgage credit checks within 45 days count as one inquiry (CFPB).
- Make an offer. Once you are under contract, your Loan Estimate arrives within three business days of application (CFPB on Loan Estimates).
- Close and file. Your Closing Disclosure comes at least three business days before signing (CFPB). Then file for the homeowner's exemption.
Lenders also look at your debt-to-income ratio, which compares monthly debts, including the new payment, with gross monthly income (CFPB on DTI). Paying down a car loan or credit card before you apply can open up more options.
Where we help first-time buyers in Idaho
Treasure Valley: Boise, Nampa, Caldwell, Kuna, Star, Ada County, and Canyon County. Eastern and Southern Idaho: Idaho Falls, Rexburg, Pocatello, Twin Falls, Bonneville County, Bannock County, and Madison County. North Idaho: Coeur d'Alene, Post Falls, Sandpoint, Moscow, and Kootenai County.
Related pages
Compare Idaho purchase loans, read the Idaho mortgage overview, or see first-time buyer guides for Utah, Texas, and Wyoming.
Sources
- Redfin, Idaho housing market
- Boise Regional REALTORS, Ada County August 2026 (PDF)
- Freddie Mac PMMS, Oct 1, 2026 release
- Idaho Housing and Finance Association, down payment help
- Idaho Housing and Finance Association, homebuyers
- Idaho State Tax Commission, first-time homebuyer savings account
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- HUD, Let FHA loans help you
- HUD Mortgagee Letter 2023-05, FHA annual MIP (PDF)
- HUD FHA mortgage limits lookup
- VA purchase loan
- VA funding fee and closing costs
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- FHFA, 2026 conforming loan limits
- Idaho State Tax Commission, homeowner's exemption
- CFPB, prequalification vs. preapproval
- CFPB, when a lender checks your credit
- CFPB, What is a Loan Estimate?
- CFPB, What is a Closing Disclosure?
- CFPB, debt-to-income ratio
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.
Our Process Is Straightforward
With Summit Lending, you can be rest assured that our mortgage loan experts will guide you throughout the process, from exploring your loan options to approval.