
Idaho Housing Down Payment Assistance at 7.32%: What the 8% Second Mortgage Really Costs (Oct 2026)


Key Takeaways
Q: Where are mortgage rates this week?
Freddie Mac's Primary Mortgage Market Survey put the average 30-year fixed at 7.32% on October 22, 2026, down from 7.40% the week before. A year ago it was 6.19%. The 15-year fixed averaged 6.68%, down from 6.71% (Freddie Mac PMMS, Oct. 22, 2026). The Mortgage Bankers Association's survey for the week ending October 16 had the average FHA contract rate at 7.13% with 1.15 points (MBA, Oct. 21).
Q: What is Idaho Housing's down payment assistance right now?
It is a second mortgage, not a grant. Idaho Housing and Finance Association (IHFA) lends up to 8% of the lower of the price or appraised value, on a 15-year fixed loan at your first mortgage rate plus 2.00%. You put in at least $500 of your own money. Household income can be up to $170,000 for most IHFA loans, and you must take the Finally Home! homebuyer class (IHFA Lender Connection rate sheet).
Q: What does it cost each month?
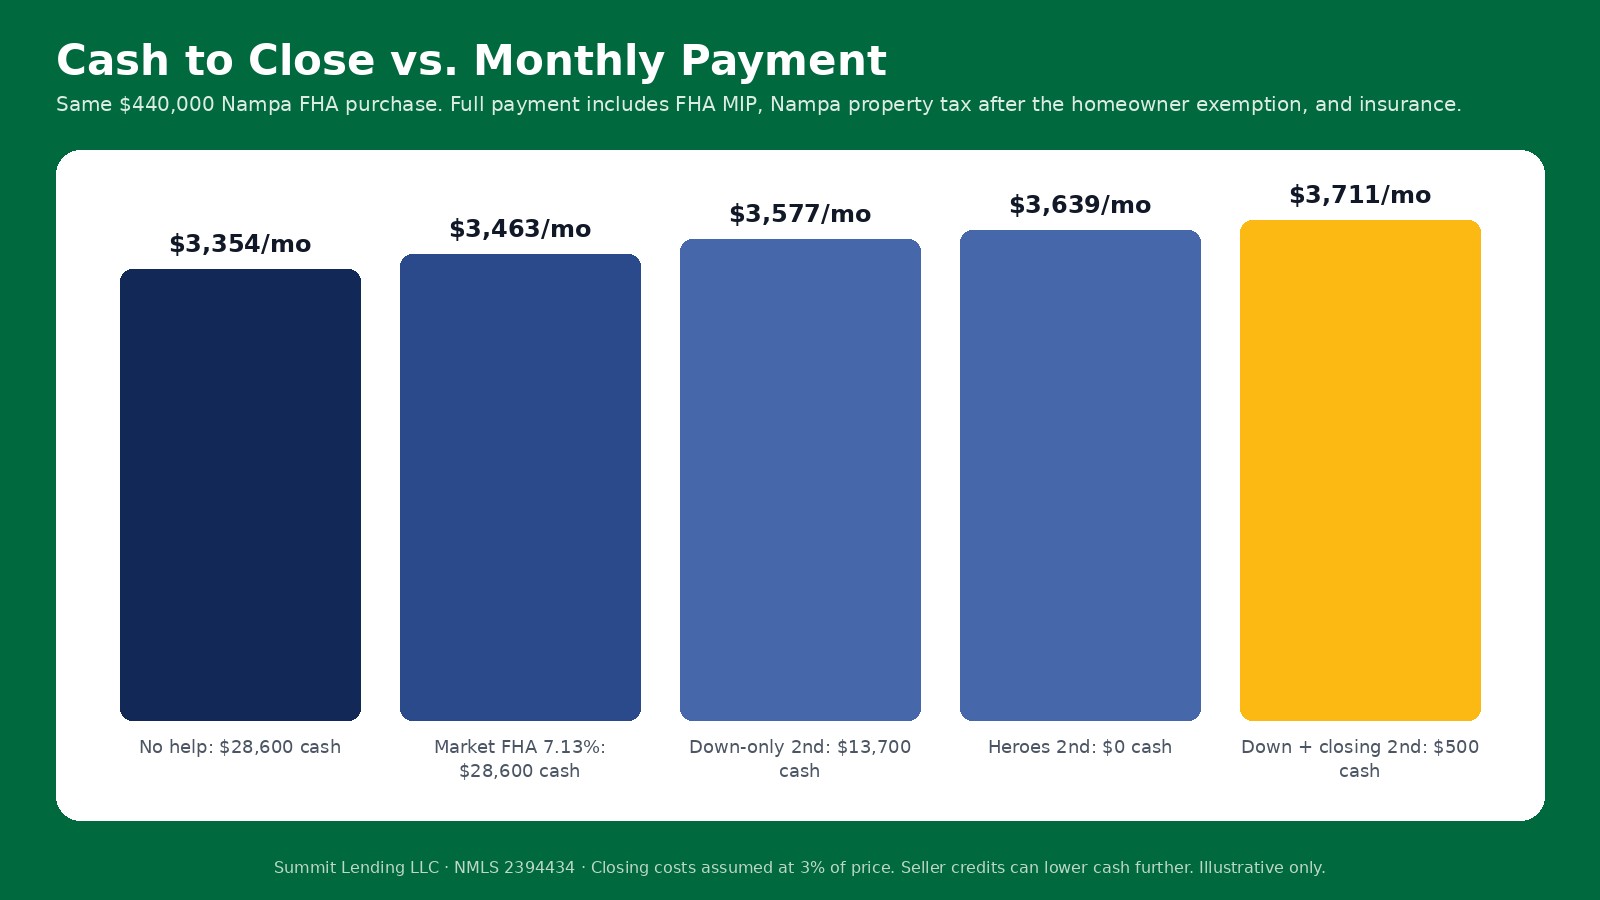
On a $440,000 Nampa home with an FHA first mortgage, a second that covers the 3.5% down payment and about 3% in closing costs runs about $285 a month at 9.00%. Add a small rate add-on on the first mortgage, and the full payment in my example goes from about $3,354 with no help to about $3,711 with help. That is roughly $357 a month to keep about $28,100 in your savings account.
Q: Who should use it?
Buyers with steady income who can carry the extra payment, but who would otherwise empty their savings to close. If you have the cash and a reserve left over, paying your own down payment is cheaper. Teachers, nurses, and first responders should ask about Idaho Heroes, which waives the $500 minimum and, on the current rate sheet, the first-mortgage rate add-on.
This week gave Idaho buyers a small break. After rising for two months, Freddie Mac's 30-year average slipped eight basis points to 7.32%. That is about $24 a month on a typical Nampa FHA loan, which is nice but will not change anyone's life. What it did do is bring a wave of calls from renters in the Treasure Valley who want to know if now is the moment, and nearly every one of them asks the same follow-up: "Can I get help with the down payment?"
In Idaho the answer usually runs through one place, Idaho Housing and Finance Association. IHFA's help is real, and a lot of people use it. IHFA told the Idaho Statesman this month that it worked with about 4,500 buyers over the past 12 months, and about 2,500 of them took down payment assistance through a second lien (Idaho Statesman, Oct. 4). But it is a loan with its own payment, its own rate, and its own balance when you sell. The marketing line, "as little as $500 out of pocket," is true. It just is not the whole story.
I am Brodie Calder, a loan officer with Summit Lending (NMLS 300501). In this guide I will walk through exactly how IHFA's 8% second mortgage works this month, what it costs on a $440,000 Nampa home and a $575,000 Ada County home at today's rates, how the tax-exempt First Loan and Idaho Heroes options change the math, and how to decide whether to borrow the help, borrow part of it, or skip it. Every payment example is illustrative and labeled with its assumptions. Your rate, eligibility, and approval depend on your credit, income, assets, the property, and program rules on the day you lock.

Where Idaho Rates and Prices Stand in Late October 2026
Assistance only makes sense in context, so here is the data that came out over the past three weeks, each number tied to its source.
- Rates eased for the first time in two months. Freddie Mac's 30-year average fell to 7.32% on October 22 from 7.40% on October 15, after climbing from 6.95% in mid-September. The year-ago figure was 6.19% (Freddie Mac). MBA's survey showed the same turn: the conforming 30-year contract rate dropped to 7.41% from 7.50%, FHA to 7.13% from 7.19%, and the 5/1 ARM to 6.46% (MBA).
- Buyers have not jumped back in yet. MBA's purchase index fell 7% for the week and was 18% below the same week last year. MBA's Joel Kan said plainly that "the higher mortgage rate environment has cooled the housing market this fall."
- Ada County prices held. Boise Regional REALTORS reported a September median sale price of $575,000 for Ada County single-family homes, up 2.9% from a year earlier, with 854 closed sales, 39 median days on market, and 2.4 months of supply (BRR Ada County, Sept. 2026).
- Canyon County is the value market. Canyon's September median was $443,523, up 5.1%, with 419 sales, 48 days on market, and 2.6 months of supply (BRR Canyon County, Sept. 2026).
- Price cuts are rising. West Real Estate Group counted 567 price reductions in the Treasure Valley for October 5 to 11, up about 35% from 420 in the same week of September. Pending sales slipped to 291 from 318, active listings rose to 3,872, and the Ada County median list price eased to $625,000 (West Real Estate Group, Oct. 12).
- The fall slowdown is showing in the pipeline. Pioneer Title's PTC Index fell to 258 in September from 294 in August. New home sales dropped 16.5% from August, and building permits fell for a third straight month, down 35% from September 2025 (Pioneer Title, Oct. 15).
- Statewide, it is a buyer's market on paper. Realtor.com's October snapshot shows a $593,000 median listing price, a $455,947 median sold price, 21,499 active listings, 61 median days on market, and homes selling about 2% below asking (Realtor.com Idaho).
Put together, this is a decent month to negotiate. Sellers are cutting prices and paying closing costs more often than they were in the spring, and that matters for assistance, because every dollar the seller pays toward your closing costs is a dollar you do not have to borrow at 9%. If you want to see how these numbers play out in your own county, the Idaho mortgage calculator and the Canyon County calculator let you plug in your own price, tax, and insurance.
How IHFA Down Payment Assistance Actually Works
A lot of older articles still describe forgivable grants and the Idaho Mortgage Credit Certificate. Those are not what buyers are getting this fall. Here is the program as it reads on IHFA's own pages this month.
The 15-year second mortgage
- Amount: up to 8% of the lower of the sales price or the appraised value. It can go toward the down payment, closing costs, or both (IHFA down payment assistance).
- Rate: your first mortgage rate plus 2.00%, fixed for 15 years. If your first mortgage is 7.00%, the second is 9.00%.
- Payment: it is a fully amortizing loan with a monthly payment. IHFA says so directly in its FAQ: "Yes. Whether you use a second mortgage or forgivable loan, your monthly payment will increase slightly." The payment counts in your debt-to-income ratio.
- Your money in: occupying borrowers must contribute at least $500 of their own funds. IHFA notes this can be earnest money, the appraisal, the inspection, or the homebuyer class fee, not only the down payment.
- Purchase only: the second is not available on a refinance.
- Limits on stacking: the combined loan amount cannot exceed what the mortgage insurance and agency guidelines allow.
- Education: one Finally Home! certificate per loan is required when you use the assistance.
The first mortgage underneath it
You cannot take the second by itself. It sits behind an IHFA first mortgage, which can be FHA, USDA Rural Development, or one of the conventional HFA products, Fannie Mae HFA Preferred or Freddie Mac HFA Advantage. IHFA also makes VA loans, but the VA section of its rate sheet does not list the second mortgage as an option. Those conventional HFA products allow up to 97% loan-to-value and have no first-time buyer requirement. Standard mortgage insurance applies for borrowers above 80% of area median income, which means buyers under that line may see reduced insurance (IHFA rate sheet).
Two other rate sheet details matter. First, there is a rate add-on to the first mortgage when you use the assistance. The current sheet lists that add-on as waived for Idaho Heroes borrowers, and IHFA's February program sheet described it as reduced by 0.125% for Heroes on conventional HFA loans. Everyone else pays it, and the exact size comes from pricing on the day you lock (IHFA DPA program sheet, Feb. 11, 2026). Second, IHFA prices smaller loans lower. Its low loan balance chart, published October 21, 2026, cuts 0.25% off the rate for conventional purchase loans up to $175,000 and 0.125% for loans up to $250,000, with no reduction above $275,000 (IHFA low loan balance chart, Oct. 21, 2026). Most Treasure Valley loans are well above that, but it can help in Pocatello, Twin Falls, or a condo purchase.
What IHFA is advertising this week
IHFA's homebuyer page currently advertises 30-year mortgages "as low as 6.75%" with a 6.753% APR, subject to change (IHFA homebuyers page). That is an "as low as" number, not a quote for everyone, and it does not include the assistance add-on. Still, it is a useful anchor: it sits about half a point below Freddie Mac's 7.32% national average and below MBA's 7.13% FHA average. I use 6.75% as the no-assistance IHFA rate in the examples below and 7.00% as an illustrative rate with assistance. Treat both as placeholders until a lender prices your actual file.
What is gone
Do not budget around a forgivable loan or the Idaho MCC. IHFA's current materials describe the assistance as a second mortgage only, and independent summaries checked against IHFA's documents in late September report that the forgivable option ended and the Mortgage Credit Certificate is listed as suspended (Proper Mortgage Quote, Sept. 26). If someone quotes you 10% assistance, they are describing the old combination.
The Math on a $440,000 Nampa Home
Let me run the numbers the way I would for a real buyer. Canyon County's September median was $443,523, so a $440,000 Nampa house is a fair test. The buyer uses an IHFA FHA first mortgage with 3.5% down.
Assumptions
- Price: $440,000. Down payment: 3.5%, or $15,400. Base loan: $424,600. Upfront FHA mortgage insurance: 1.75%, financed, for a total first loan of $432,031.
- Annual FHA mortgage insurance: 0.55%, about $195 a month in year one.
- Property tax: about $175 a month. That uses the 2025 certified levy of 0.6680% for Nampa code area 002-00 and the Idaho homeowner's exemption, which removes half the value up to $125,000 (Data Idaho, Nampa levy). Your code area may differ.
- Homeowners insurance: about $181 a month, from LendingTree's 2026 average of $2,177 a year for Nampa (LendingTree). Your quote will depend on the house and the carrier.
- Closing costs and prepaids: about 3% of price, or $13,200. This is an illustrative figure; your Loan Estimate is what counts.
- Rates: 6.75% for an IHFA first with no assistance (IHFA's advertised "as low as" rate), an illustrative 7.00% with assistance, and the second at 7.00% plus 2.00%, or 9.00%.
Without help, this buyer needs about $28,600 in cash: $15,400 down plus $13,200 in costs. That is the number that stops most first-time buyers I talk to in Nampa and Caldwell, not the monthly payment.
Four ways to buy the same house
| Option | Second mortgage | Second payment | First P&I | Full monthly payment | Cash you bring |
|---|---|---|---|---|---|
| IHFA first at 6.75%, no help | None | None | $2,802 | $3,354 | $28,600 |
| Market FHA at 7.13% (MBA average), no help | None | None | $2,912 | $3,463 | $28,600 |
| IHFA at 7.00%, second covers down payment only | $14,900 at 9.00% | $151 | $2,874 | $3,577 | $13,700 |
| IHFA at 7.00%, second covers down payment and costs | $28,100 at 9.00% | $285 | $2,874 | $3,711 | $500 |
| Idaho Heroes at 6.75%, second covers down payment and costs | $28,600 at 8.75% | $286 | $2,802 | $3,639 | $0 minimum |
Full payment includes principal and interest on both loans, FHA monthly mortgage insurance, property tax, and insurance. Illustrative only, not a rate quote.

What the table is really telling you
The full help costs about $357 a month in this example. Compare the no-help IHFA loan at $3,354 with the full-help version at $3,711. About $285 of that is the second mortgage payment and about $72 is the 0.25% add-on I assumed on the first. In exchange, you keep about $28,100 in the bank.
The second gets expensive if you hold it a long time. A $28,100 second at 9.00% over 15 years costs about $23,200 in interest if you never pay it off early. After five years you would still owe about $22,500, and you would have paid about $11,500 in interest on it. That balance is due when you sell or refinance, so it comes out of your equity.
Borrow only what you need. The down-payment-only version saves you about $134 a month compared with the full-help version. If you have $13,700 saved and would still keep a cushion after closing, that version is a cleaner deal. If paying closing costs yourself would leave you with nothing, borrow it.
A seller credit beats a 9% loan. With Treasure Valley price cuts up about 35% in a month, asking the seller to cover closing costs is reasonable on many listings. If a seller pays $13,200, you can use the smaller down-payment-only second and save about $134 a month for as long as you keep the loan. FHA allows seller concessions up to 6% of the price, so this is not an unusual ask right now. You can compare offers with our Nampa purchase loan page or our Canyon County purchase options.
The weekly rate dip matters less than the structure. The move from 7.40% to 7.32% is worth about $24 a month on this loan. Choosing a down-payment-only second instead of the full amount is worth $134. Getting a seller credit can be worth more than both. Structure is where the money is.
The income side
Lenders look at your total debt-to-income ratio, and the second payment counts. Assuming $450 a month in other debts (a car payment and a card, for example), here is roughly what this buyer needs to earn:
- No help at 6.75%: about $101,400 a year at a 45% ratio.
- Down-payment-only second: about $107,400 at 45%, or $96,600 at 50%.
- Full down payment and closing cost second: about $111,000 at 45%, or $99,900 at 50%.
FHA automated underwriting can approve ratios near 50% with strong credit and reserves, but I would not plan a budget around the maximum. The question I ask every buyer is simple: if your car needed $2,000 in repairs in month three, would the payment still work? If you are not sure where you land, a Nampa preapproval or a Canyon County preapproval will show the real ratio on paper before you write an offer.
The Math on a $575,000 Ada County Home
Ada County is a different problem. The September median was $575,000, and most buyers there are not FHA buyers. Let me use a conventional IHFA HFA Preferred loan with 3% down.
- Price: $575,000. Down payment: 3%, or $17,250. Loan: $557,750.
- Private mortgage insurance: I use 0.45% a year, about $209 a month, as an illustrative figure. Real MI pricing depends on credit score, and HFA Preferred buyers under 80% of area median income may get reduced coverage.
- Property tax: about $168 a month, using Meridian code area 03-15's 2025 certified levy of 0.4479% after the homeowner's exemption (Data Idaho, Meridian levy).
- Insurance: about $175 a month, from LendingTree's 2026 Meridian average of $2,100 a year.
- Closing costs: about 3%, or $17,250. Cash to close without help: about $34,500.
| Option | Rate | First P&I | Second payment | Full monthly payment | Income needed at 45% (with $450 debts) |
|---|---|---|---|---|---|
| Market benchmark (Freddie Mac average) | 7.32% | $3,831 | None | $4,383 | about $128,900 |
| IHFA HFA Preferred, no help | 6.75% | $3,618 | None | $4,170 | about $123,200 |
| IHFA with second for down payment ($16,750) | 7.00% / 9.00% | $3,711 | $170 | $4,433 | about $130,200 |
| IHFA with second for down payment and costs ($34,000) | 7.00% / 9.00% | $3,711 | $345 | $4,608 | about $134,900 |
Illustrative only. Freddie Mac's average assumes 20% down and strong credit, so a 3% down buyer would usually see different pricing.
Two things stand out. First, the gap between the national average and a year ago is large here: at 6.19%, this same loan would have cost about $419 a month less in principal and interest. This week's dip from 7.40% saves about $30. Second, look at the income column. A household that qualifies for a $575,000 Ada County home with full assistance needs roughly $135,000, which is under IHFA's $170,000 cap for its regular loans but above the income limits for IHFA's tax-exempt First Loan in Ada County. That brings us to the next section. If you are shopping in Boise, Meridian, or Kuna, the Ada County calculator and the Boise mortgage calculator are good places to test your own price.
First Loan Tax-Exempt: The Lower Rate With Rules Attached
IHFA brought back its tax-exempt mortgage revenue bond program this year, with locks starting March 9, 2026 (IHFA Program Bulletin 2026-4). Because the bonds are tax-exempt, the rate is usually lower than IHFA's regular pricing. You can still pair it with the same 8% second mortgage. In exchange, federal bond rules apply:
- First-time buyer test: you must not have owned a primary residence in the past three years, unless you buy in a targeted county.
- County income and price limits: lower than the $170,000 cap that applies to regular IHFA loans. New limits took effect for reservations on or after May 1, 2026 (IHFA Program Bulletin 2026-6).
- Household income, not just borrower income: bond programs generally count income from adults living in the home, even if they are not on the loan. Ask your lender to run this test early.
- Purchase only, with post-closing compliance review and federal recapture disclosures. Recapture can apply if you sell within nine years with a large gain and your income has risen; your lender must give you the recapture notice, and you should read it.
Here are the 2026 First Loan limits for the counties I get asked about most, as compiled from IHFA's chart (IHFA borrower income limits; summary via Proper Mortgage Quote). Always confirm against IHFA's current chart before you rely on them.
| County | Targeted? | Income limit, 1 to 2 people | Income limit, 3 or more | Price limit |
|---|---|---|---|---|
| Ada (Boise, Meridian, Kuna, Star) | No | $110,700 | $127,305 | $613,662 |
| Canyon (Nampa, Caldwell, Middleton) | Yes | $132,840 | $154,980 | $750,031 |
| Kootenai (Coeur d'Alene, Post Falls) | Yes | $124,200 | $144,900 | $732,383 |
| Bonneville (Idaho Falls) | No | $101,600 | $116,840 | $566,354 |
| Bannock (Pocatello) | No | $101,600 | $116,840 | $566,354 |
| Twin Falls | No | $102,294 | $117,639 | $566,354 |
Look at Canyon County. It is a targeted county, so you do not have to be a first-time buyer, and its income limits are higher than Ada's. A family of three earning $140,000 can use First Loan in Nampa or Caldwell, but not in Meridian. That is one more reason Canyon County is where I see Idaho Housing loans used most. If you are weighing the two counties, our Canyon County first-time buyer guide and Ada County first-time buyer guide lay out the local details, and Caldwell and Nampa have their own pages.
For the $575,000 Ada example above, the household that qualifies with full assistance at roughly $135,000 would be above Ada's $127,305 First Loan limit for three or more people. That buyer is on IHFA's regular pricing, or a standard conventional loan. A lower price or a smaller household can change the answer. First Loan also does not allow a non-occupying co-borrower, so a parent cannot co-sign to make it work. Run the test before you fall in love with a house.
Outside the Treasure Valley, the targeted county rule also helps in places like Kootenai. Buyers there can start with our Kootenai County first-time buyer page or a Coeur d'Alene preapproval. In eastern Idaho, see Bonneville County and Idaho Falls purchase loans. In the Magic Valley, start with Twin Falls, and for Pocatello, a Pocatello preapproval.
Idaho Heroes: The Best Version of the Deal, If You Qualify
Idaho Heroes uses the same 8%, 15-year second mortgage at the first rate plus 2.00%, with two improvements. The $500 minimum contribution is waived, and the current rate sheet says the rate add-on to the first mortgage for the assistance is waived (IHFA rate sheet). The rate sheet lists nurses, teachers, and first responders (firefighters, police, paramedics, and EMTs). IHFA's February program sheet also listed active military and veterans, so if you are in that group, ask your lender to confirm current eligibility.
In the Nampa example, Heroes pricing lowers the full-help payment from about $3,711 to about $3,639, roughly $72 a month, because the first mortgage stays at 6.75% and the second drops to 8.75%. Over five years that is more than $4,300. If you teach in the Nampa or Vallivue school districts or work a shift at a Treasure Valley hospital, ask about it on your very first call.
When IHFA Help Makes Sense, and When It Does Not
It usually makes sense when
- You have stable income and can handle the full payment with room to spare, but paying 3.5% down plus closing costs would leave you with less than two or three months of expenses in savings.
- You expect to stay at least several years and do not plan to refinance soon. A second that has to be paid off at a refinance makes a future rate drop harder to use.
- You are buying in a targeted county like Canyon or Kootenai and can combine the second with First Loan pricing.
- You qualify for Idaho Heroes.
It usually does not make sense when
- You have the cash and a reserve left over. Paying your own way avoids a 9% loan and keeps your ratio lower.
- Your debt-to-income ratio is already tight. Adding $150 to $350 a month can push an approval over the line.
- The seller is willing to pay most of your closing costs. Then a smaller second, or none, often works.
- You expect to sell or move within two or three years. You will repay most of the second out of your sale proceeds, and with Treasure Valley prices only up 2% to 5% this year, there may not be much equity to absorb it.
A quick self-check before you call a lender
- How much cash do you have today, and how much do you want left after closing? Write both numbers down.
- What monthly payment, all in, would let you still save something each month?
- Is your household income under $170,000? If you want First Loan, is it under your county's limit, counting everyone 18 or older who will live there?
- Have you owned a home in the past three years? That only matters for First Loan outside targeted counties.
- Are you a teacher, nurse, first responder, active military member, or veteran?
- How long do you realistically expect to keep this home and this loan?
Five Mistakes I See With Idaho Down Payment Assistance
- Borrowing the full 8% by default. You can only use what the transaction needs, and every extra dollar is borrowed at about 9%. Size the second to the gap, not the maximum.
- Skipping the seller credit conversation. In a month with more price cuts and more listings, a credit toward costs is often easier to get than a price cut, and it reduces how much you have to borrow.
- Forgetting the homeowner's exemption. The tax figures in this article assume you get the exemption, which removes half your home's value, up to $125,000, from property tax. You have to apply with your county assessor after you move in. Missing it can add well over $50 a month in Nampa.
- Ignoring the refinance trap. If rates fall a full point next year, a refinance has to pay off the second too. That raises the new loan amount and can limit your options if values have not grown. Plan for that before you sign.
- Waiting for the class. Finally Home! is required when you use the assistance. Take it before you shop so it does not hold up a contract. It also covers budgeting and maintenance, and it is genuinely useful for first-time owners.
How the Process Works, Step by Step
- Get preapproved with an IHFA-approved lender. IHFA loans and assistance must go through one of its lending partners, and IHFA keeps a directory on its site. Ask any lender, including us, to confirm IHFA approval status and to quote the same file with and without assistance. You can start with an Idaho preapproval, or go local with Ada County, Boise, or Kuna.
- Take Finally Home! One certificate covers the loan.
- Shop with a real budget. Use the full payment, not just principal and interest. Our Nampa calculator and Caldwell calculator include tax and insurance fields.
- Write the offer with your financing in mind. Ask for a seller credit where the market allows it. Our Boise purchase loan page, Ada County purchase options, Kuna, and Middleton pages cover local loan choices.
- Lock, then size the second. Once your rate and costs are set, the second is sized to the actual gap between your cash and what the transaction needs.
- After closing, file your homeowner's exemption and keep an eye on both payments. IHFA says its home loans are serviced by HomeLoanServ, so that is who you will hear from.
If you are building instead of buying resale, the assistance can work on new construction purchases too, but builder incentives change the math. I covered that in new construction vs. resale and builder incentives in Idaho, and you can read about Idaho construction loans if you are building on your own lot.
Frequently Asked Questions
Is Idaho Housing's down payment assistance a grant?
No. The current program is a 15-year fixed second mortgage at your first mortgage rate plus 2.00%, with a monthly payment. It has to be repaid, either monthly over 15 years or in full when you sell or refinance.
Do I have to be a first-time buyer?
Not for IHFA's regular loans or the second mortgage. IHFA says its assistance is "available to all eligible Idaho homebuyers, not just first-time homebuyers." Only First Loan tax-exempt has a first-time buyer test, and that test is waived in targeted counties like Canyon and Kootenai.
What is the income limit?
$170,000 of household income for most IHFA loans. First Loan tax-exempt uses lower county limits, for example $110,700 for one to two people and $127,305 for three or more in Ada County.
What credit score do I need?
IHFA's rate sheet defers to the agency guidelines for the loan type. IHFA's homebuyer page says a score of 620 or higher is typically beneficial. In practice, your score affects your mortgage insurance and pricing more than your eligibility.
How much does the second mortgage add to my payment?
At a 9.00% second rate over 15 years, every $10,000 you borrow adds about $101 a month. In the Nampa example, a $14,900 second costs about $151 a month and a $28,100 second about $285.
Did this week's rate drop change the math?
A little. Freddie Mac's average fell from 7.40% to 7.32% on October 22, which is worth about $24 a month on a $432,000 loan. Because the second is priced off your first rate, a lower first rate also lowers the second. The bigger levers are how much you borrow and whether the seller pays costs.
Can I use the assistance with a seller credit?
Yes, as long as the total does not exceed what you need for the transaction and stays within the loan program's limits on seller contributions. In practice, a seller credit usually reduces how much assistance you need.
What happens if I refinance or sell?
The remaining balance of the second is paid off from the sale or the new loan. In the Nampa example, about $22,500 of a $28,100 second would still be owed after five years.
Is the Idaho Mortgage Credit Certificate available?
Not right now. It is listed as suspended, so do not count it in your budget.
Should I wait for rates to drop further?
Nobody can promise where rates go next. MBA's data shows buyers pulling back, and Treasure Valley sellers are cutting prices more often, which gives you some leverage today. If the full payment works for you now and you have a cushion, buying in a softer month is a reasonable choice. If it only works after a refinance that may not happen, wait.
Can Summit Lending help with an Idaho purchase?
Yes. Summit Lending works with buyers across Idaho. We can price a standard loan and compare it with an assisted option on the same address, so you see the payment, the cash to close, and the income needed side by side. Ask us directly whether a specific IHFA product is available on your file.
Your Next Step
The right amount of help is the smallest amount that lets you close and still sleep at night. Here is how I would start:
- Get an online preapproval started, or go straight to the Idaho preapproval page, and ask for two quotes on the same file: with assistance and without.
- Run your own numbers on the mortgage calculator, then compare Idaho purchase loans and the broader Idaho mortgage options, including Ada County, Canyon County, and Nampa.
- New to buying? Start with the first-time home buyer center and the Idaho first-time buyer guide, then look at Boise and Star.
- Already own and thinking about a refinance instead? See Idaho refinance options.
- Call 385-200-1470 or email [email protected] and ask for an Idaho assistance comparison on a specific address. You can also reach me through my loan officer page.
Related reading: ARM or fixed for Idaho buyers, how Texas down payment assistance prices its help, Utah Housing's new FirstHome conventional loan, low down payment loans compared, Arkansas payments compared, what a $475,000 Phoenix home really costs, and what to do when rates are above 7%.
Summit Lending LLC, NMLS 2394434 · 4542 W 14800 N, Garland, UT 84312. Brodie Calder, NMLS 300501. Rates cited are published survey averages and program information as of the dates shown, not Summit Lending rate quotes or advertised rates: Freddie Mac PMMS of October 22, 2026, MBA Weekly Applications Survey for the week ending October 16, 2026, and IHFA's homebuyer page and Lender Connection rate sheet as viewed October 23, 2026 (low loan balance chart published October 21, 2026). The 7.00% first mortgage rate used with assistance is an illustrative assumption; IHFA's actual add-on is set at lock. Payment, cash-to-close, and income examples are illustrative and based on stated assumptions for price, mortgage insurance, property tax (2025 certified levies via Data Idaho), insurance (LendingTree 2026 averages), and closing costs; actual figures vary by property and borrower. Program summaries are based on IHFA's down payment assistance page, rate sheet, February 11, 2026 program sheet, and Program Bulletins 2026-4 and 2026-6; First Loan limits are as compiled from IHFA's chart and should be confirmed with IHFA's current chart. IHFA's guidelines control, terms and funding can change, and Summit Lending does not administer IHFA programs. Recapture and tax information is general and is not tax advice. Market statistics are from Boise Regional REALTORS (Intermountain MLS data as of October 8, 2026), West Real Estate Group, Pioneer Title, Realtor.com, and the Idaho Statesman as cited. Content is for general information and is not a commitment to lend. All loans subject to credit approval, program guidelines, and appraisal. Equal Housing Opportunity.
About the Author
Brodie has been in the mortgage industry for over 15 years. He has helped thousands of clients and families, led as a President/Principal Lending Manager overseeing many loan officers, and been par...



