Texas Home Purchase Loans
Texas home purchase loans, compared across lenders
Texas is one of the largest housing markets in the country, and it is not one market. A starter home in the suburbs of Houston, a townhome in Austin, a ranch property outside Waco, and a new build north of Dallas all finance differently. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed in Texas, headquartered in Garland, Utah. We compare purchase loans from multiple wholesale lenders so Texas buyers can see the real differences in rate, fees, down payment, and mortgage insurance before making an offer.
This page covers the Texas market this year, loan options, 2026 limits, Texas down payment programs, and Texas-specific costs that catch buyers off guard. Ready to shop? Start a Texas preapproval or test a payment in the Texas loan calculator.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
The Texas market in 2026
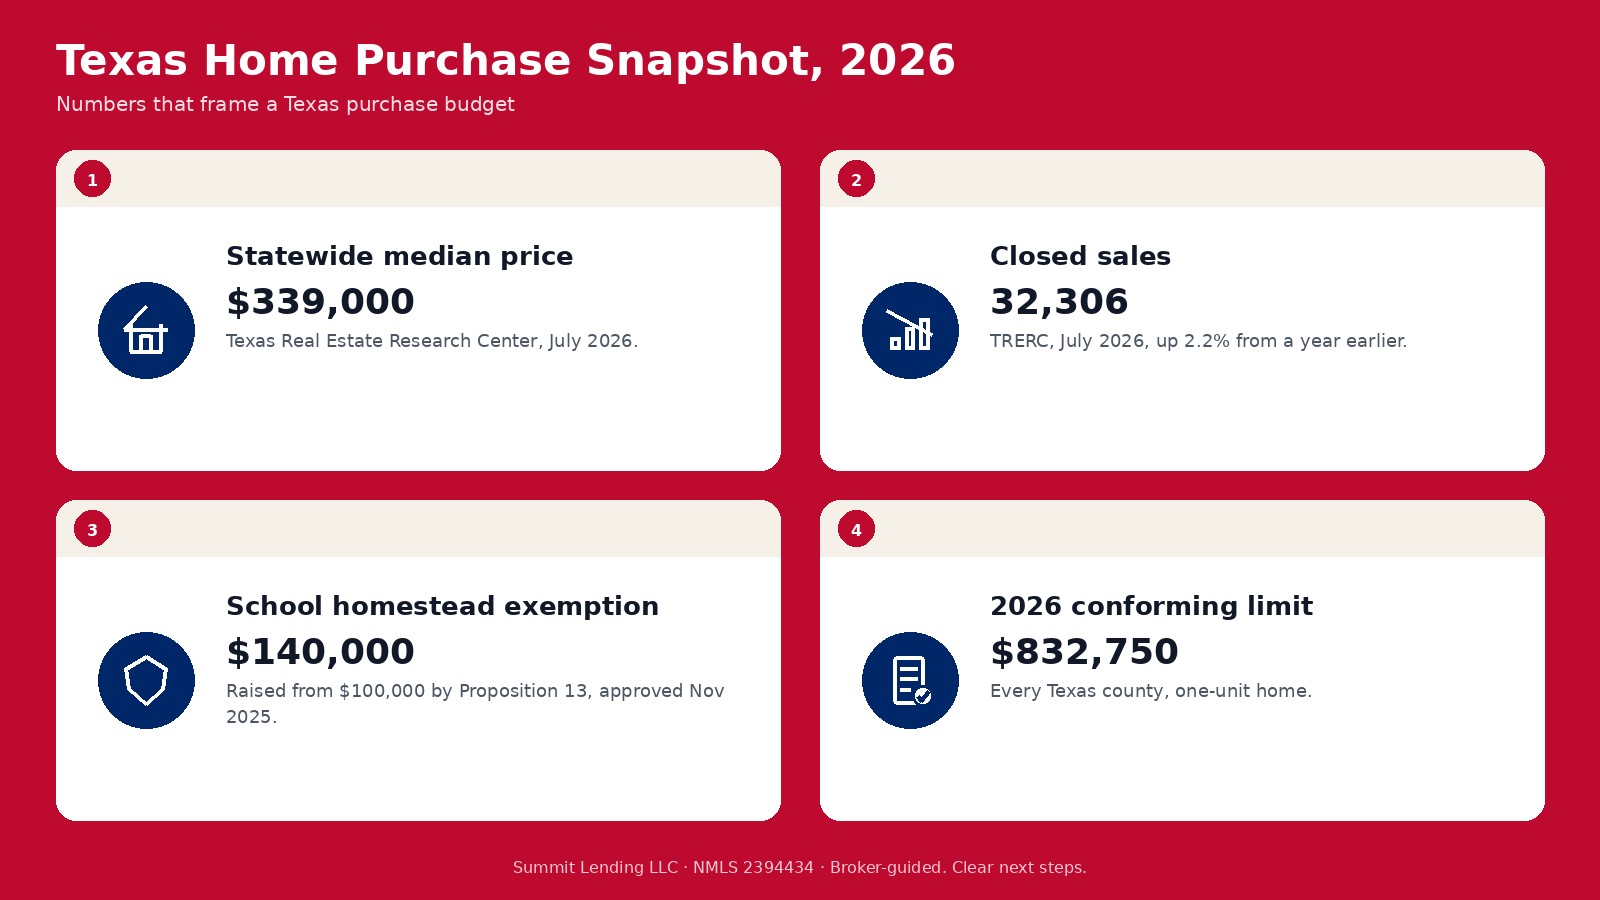
The Texas Real Estate Research Center at Texas A&M reported a statewide median sales price of $339,000 for July 2026, essentially flat from a year earlier, with 32,306 closed sales, up 2.2% (TRERC Texas Housing Insight). Steady prices and more sales suggest a market where buyers have choices and builders, in particular, are competing with incentives in many fast-growing suburbs.
Rates are the bigger story this fall. Freddie Mac's survey put the average 30-year fixed rate at 7.28% for the week of October 1, 2026, up from 7.03% a week earlier and 6.34% a year ago (Freddie Mac PMMS; history on FRED). These are national averages for strong-credit borrowers, not a quote. Builder rate buydowns can be valuable right now, but compare them carefully against a lower price.
Purchase loan options for Texas buyers
Conventional
Qualified buyers can put as little as 3% down on a one-unit primary home; Fannie Mae allows up to 97% loan-to-value on eligible fixed-rate purchases (Fannie Mae Eligibility Matrix). Private mortgage insurance applies below 20% down and can be cancelled at 80% of the original value (CFPB on PMI).
FHA
FHA loans allow 3.5% down with a 580 or higher credit score (HUD FHA overview) and are often the easiest fit for buyers with thinner credit or higher debt ratios.
VA
Texas has one of the largest veteran and military populations in the country. VA loans offer no down payment and no monthly mortgage insurance for eligible borrowers (VA purchase loans), with a one-time funding fee unless exempt (VA funding fee). Buyers near Fort Hood in Killeen, Joint Base San Antonio in Bexar County, and Fort Bliss in El Paso use VA financing often.
USDA
No-down-payment USDA guaranteed loans are available in eligible rural and some exurban areas for households under the income limits (USDA guaranteed loans). Check addresses on the USDA eligibility map, because areas around growing metros can change.
Jumbo
Every Texas county uses the 2026 baseline conforming limit of $832,750 for a one-unit home (FHFA announcement, FHFA county file). Above that, you need a jumbo loan. Jumbo purchases are most common in parts of Austin, Dallas, Houston, and suburbs like Plano and Sugar Land.
For FHA, HUD's 2026 one-unit floor is $541,287 and its ceiling is $1,249,125 (HUD announcement); check county limits on the HUD lookup tool.
Texas down payment and first-time buyer programs
TDHCA: My First Texas Home and My Choice Texas Home
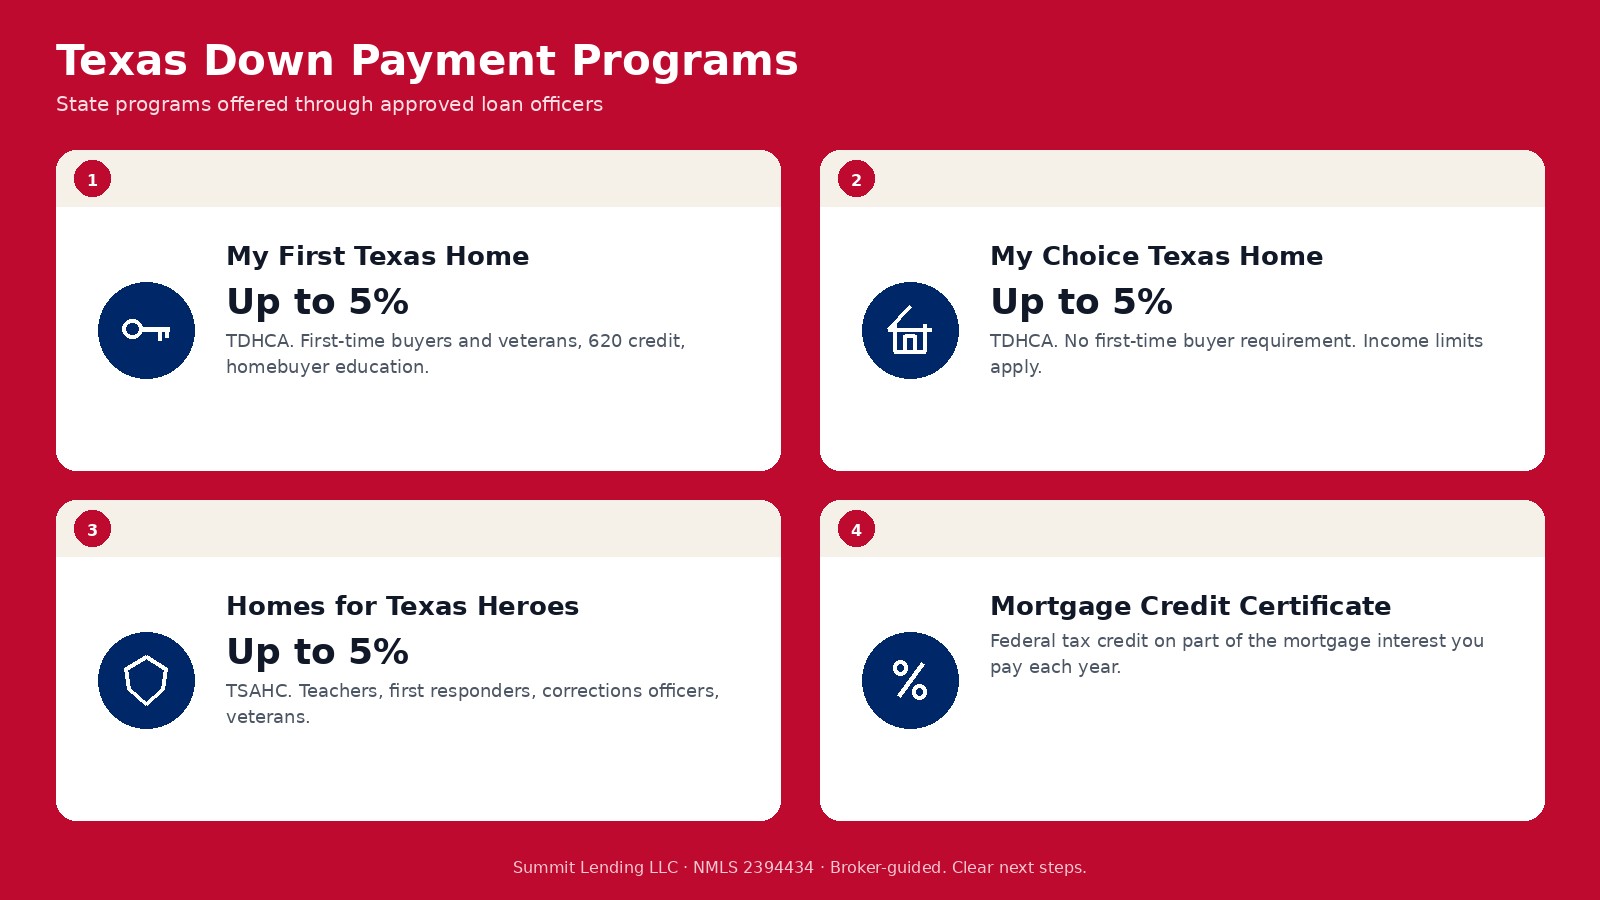
The Texas Department of Housing and Community Affairs (TDHCA) offers My First Texas Home, a 30-year fixed loan with down payment assistance of up to 5%. It requires a 620 credit score and homebuyer education. The first-time buyer requirement is waived for veterans and for properties in targeted areas. My Choice Texas Home offers similar assistance with no first-time buyer requirement. TDHCA also offers a Texas Mortgage Credit Certificate, which can provide a federal tax credit on part of the mortgage interest you pay. Income and purchase price limits apply (TDHCA program chart).
TSAHC: Homes for Texas Heroes
The Texas State Affordable Housing Corporation's Homes for Texas Heroes program serves teachers, police officers, firefighters, EMS personnel, corrections officers, veterans, and similar professions. It offers down payment assistance of up to 5%, structured either as a grant or a forgivable loan over three years (TSAHC Homes for Texas Heroes).
These programs are offered through approved loan officers and have specific pricing. We will compare them with a standard loan, because sometimes the assistance comes with a higher rate that costs more over time. More detail is on Texas first-time home buyer programs.
Texas costs to plan for
- Property taxes. Texas relies heavily on local property taxes, and rates vary widely by county, city, school district, and special districts such as MUDs. Always budget with the actual tax rate for the address.
- Homestead exemption. Texas voters approved Proposition 13 in November 2025, raising the school district homestead exemption from $100,000 to $140,000 (Ballotpedia on Proposition 13, Texas Comptroller exemptions). Apply with your county appraisal district after you move in. Your initial escrow may be calculated before the exemption applies.
- Title insurance. Texas title insurance premiums are set by the Texas Department of Insurance, so the basic premium is the same no matter which title company you use (TDI on title insurance). Endorsements and escrow fees can still vary.
- Homeowners insurance. Hail, wind, and flood risk affect premiums, especially on the Gulf Coast. Get quotes early, and check flood zone status before you commit.
- HOA and MUD fees. Common in new Houston and Dallas suburbs. They count in your debt-to-income ratio (CFPB on DTI).
How a Texas purchase works with Summit
- Preapproval. We verify credit, income, and assets and issue a letter. The CFPB notes that lenders use the words prequalification and preapproval differently, so what matters is what was verified (CFPB comparison). Multiple mortgage credit checks within 45 days count as one inquiry (CFPB).
- Offer and Loan Estimate. Once under contract, your Loan Estimate arrives within three business days of application (CFPB). If a builder offers a rate buydown, we compare it with a price reduction.
- Appraisal, survey, title. Texas purchases often involve a survey and title commitment. We track these with your agent and title company.
- Closing. You receive the Closing Disclosure at least three business days before signing (CFPB).
The CFPB's free buying guide is a good companion (CFPB Buying a House).
Where we help Texas buyers
Major metros: Houston, Dallas, Austin, Fort Worth, and El Paso. Suburbs: Plano, Katy, Sugar Land, and Pearland. Counties: Harris County, Dallas County, Travis County, Bexar County, Tarrant County, Collin County, Denton County, Williamson County, and Fort Bend County. Regional cities: Lubbock, Amarillo, Corpus Christi, Waco, and College Station.
Related pages
See Texas refinance options, Texas construction loans, Texas reverse mortgages, and the Texas mortgage overview. The national purchase loans page covers every state we serve, including Utah, Idaho, and Wyoming.
Sources
- Texas Real Estate Research Center, Texas Housing Insight
- Freddie Mac PMMS, Oct 1, 2026 release
- FRED, 30-Year Fixed Rate Mortgage Average
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- HUD, Let FHA loans help you
- VA purchase loan
- VA funding fee and closing costs
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- FHFA, 2026 conforming loan limits
- FHFA 2026 county loan limit list
- HUD No. 25-145, 2026 FHA loan limits
- HUD FHA mortgage limits lookup
- TDHCA homebuyer program chart (PDF)
- TSAHC, Homes for Texas Heroes
- Ballotpedia, Texas Proposition 13 (2025)
- Texas Comptroller, property tax exemptions
- Texas Department of Insurance, title insurance
- CFPB, debt-to-income ratio
- CFPB, prequalification vs. preapproval
- CFPB, when a lender checks your credit
- CFPB, What is a Loan Estimate?
- CFPB, What is a Closing Disclosure?
- CFPB, Buying a House
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.
Related Articles
Texas Property Taxes and Home Insurance: Budgeting the Real Mortgage Payment (Oct 2026)
Texas property tax bills go out in October, Harris and Dallas counties just raised rates, and TDI shows insurers filing for lower rates on average. Here is how the $140,000 homestead exemption, escrow, and insurance shape the payment you will actually make.
Texas Buyer's Market at 7.40%: How to Negotiate Price Cuts, Seller Credits, and Buydowns (Oct 2026)
Freddie Mac's 30-year average hit 7.40% on Oct. 8, while 69% of Texas Realtors say their buyers faced no competing offers this year. Here is how a price cut, seller credit, and rate buydown compare on an Austin-area home, plus the Texas contract tools that protect you.
Texas Down Payment Assistance at 7.40%: What TDHCA and TSAHC Help Really Costs (Oct 2026)
Texas down payment assistance is still available with rates at 7.40%, but the help usually comes with a higher rate. Using the TDHCA and TSAHC rate sheets from Oct. 19, 2026, here is what 2% to 5% assistance really costs each month on a $325,000 home, when it must be repaid, how the 15% MCC works, and which program fits your plans.Frequently Asked Questions
Everything you need to know about home mortgage loans in TexasYour ideal loan depends on several factors like your financial situation, long term goals, and risk tolerance. Fixed rate mortgages offer stability, while adjustable rate loans may save you money initially. Government-backed options can be great for those with lower credit scores. At Summit Lending, we’ll guide you through the options to find a perfect fit.