Texas Mortgage Preapproval
Your Guide To Home Loan Pre Approval in Texas
What Are Mortgage Loan Pre-Approvals?
A home loan pre-approval serves as a stamp of approval from lenders confirming your financial readiness to buy a home. Before you get pre-approved, the lender will evaluate your debt-to-income ratio and creditworthiness. Upon approval, you will receive a statement that serves as their conditional commitment to lending you money to buy your home while also showing how much they are willing to give you.
Pre-approval Vs Prequalification - What's The Difference?
A prequalification gives you a rough idea of how much you can borrow based on what you tell the lender about your finances. Pre-approval, on the other hand, means the lender has checked and confirmed your financial information, giving you a conditional thumbs-up for a specific loan amount.
When Should You Get Pre-Approved?
You can get approved for a mortgage in as little as one business day if your paperwork is in order, while other lenders may take longer. Pre-approvals are usually valid for 90 days. However, some lenders may keep it valid for 30 or 60 days.
We recommend you start before looking for a home to ensure you can make an offer on the home you like on time.
Do Pre-approvals Affect Your Credit Score?
Before you get preapproved for a mortgage, lenders carry out a hard pull of your credit to check your score, temporarily lowering it by a few points. However, you will have a 45-day window in which multiple credit score inquiries will be considered on your credit report. Are you worried about denial? You can ask the lender why your home loan pre approval was denied and address the issue.
However, when you work with mortgage loan specialists like us, we ensure you apply for the loans that best align with your financial situation, maximizing your chances of approval.
Pre-Approval Costs in Texas
You may be wondering if you need to pay money to get pre-approved for a mortgage loan in Texas. That depends on the lender you choose to work with. Some do it for free, while others demand a non-refundable application fee you must pay upfront, whether you get approved or not.
Texas mortgage preapproval: know your number before you make an offer
A preapproval tells you, and the seller, how much a lender is prepared to lend you after looking at your real credit, income, and assets. In Texas, it also shapes the financing terms you write into the contract, so getting it right before you shop is worth the effort. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed in Texas. We review your file with more than one wholesale lender in mind, so your preapproval reflects a loan you can actually close, at a price you have compared.
Want to see the payment first? Try the Texas mortgage calculator, then come back here.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
Why preapproval matters in Texas right now
Redfin put the Texas statewide median sale price at about $333,611 for August 2026 (Redfin Texas data). In Houston, homes were taking around 45 days to go under contract and selling for about 96.9% of list price (Redfin Houston data). That is a market where buyers can negotiate, but sellers still compare offers on how likely they are to close. A verified preapproval, with financing terms you understand, makes your offer easier to accept.
Rates matter just as much. Freddie Mac's survey put the 30-year fixed average at 7.28% for the week of October 1, 2026, compared with 7.03% a week earlier and 6.34% a year ago (Freddie Mac PMMS). On a $300,000 loan, principal and interest is about $2,053 a month at 7.28%, versus about $1,865 at last year's rate. A preapproval built on today's numbers keeps you shopping in the right range.
Prequalification versus preapproval
The CFPB notes that lenders do not use these terms the same way. Some prequalifications rely only on what you say, while some preapprovals involve full document and credit review. What matters is what was verified (CFPB comparison). At Summit, a preapproval means we have pulled credit and reviewed your income and asset documents.
What to gather
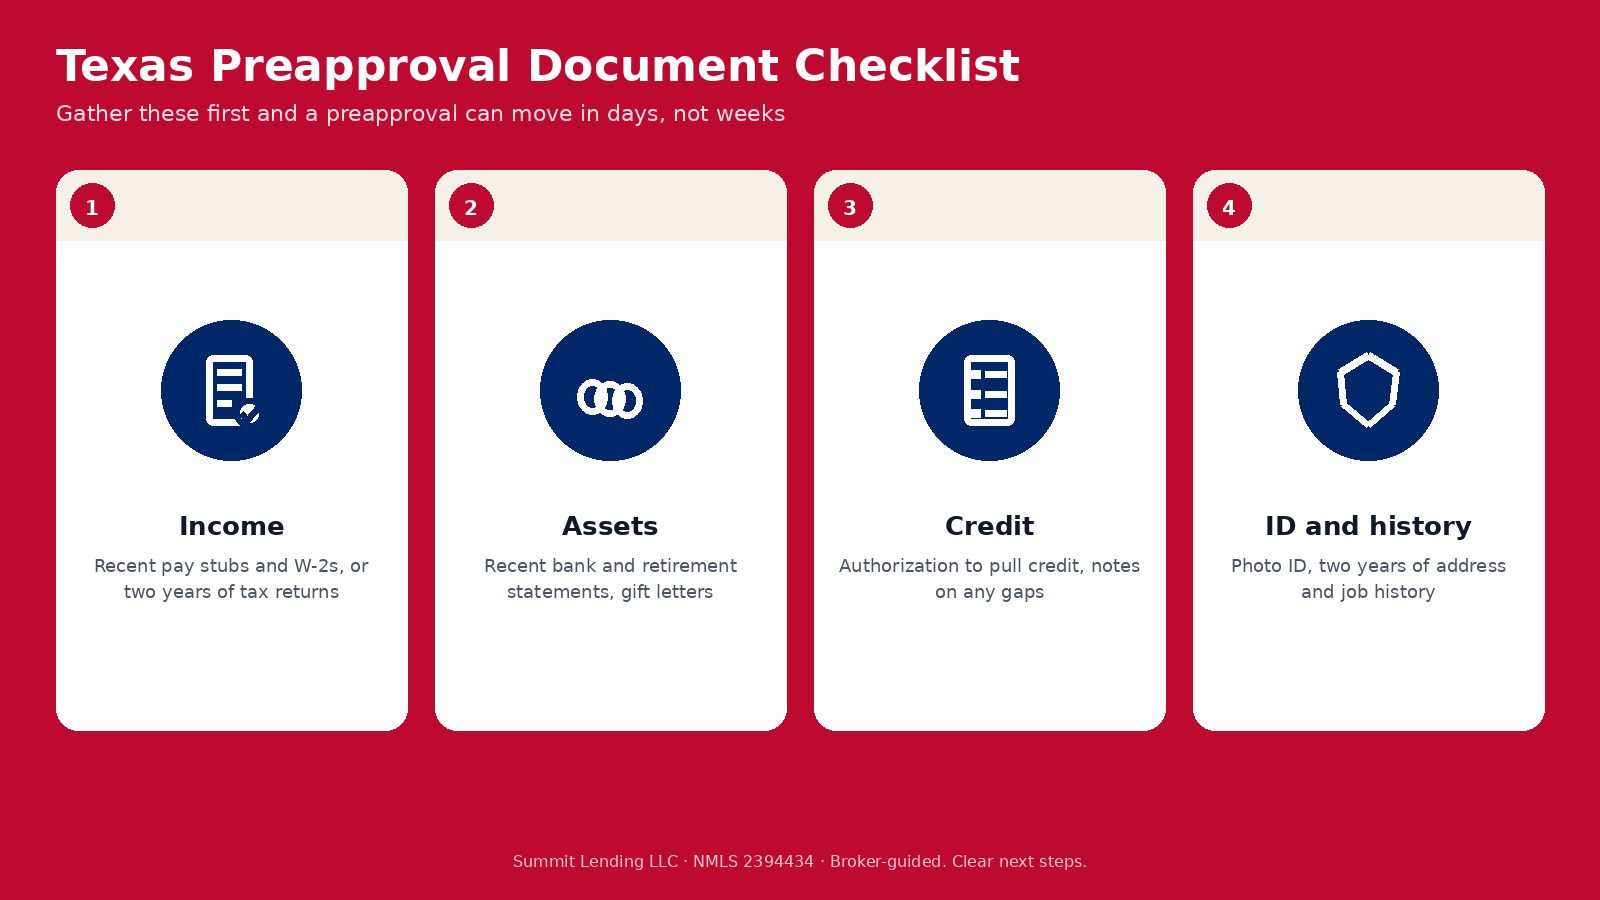
- Income. Recent pay stubs and W-2s. Self-employed and commission borrowers should expect to provide tax returns, often for two years.
- Assets. Recent bank statements and any retirement or investment statements you will use for the down payment, closing costs, or reserves. If family is helping, a signed gift letter.
- Credit. Your authorization to pull credit, plus a short note for anything unusual, like a past late payment or a gap in work.
- Identification and history. A photo ID and two years of address and employment history.
- Program extras. For VA loans, your Certificate of Eligibility (VA eligibility). For TDHCA or TSAHC assistance, the program's homebuyer education certificate.
What lenders actually check
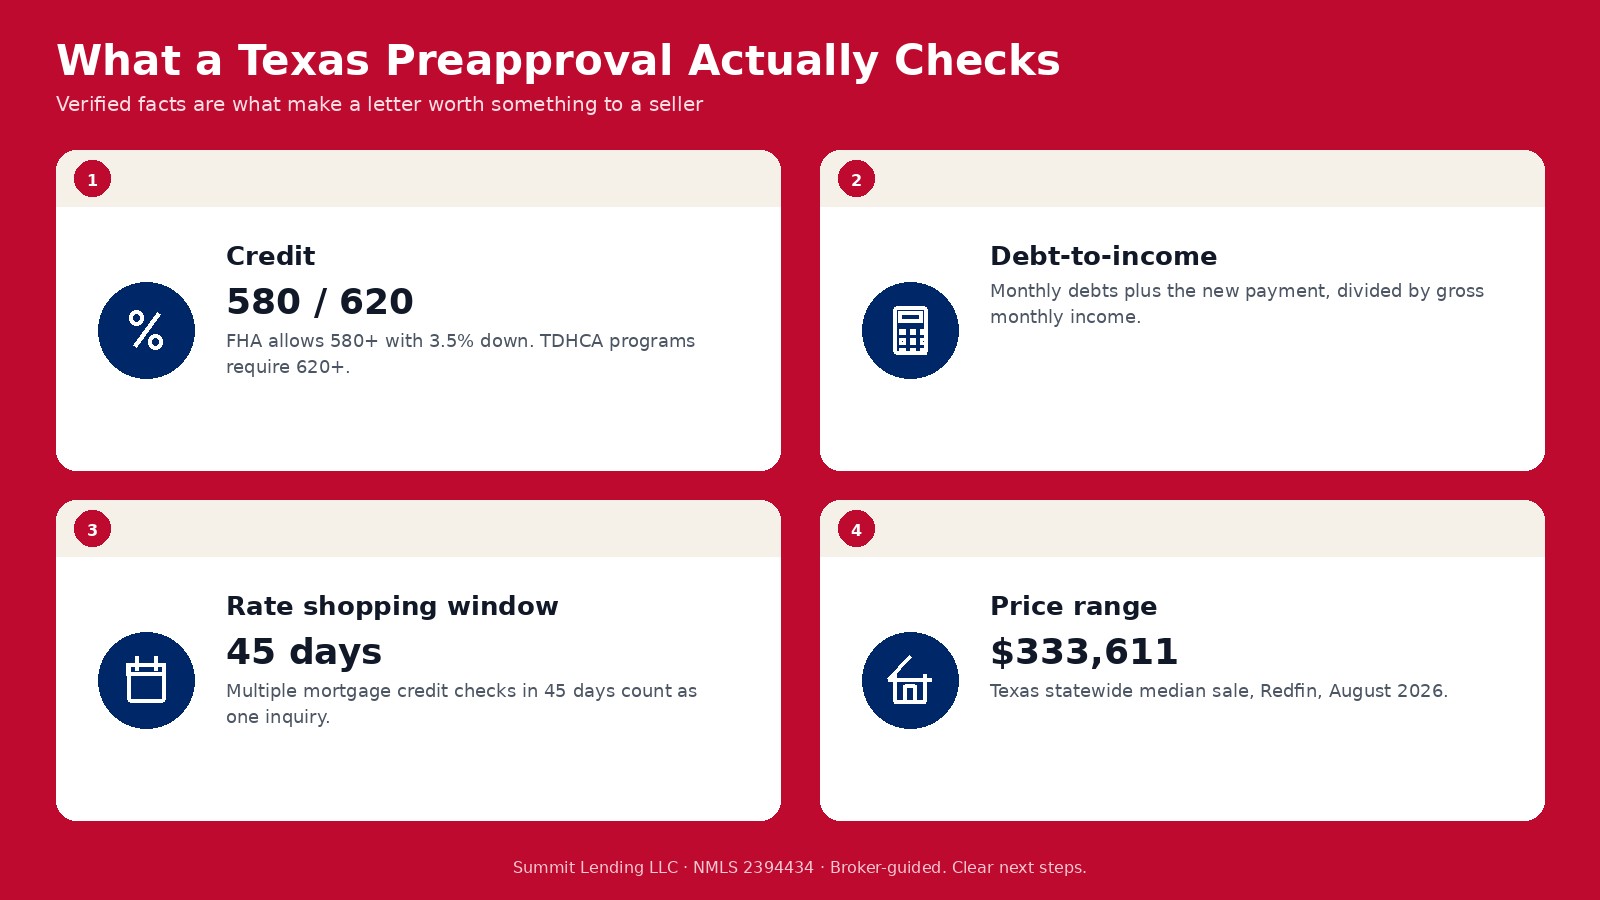
- Credit. Your score affects both approval and price. FHA allows 3.5% down with a score of 580 or higher (HUD FHA overview), and TDHCA's homebuyer programs require a minimum score of 620 (TDHCA program chart). Several mortgage credit checks within a 45-day window generally count as one inquiry for scoring, so comparing lenders will not hurt you more than once (CFPB on credit checks).
- Debt-to-income ratio. Your monthly debts, including the new payment, divided by your gross monthly income (CFPB on DTI). In Texas, a high property tax bill can raise the housing payment noticeably, so we use a realistic tax estimate for the areas you are shopping.
- Down payment and reserves. We confirm the money and where it came from.
- Program and limits. The 2026 conforming loan limit is $832,750 for a one-unit home in every Texas county (FHFA). FHA limits vary by county, with $541,287 in Harris and Fort Bend counties (HUD lookup).
Texas contract details that tie to your preapproval
Most Texas resale purchases use forms promulgated by the Texas Real Estate Commission. When any part of the price is financed by a third party, the contract usually includes TREC's Third Party Financing Addendum, Form 40-11 (TREC). That addendum describes the loan you are seeking and sets a period for you to obtain buyer approval for it, along with how you can end the contract if you cannot. A solid preapproval lets you and your agent choose that timeline with confidence, rather than guessing. Ask us before you sign how many days we need for your file.
Two other Texas details are useful to know early. Title insurance premiums are set by the Texas Department of Insurance, so the base rate for a given price is the same with any title company (TDI). And once you own the home as your residence, you can file for the homestead exemption, which for school district taxes is $140,000 after 2025's Proposition 13 (Ballotpedia; Texas Comptroller). We factor both into the cash to close and payment we show you.
Loan options we preapprove Texas buyers for
- Conventional. As little as 3% down for qualified buyers on a one-unit primary home (Fannie Mae eligibility matrix), with PMI below 20% down (CFPB on PMI).
- FHA. 3.5% down with a 580 or higher score, plus a 1.75% upfront premium and an annual premium (HUD Mortgagee Letter 2023-05).
- VA. No down payment and no monthly mortgage insurance for eligible borrowers (VA purchase loans), with a funding fee unless exempt (VA funding fee). Texas has a large military community around Killeen and El Paso.
- USDA. No down payment in eligible rural areas for households under the income limits (USDA). Check the address on the USDA eligibility map.
- Jumbo. Above $832,750, which comes up in parts of Austin, Dallas, and Houston.
If you plan to use down payment help, tell us at the start. TDHCA's My First Texas Home and My Choice Texas Home offer up to 5% assistance through participating lenders (TDHCA), and TSAHC offers up to 5% through Homes for Texas Heroes and Home Sweet Texas (TSAHC programs). Income and price limits apply. Our Texas first-time home buyer guide has the details.
How preapproval works with Summit
- Short conversation. Goals, timeline, price range, and where in Texas you are shopping.
- Application and documents. You upload the items above through a secure link.
- Credit and review. We pull credit and review income and assets with more than one lender in mind.
- Letter. You get a preapproval letter for your offers. We can tailor the amount for each offer so you do not show more than you need to.
- Under contract. After you apply for a specific property, your Loan Estimate arrives within three business days (CFPB on Loan Estimates), and your Closing Disclosure comes at least three business days before signing (CFPB on Closing Disclosures).
Keep your preapproval strong
- Do not open new credit or finance a car or furniture before closing.
- Document large deposits, and tell us before you move money between accounts.
- Tell us right away if your job or income changes.
- Expect to send updated pay stubs and statements if your search runs more than a few weeks.
- Get insurance quotes early, especially in coastal and flood-prone parts of the state, since premiums affect your debt-to-income ratio.
Where we preapprove Texas buyers
Major cities: Houston, Dallas, Austin, Fort Worth, El Paso, Plano, Corpus Christi, and Lubbock. Houston area: Katy, Sugar Land, Harris County, Fort Bend County, and Montgomery County. Dallas and Fort Worth area: Dallas County, Tarrant County, Collin County, and Denton County. Central Texas: Travis County, Williamson County, Bexar County, Waco, Killeen, and College Station. West Texas: Amarillo, and El Paso County.
Related pages
See the Texas mortgage overview, Texas purchase loans, Texas refinancing, Texas construction loans, and Texas reverse mortgages. We also preapprove buyers in Utah, Idaho, and Wyoming.
Sources
- Redfin, Texas housing market
- Redfin, Houston housing market
- Freddie Mac PMMS, Oct 1, 2026 release
- Freddie Mac Primary Mortgage Market Survey
- CFPB, prequalification vs. preapproval
- VA home loan eligibility
- HUD, Let FHA loans help you
- TDHCA homebuyer program chart (PDF)
- CFPB, when a lender checks your credit
- CFPB, debt-to-income ratio
- FHFA, 2026 conforming loan limits
- HUD FHA mortgage limits lookup
- TREC, Third Party Financing Addendum (Form 40-11)
- Texas Department of Insurance, title insurance
- Ballotpedia, Texas Proposition 13 (2025)
- Texas Comptroller, property tax exemptions
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- HUD Mortgagee Letter 2023-05, FHA annual MIP (PDF)
- VA purchase loan
- VA funding fee and closing costs
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- TSAHC, loans and down payment assistance
- CFPB, What is a Loan Estimate?
- CFPB, What is a Closing Disclosure?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.