Holbrook 86025 Mortgage Calculator
Rate History
Are you a first time Home buyer?
Our First Time Home Buyer Assistance Program is just what you need.Holbrook 86025 mortgage calculator: estimate a payment in the Navajo County seat
ZIP code 86025 is Holbrook, the county seat of Navajo County in northeastern Arizona, on I-40 and historic Route 66. It is a small town with mostly older single-family homes and rural lots, and the south entrance to Petrified Forest National Park is about 19 miles away on Highway 180 (National Park Service). This page gives you current 86025 numbers, a worked example, and the Arizona tax and down payment rules that shape a real estimate. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed in Arizona. We compare loans from multiple wholesale lenders, so you can turn this estimate into an actual quote.
When you are ready, start a mortgage preapproval or read about home purchase loans.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
86025 numbers to start with
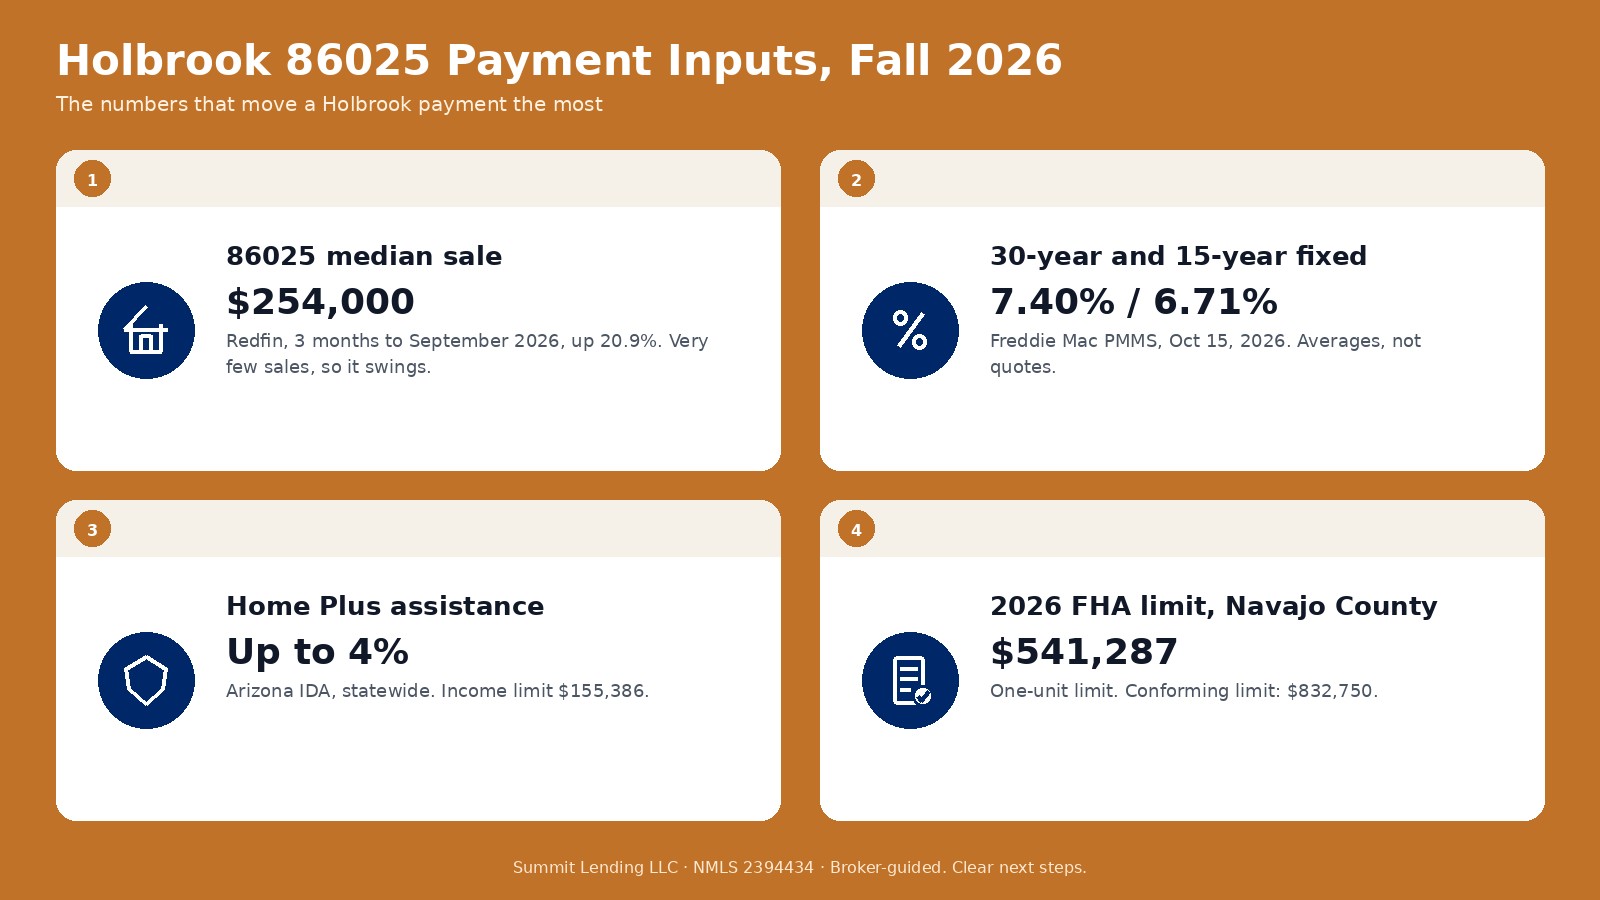
Redfin put the 86025 median sale price at about $254,000 for the three months ending September 2026, up 20.9% from the same period a year earlier. Homes took a median of about 71 days to sell, compared with 158 days a year earlier (Redfin 86025 data). Over the last 12 months, Redfin says the average home sold for about 4% below list price.
Read those figures with care. Holbrook is a small market, and Redfin counted only 6 homes sold in September, compared with 5 a year earlier. With that few sales, one large or small home can move the median by tens of thousands of dollars. Use a price that matches the actual homes you are looking at, and lean on recent comparable sales your agent pulls for the specific street or area.
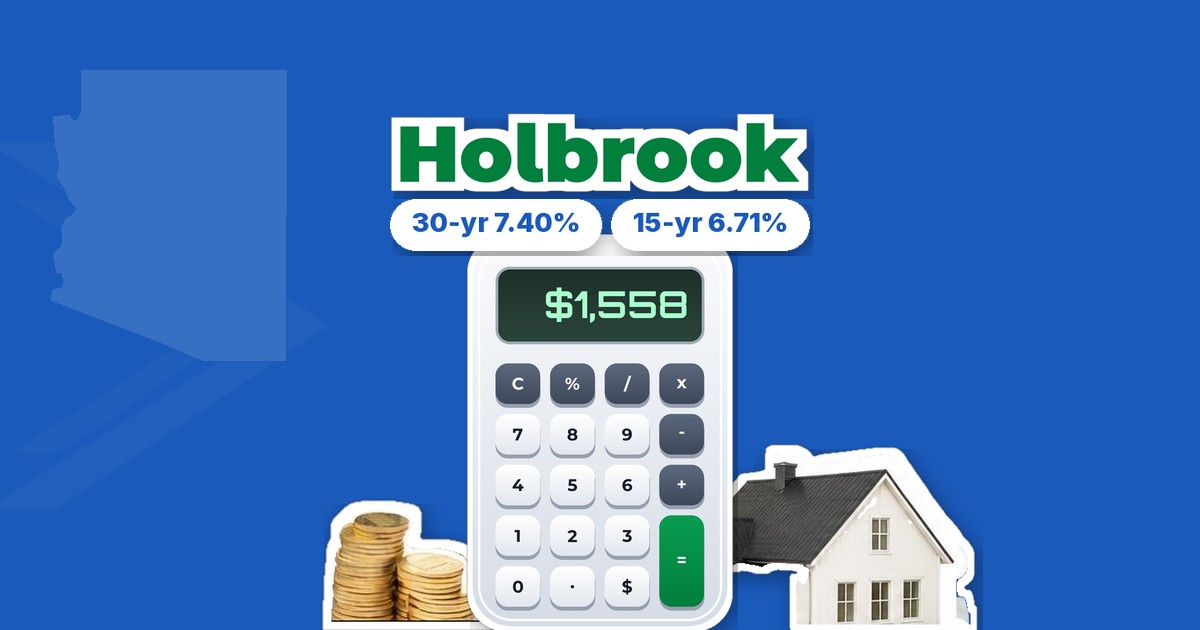
Rates set the base of every estimate. Freddie Mac's weekly survey put the average 30-year fixed rate at 7.40% as of October 15, 2026, unchanged from the week before and up from 6.27% a year ago. The 15-year average was 6.71%, down slightly from 6.73% a week earlier (Freddie Mac PMMS, Oct 15, 2026; weekly history in the PMMS archive and on FRED). Those are national averages for borrowers with strong credit and roughly 20% down, not Holbrook quotes. Freddie Mac publishes a new reading every Thursday, so if you are running numbers a few weeks from now, update the rate first.
What goes into an 86025 payment
- Principal and interest. The calculator's core result.
- Property tax. Based on Arizona's limited property value system, explained below.
- Homeowners insurance. Redfin's climate data rates about 53% of 86025 properties as having some wildfire risk over the next 30 years and about 3% at severe flood risk, so get a real quote early, especially for homes on larger lots outside town.
- Mortgage insurance. PMI on conventional loans with less than 20% down, or FHA's annual premium.
- Utilities and upkeep. Not part of the mortgage payment, but on an older home or a rural lot with a well or septic system, budget for them before you decide how much payment you are comfortable with.
How Arizona property tax works
Arizona does not tax a home on what you paid for it. Each property has a full cash value and a limited property value, and most taxes are figured on the limited value. Since 2015, under Proposition 117, the limited value can rise by no more than 5% a year and can never exceed the full cash value (Arizona Department of Revenue). A home you live in as your primary residence is Class 3 property, assessed at 10% of its limited value, and owner-occupied homes also receive a homeowner rebate on part of the school district tax, shown as a line on the bill (Arizona Property Taxation). The Arizona Constitution also caps the primary tax levied on residential property at 1% of its limited value, although voter-approved bonds and overrides and many special district levies are outside that cap (Arizona Constitution, Article 9, Section 18).
What this means for your estimate: the seller's bill is usually a good guide, but it is not guaranteed. If the home was a rental, it may have been taxed in a different class without the owner rebate, and your bill could drop after you file it as a primary residence. If values in the area have risen quickly, the limited value may still be catching up, so expect modest increases of up to 5% a year in the taxable value even if the price you paid was much higher.
Worked example: a $250,000 home in 86025
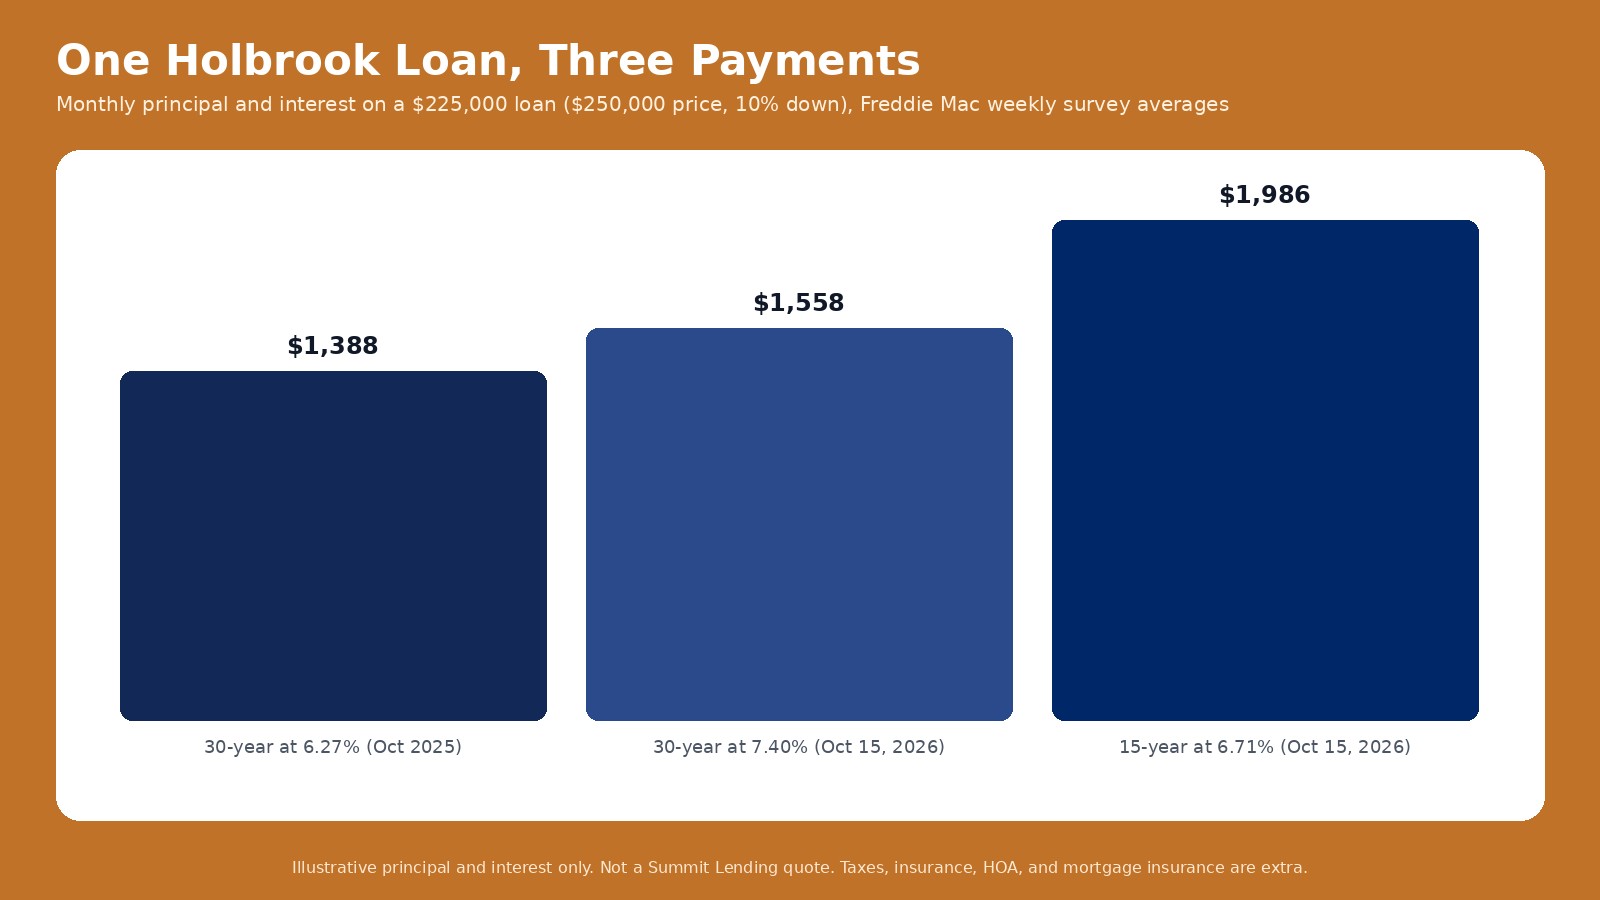
Take a $250,000 home with 10% down. The loan is $225,000. At 7.40%, principal and interest on a 30-year fixed is about $1,558 a month. At last year's 6.27%, it would have been about $1,388, so the rate change alone adds about $170 a month.
A 15-year fixed at 6.71% raises principal and interest to about $1,986, but total interest falls to about $132,491, compared with about $335,828 over 30 years at 7.40%. Then add tax, insurance, and any mortgage insurance. At Holbrook prices, the down payment and closing costs are often a bigger hurdle than the monthly payment, which is where Home Plus (below) can help.
How the loan type changes your Arizona result
Most online calculators assume a conventional loan with a fixed rate, which can make the number look better or worse than what you would actually get. Here is how the same $250,000 Arizona home changes by program, using the 7.40% survey average as a stand-in rate. Your actual rate will differ by program and profile.
Conventional
Qualified buyers can put as little as 3% down on a one-unit primary home, which is $7,500 on $250,000 (Fannie Mae eligibility matrix). Below 20% down you pay private mortgage insurance, and you can ask to cancel it once the balance reaches 80% of the original value (CFPB on PMI). PMI is priced by credit score and down payment, so add it as a separate line in the calculator rather than guessing.
FHA
FHA requires 3.5% down with a 580 or higher score (HUD FHA overview). It also adds two insurance costs a basic calculator often skips: an upfront premium of 1.75% that is usually financed into the loan, and an annual premium paid monthly. For a base loan of $726,200 or less with more than 95% loan-to-value, the annual rate is 0.55% (HUD Mortgagee Letter 2023-05). On $250,000 with 3.5% down, the base loan is $241,250, the upfront premium adds $4,222, and principal and interest on $245,472 is about $1,700 at 7.40%. The monthly premium adds roughly $111, for about $1,810 before taxes and insurance. The 2026 FHA one-unit limit in Navajo County is $541,287, the national floor, so this price fits with plenty of room.
VA
Eligible veterans and service members can buy with no down payment and no monthly mortgage insurance (VA purchase loans). A one-time funding fee applies unless you are exempt, and for first use with less than 5% down it is 2.15% of the loan (VA funding fee). Financing that fee on $250,000 brings the loan to about $255,375, with principal and interest near $1,768 at 7.40%.
USDA
USDA guaranteed loans allow no down payment in eligible rural areas for households under the income limits (USDA guaranteed loans). Holbrook is a small town, and USDA eligibility is set by address, so check the map before you rule it in or out. Check an address on the USDA eligibility map before you count on it.
2026 loan limits in Navajo County
The 2026 conforming loan limit is $832,750 for a one-unit home in every Arizona county (FHFA announcement, FHFA county file). The FHA one-unit limit in Navajo County is $541,287, the national floor (HUD announcement, HUD lookup). With prices this far below both limits, FHA, VA, USDA where eligible, and conventional loans all fit most of the market.
Down payment help in Arizona
The Arizona Industrial Development Authority's Home Plus program is available statewide, in every county, city, and ZIP code. It offers up to 4% of assistance for down payment and closing costs, paired with a Home Plus first mortgage. Household income cannot exceed $155,386 (as of April 6, 2026), and one borrower has to complete a homebuyer education course before closing. The assistance is a no-interest, no-payment second mortgage that is forgiven after 60 months, but it has to be repaid if you sell or refinance within those five years (Arizona IDA Home Plus). The interest rate on a Home Plus first mortgage can be slightly higher than a market rate, so ask your lender to compare total payments with and without it.
Arizona IDA's separate Arizona Is Home program is not an option for the rest of 2026. The authority says its 2026 funds are exhausted and the program was retired for the remainder of the year as of October 6, 2026 (Arizona IDA lender information).
Buying in a small rural market
A few things come up more often in Holbrook than in a big metro, and it helps to plan for them before you make an offer.
- Appraisals with few comparable sales. With only a handful of sales a month, an appraiser may have to reach further back in time or further out in distance for comparables. Leave some room in your timeline, and talk to us before you agree to cover an appraisal gap.
- Wells, septic, and land. Homes outside town may have a private well or septic system, which can mean extra inspections, and larger parcels can affect which loan programs fit.
- Manufactured homes. Financing depends on how the home is set up. Lenders generally want it on a permanent foundation and titled as real property, so ask us early if you are looking at one.
- Tribal land. Parts of Navajo County are on the Navajo Nation and the Hopi Reservation, where financing works differently than it does in town. If a property is on or near tribal land, tell your loan officer up front.
From a calculator estimate to a real number
- Run a few scenarios here. Try two prices, two down payments, and both a 30-year and 15-year term so you know your range.
- Get preapproved. A preapproval means a lender checked your credit, income, and assets. The CFPB points out that lenders use the terms prequalification and preapproval differently, so ask what was verified (CFPB comparison). Several mortgage credit checks within 45 days count as one inquiry for most scoring models, so shopping does not hurt your score more than once (CFPB on credit checks).
- Compare Loan Estimates. Lenders must send a Loan Estimate within three business days of your application, and the standard format makes side-by-side comparison easy (CFPB on Loan Estimates).
- Watch your debt-to-income ratio. Lenders compare your monthly debts, including the new payment, to gross monthly income (CFPB on DTI). A payment that fits your budget can still be too high for a program limit, or the reverse.
- Check the final numbers. Your Closing Disclosure arrives at least three business days before closing. Compare it to your Loan Estimate line by line (CFPB on Closing Disclosures).
Calculators for nearby ZIP codes
Northeastern Arizona: 86502 (Chambers), 86503 (Chinle), and 86504 (Fort Defiance). Northern Arizona: 86020 (Cameron), 86023 (Grand Canyon), 86024 (Happy Jack), 86021 (Colorado City), and 86022 (Fredonia). Phoenix and Tucson areas: 85281 (Tempe), and 85705 (Tucson).
Related pages
Already own a home? Compare refinance options. Building instead of buying? See construction loans. Homeowners 62 and older can read about reverse mortgages, and first-time buyers can start with our first-time home buyer guide. The main loan calculator page has calculators for every state we serve.
Sources
- Redfin, 86025 (Holbrook, AZ) housing market
- National Park Service, Petrified Forest directions
- Freddie Mac Primary Mortgage Market Survey, October 15, 2026
- Freddie Mac PMMS archive
- FRED, 30-Year Fixed Rate Mortgage Average
- Arizona Department of Revenue, Limited Property Value (PDF)
- Arizona Department of Revenue, Arizona Property Taxation (PDF)
- Arizona Constitution, Article 9, Section 18
- Arizona IDA, Home Plus down payment assistance
- Arizona IDA, Home Plus lender information
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- HUD, Let FHA loans help you
- HUD Mortgagee Letter 2023-05, FHA annual MIP (PDF)
- VA purchase loan
- VA funding fee and closing costs
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- FHFA, 2026 conforming loan limits
- FHFA 2026 county loan limit list
- HUD No. 25-145, 2026 FHA loan limits
- HUD FHA mortgage limits lookup
- CFPB, prequalification vs. preapproval
- CFPB, when a lender checks your credit
- CFPB, What is a Loan Estimate?
- CFPB, debt-to-income ratio
- CFPB, What is a Closing Disclosure?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.