Pulaski County Mortgage Calculator
Rate History
Are you a first time Home buyer?
Our First Time Home Buyer Assistance Program is just what you need.Pulaski County mortgage calculator: plan the whole payment
Pulaski County includes Little Rock, North Little Rock, and Jacksonville, with Little Rock Air Force Base nearby. It is one of the most affordable metro areas we serve, which makes the tax, insurance, and assistance lines a bigger share of the decision. This page gives you current Pulaski County numbers, a worked example near the local median, and the Arkansas tax and loan rules that belong in any honest estimate. Summit Lending LLC (NMLS 2394434) is a mortgage broker based in Garland, Utah. We compare loans from multiple wholesale lenders and can turn your calculator result into a real quote for a home in Pulaski County.
Ready to shop? Start with mortgage preapproval, or read about home purchase loans.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
Pulaski County numbers to start with
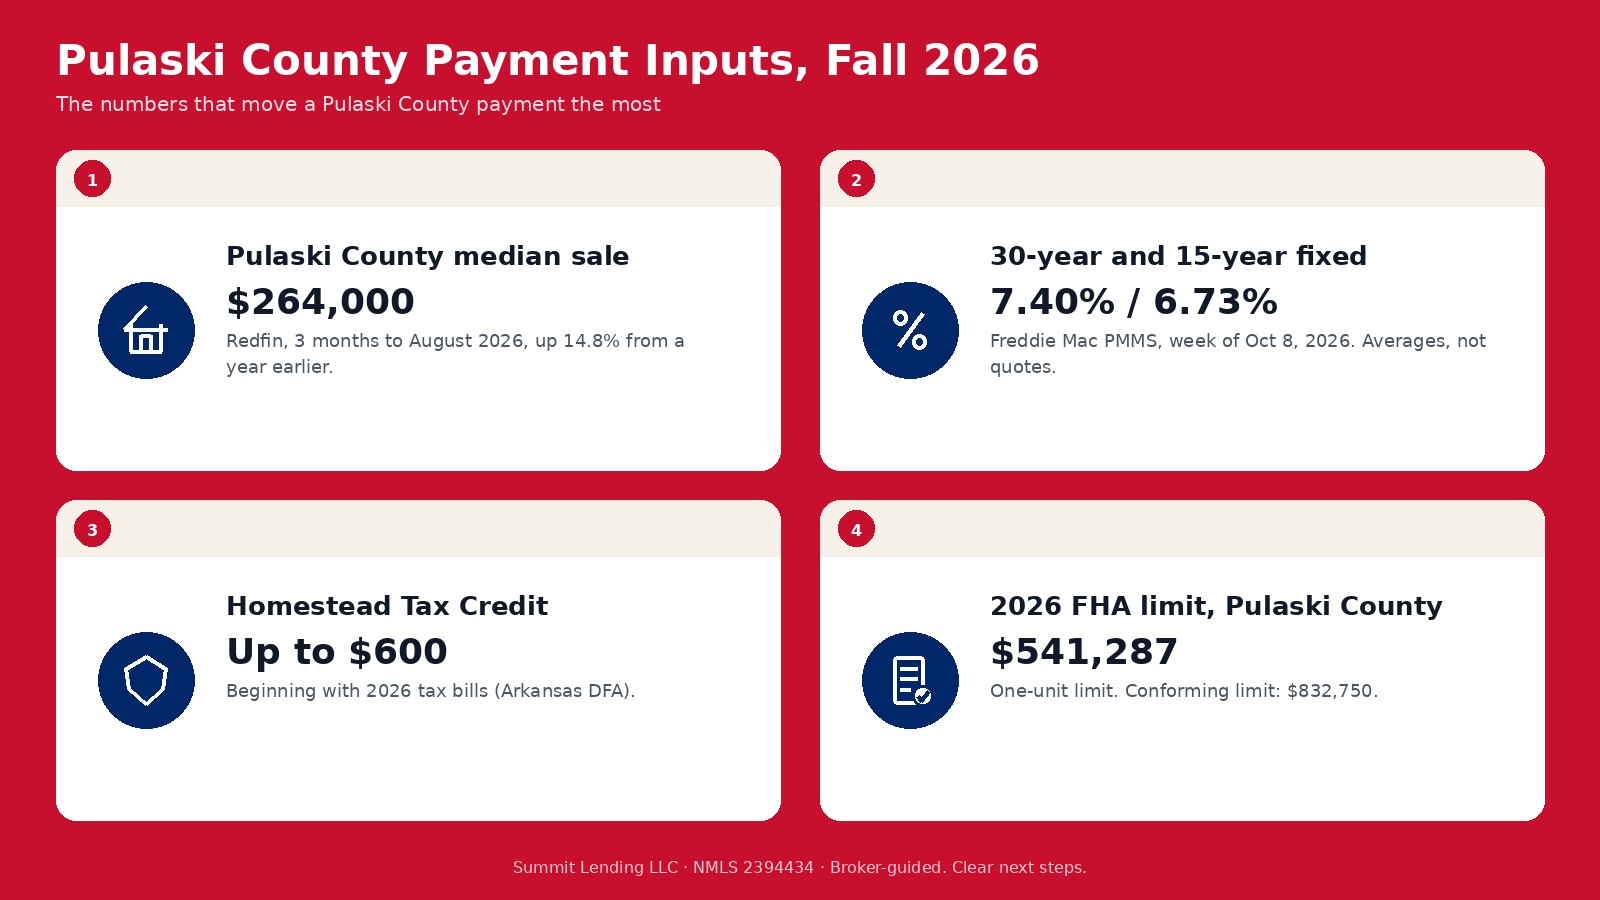
Redfin put the Pulaski County median sale price at about $264,000 for the three months ending August 2026, up 14.8% from the same period a year earlier. About 422 homes sold in August, compared with 474 a year earlier, and homes took a median of about 52 days to sell, versus 55 days last year, with an average sale-to-list ratio near 97.8% (Redfin Pulaski County data). Prices rose sharply over the past year, though the number of sales fell, so a smaller mix of sales may be pushing the median up.
For city numbers, see the Little Rock mortgage calculator and North Little Rock. Military buyers should compare a VA loan side by side with FHA and conventional options.
Rates set the base of every estimate. Freddie Mac's weekly survey put the average 30-year fixed rate at 7.40% for the week of October 8, 2026, up from 7.28% a week earlier and 6.30% a year ago. It was the seventh weekly increase in a row and the highest reading since November 2023. The 15-year average was 6.73% (AP report on the Oct 8 survey; weekly history in the PMMS archive and on FRED). Those are national averages for borrowers with strong credit and roughly 20% down, not Pulaski County quotes. Freddie Mac publishes a new reading every Thursday (PMMS page), so if you are running numbers a few weeks from now, update the rate first.
What goes into a Pulaski County payment
- Principal and interest. The calculator's core result, set by price, down payment, rate, and term.
- Property tax. Arkansas assesses property at 20% of market value and applies local millage. A homestead credit of up to $600 applies starting with 2026 bills.
- Homeowners insurance. Ask about wind and hail coverage, and check flood zone status near creeks and rivers.
- Mortgage insurance. PMI on conventional loans with less than 20% down, or FHA's annual premium.
- HOA dues. Less common in older neighborhoods, but many newer subdivisions have them.
Arkansas property tax relief
Arkansas gives owner-occupied homes a homestead property tax credit. The Department of Finance and Administration says the credit is up to $500 and is increasing to up to $600 beginning with 2026 tax bills. Amendment 79 also limits how much the assessed value of a homestead can rise, to 5% a year, and homeowners who are 65 or older or disabled can have their assessed value frozen (Arkansas DFA property tax relief). You claim the credit with the Pulaski County Assessor once the home is your primary residence.
For the calculator, start with the seller's latest bill and subtract nothing until you know whether the seller already had the credit or a freeze. A home owned for many years by a senior can show a frozen bill that resets when you buy.
Worked example: a $264,000 home in Pulaski County
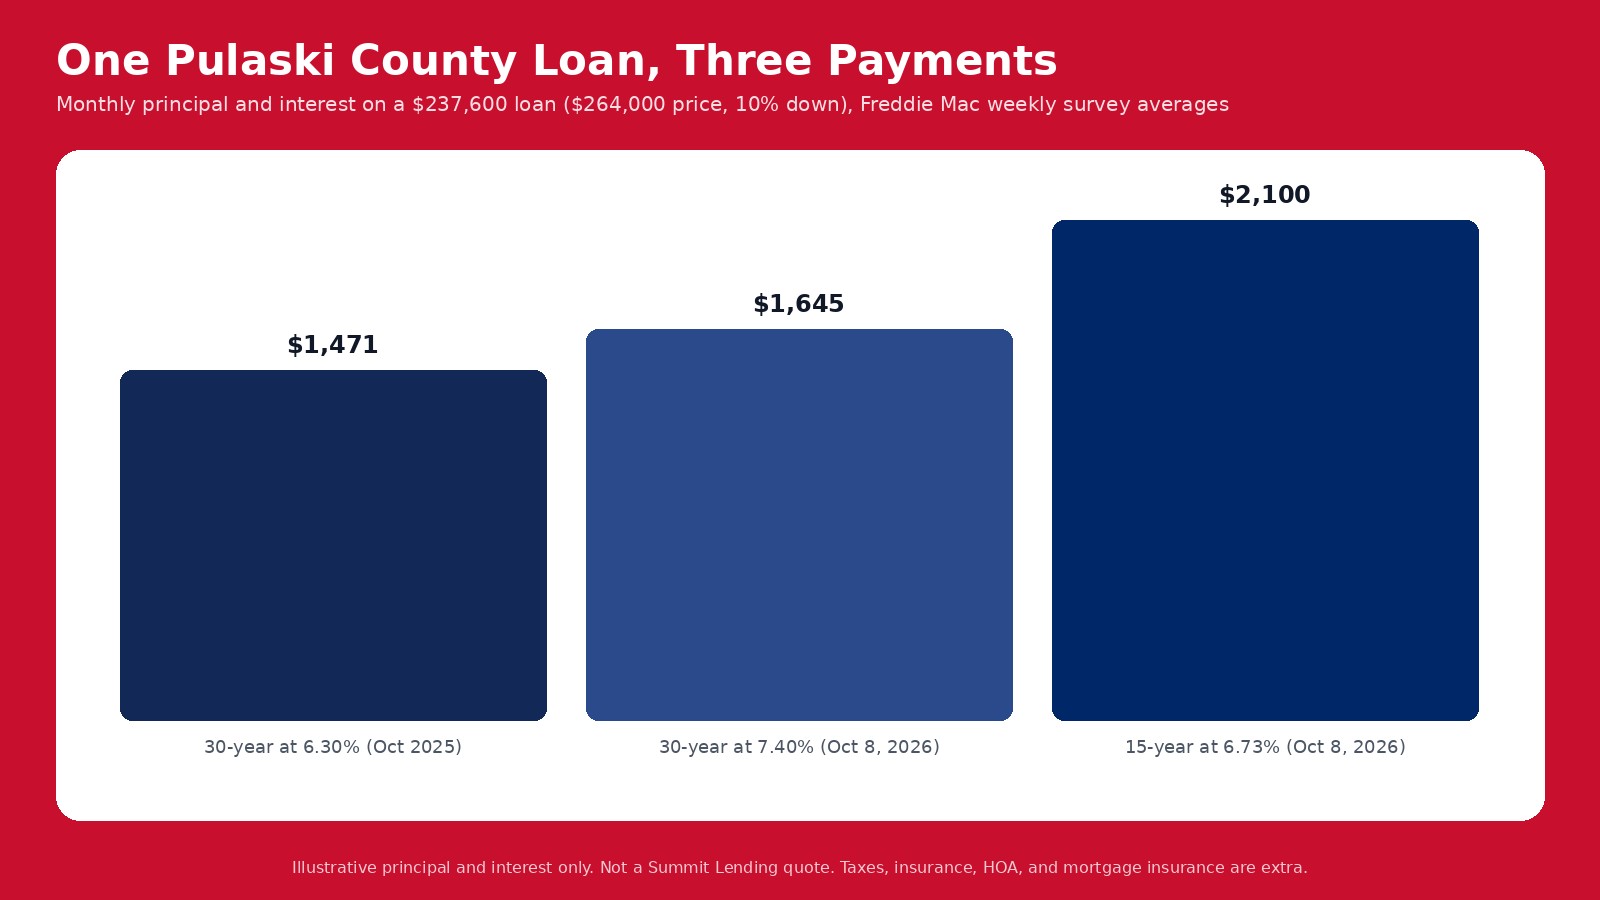
Take a $264,000 home near the Pulaski County median with 10% down. The loan is $237,600. At 7.40%, principal and interest on a 30-year fixed is about $1,645 a month. At last year's 6.30%, the same loan would have been about $1,471, so the rate change alone adds about $174 a month.
A 15-year fixed at 6.73% raises the payment to about $2,100, while total interest drops to about $140,384, compared with about $354,634 over 30 years at 7.40%. Add tax, insurance, PMI, and HOA dues for the full number. If it is more than you want to carry, compare a lower price point, a larger down payment, a temporary or permanent rate buydown paid by the seller, or ADFA down payment assistance.
How the loan type changes your Pulaski County result
Most online calculators assume a conventional loan with a fixed rate, which can make the number look better or worse than what you would actually get. Here is how the same $264,000 Pulaski County home changes by program, using the 7.40% survey average as a stand-in rate. Your actual rate will differ by program and profile.
Conventional
Qualified buyers can put as little as 3% down on a one-unit primary home, which is $7,920 on $264,000 (Fannie Mae eligibility matrix). Below 20% down you pay private mortgage insurance, and you can ask to cancel it once the balance reaches 80% of the original value (CFPB on PMI). PMI is priced by credit score and down payment, so add it as a separate line in the calculator rather than guessing.
FHA
FHA requires 3.5% down with a 580 or higher score (HUD FHA overview). It also adds two insurance costs a basic calculator often skips: an upfront premium of 1.75% that is usually financed into the loan, and an annual premium paid monthly. For a base loan of $726,200 or less with more than 95% loan-to-value, the annual rate is 0.55% (HUD Mortgagee Letter 2023-05). On $264,000 with 3.5% down, the base loan is $254,760, the upfront premium adds $4,458, and principal and interest on $259,218 is about $1,795 at 7.40%. The monthly premium adds roughly $117, for about $1,912 before taxes and insurance. The 2026 FHA one-unit limit in Pulaski County is $541,287, so this price fits with plenty of room.
VA
Eligible veterans and service members can buy with no down payment and no monthly mortgage insurance (VA purchase loans). A one-time funding fee applies unless you are exempt, and for first use with less than 5% down it is 2.15% of the loan (VA funding fee). Financing that fee on $264,000 brings the loan to about $269,676, with principal and interest near $1,867 at 7.40%.
USDA
USDA guaranteed loans allow no down payment in eligible rural areas for households under the income limits (USDA guaranteed loans). Some areas at the edges of the county can be eligible, but most of the urban area is not. Check an address on the USDA eligibility map before you count on it.
2026 loan limits in Pulaski County
The 2026 conforming loan limit is $832,750 for a one-unit home in all 75 Arkansas counties (FHFA announcement, FHFA county file). The FHA one-unit limit in Pulaski County is $541,287, the national floor (HUD announcement, HUD lookup).
ADFA programs and down payment help
The Arkansas Development Finance Authority (ADFA) offers home loans and down payment assistance through participating lenders. Its guidelines, revised in June 2026, describe these options (ADFA program guidelines):
- Move-Up. No first-time buyer requirement, a qualifying income limit of $142,000, and a minimum median credit score of 640 (ADFA Move-Up).
- Down payment assistance. From $1,000 up to $15,000 as a second mortgage repaid over 10 years at the same rate as the first mortgage. The maximum debt-to-income ratio is 45%, including the assistance payment (ADFA DPA).
- StartSmart. For first-time buyers (no ownership in the past three years), with a $500,000 purchase price limit.
Because ADFA assistance is repayable, add its monthly payment to the estimate. A $10,000 assistance loan over 10 years at 7.40% adds about $118 a month. See our first-time home buyer guide for more on how assistance fits with FHA and conventional loans.
From a calculator estimate to a real number
- Run a few scenarios here. Try two prices, two down payments, and both a 30-year and 15-year term so you know your range.
- Get preapproved. A preapproval means a lender checked your credit, income, and assets. The CFPB points out that lenders use the terms prequalification and preapproval differently, so ask what was verified (CFPB comparison). Several mortgage credit checks within 45 days count as one inquiry for most scoring models, so shopping does not hurt your score more than once (CFPB on credit checks).
- Compare Loan Estimates. Lenders must send a Loan Estimate within three business days of your application, and the standard format makes side-by-side comparison easy (CFPB on Loan Estimates).
- Watch your debt-to-income ratio. Lenders compare your monthly debts, including the new payment, to gross monthly income (CFPB on DTI). A payment that fits your budget can still be too high for a program limit, or the reverse.
- Check the final numbers. Your Closing Disclosure arrives at least three business days before closing. Compare it to your Loan Estimate line by line (CFPB on Closing Disclosures).
Calculators for nearby areas
Central Arkansas: Little Rock, North Little Rock, and Cabot. Elsewhere in Arkansas: Saline County, Faulkner County, Lonoke County, Benton County, and Washington County. Or use the statewide Arkansas mortgage calculator.
Related pages
Thinking about a refinance instead? See refinance options. Building? See construction loans. Homeowners 62 and older can read about reverse mortgages. Statewide, use the Arkansas mortgage calculator, and our main loan calculator page links to calculators for every state we serve.
Sources
- Redfin, Pulaski County, AR housing market
- Redfin, Arkansas housing market
- AP via WTOP, Freddie Mac rates for Oct 8, 2026
- Freddie Mac PMMS archive
- Freddie Mac Primary Mortgage Market Survey
- FRED, 30-Year Fixed Rate Mortgage Average
- Arkansas DFA, property tax relief
- Pulaski County Assessor
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- HUD, Let FHA loans help you
- HUD Mortgagee Letter 2023-05, FHA annual MIP (PDF)
- VA purchase loan
- VA funding fee and closing costs
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- FHFA, 2026 conforming loan limits
- FHFA 2026 county loan limit list
- HUD No. 25-145, 2026 FHA loan limits
- HUD FHA mortgage limits lookup
- ADFA single-family program guidelines, rev. June 2026 (PDF)
- ADFA Move-Up loan program
- ADFA down payment assistance program
- CFPB, prequalification vs. preapproval
- CFPB, when a lender checks your credit
- CFPB, What is a Loan Estimate?
- CFPB, debt-to-income ratio
- CFPB, What is a Closing Disclosure?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.