Coeur d'Alene Mortgage Calculator
Buying your first home?
3% down on conventional loans, 3.5% with FHA
We line up down payment assistance, credit prep and pre-approval for first-time buyers, so you know your payment and cash to close before you make an offer.
See first-time buyer optionsCoeur d'Alene mortgage calculator: plan the whole payment
Coeur d'Alene is the largest city in Kootenai County and the center of North Idaho, about 30 miles east of Spokane. Lake Coeur d'Alene, tourism, healthcare, and a steady flow of relocating buyers support the market, and lake and view homes push the top end well past the conforming limit. This page gives you current Coeur d'Alene numbers, a worked example near the local median, and the Idaho tax and loan rules that belong in any honest estimate. Summit Lending LLC (NMLS 2394434) is a mortgage broker based in Garland, Utah. We compare loans from multiple wholesale lenders and can turn your calculator result into a real quote for a home in Coeur d'Alene.
Ready to shop? Start a Coeur d'Alene preapproval, or read about Coeur d'Alene purchase loans.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
Coeur d'Alene numbers to start with
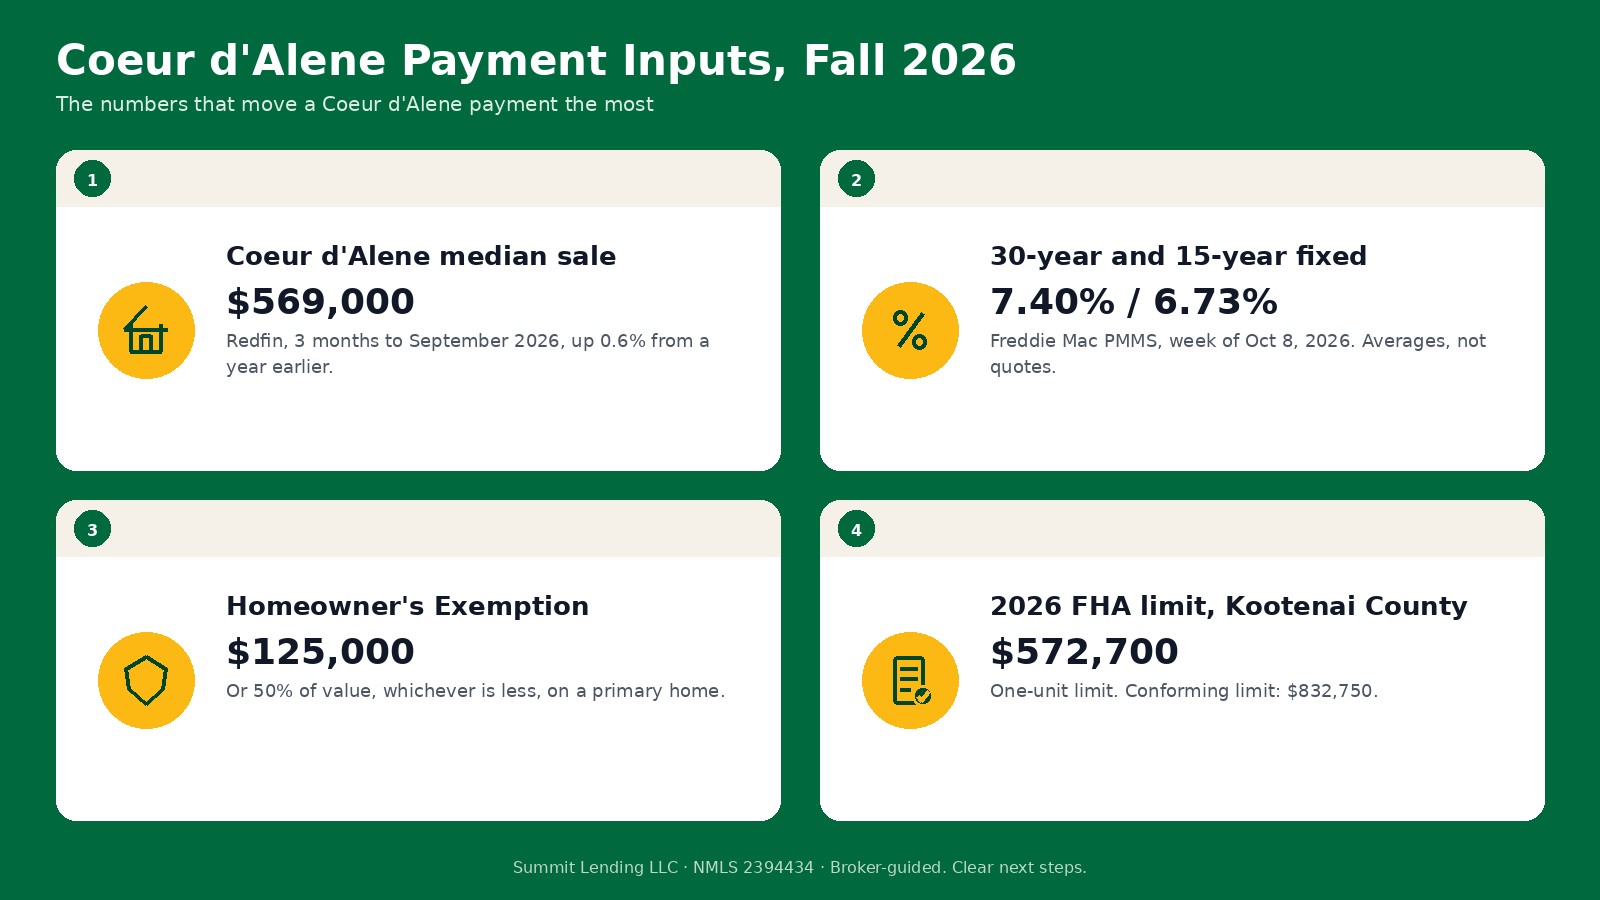
Redfin put the Coeur d'Alene median sale price at about $569,000 for the three months ending September 2026, up 0.6% from the same period a year earlier. About 285 homes sold in September, compared with 293 a year earlier, and homes took a median of about 29 days to sell, versus 36 days last year, with an average sale-to-list ratio near 97.9% (Redfin Coeur d'Alene data). Prices are about flat compared with a year ago, but homes are selling faster than last year, so well-priced homes still move quickly.
For the wider area, compare Kootenai County and nearby Post Falls, Rathdrum, Spirit Lake, and Athol. Many buyers here are relocating or buying a second home, and only a primary residence gets Idaho's homeowner's exemption.
Rates set the base of every estimate. Freddie Mac's weekly survey put the average 30-year fixed rate at 7.40% for the week of October 8, 2026, up from 7.28% a week earlier and 6.30% a year ago. It was the seventh weekly increase in a row and the highest reading since November 2023. The 15-year average was 6.73% (AP report on the Oct 8 survey; weekly history in the PMMS archive and on FRED). Those are national averages for borrowers with strong credit and roughly 20% down, not Coeur d'Alene quotes. Freddie Mac publishes a new reading every Thursday (PMMS page), so if you are running numbers a few weeks from now, update the rate first.
What goes into a Coeur d'Alene payment
- Principal and interest. The calculator's core result, set by price, down payment, rate, and term.
- Property tax. Based on value after the homeowner's exemption, multiplied by the levy for your taxing district.
- Homeowners insurance. Ask about wildfire exposure, snow load, and winter weather coverage, especially for homes near the forest edge or on the hillsides around the lake.
- Mortgage insurance. PMI on conventional loans with less than 20% down, or FHA's annual premium.
- HOA dues. Common in newer subdivisions and lake communities, less common in older neighborhoods near downtown.
Idaho's homeowner's exemption
Idaho exempts part of the value of an owner-occupied primary home from property tax. For 2026, the exemption is the lesser of $125,000 or 50% of the home's value, covering the home and up to one acre of land (Idaho State Tax Commission; Idaho Code 63-602G). On a $570,000 home, that means $125,000 of value is not taxed, so the taxable value is about $445,000. You apply with your county assessor after you buy, and it does not carry over from the seller automatically. The Kootenai County Assessor handles exemption applications and value notices for Kootenai County.
For the calculator, ask for the most recent tax bill on the address and check whether the seller had the exemption. If they did not, for example because the home was a rental, your bill could drop once yours is approved. If they did, the bill is a reasonable starting point. Second homes and vacation properties around the lake do not qualify for the exemption, so their tax bills run higher.
Worked example: a $570,000 home in Coeur d'Alene
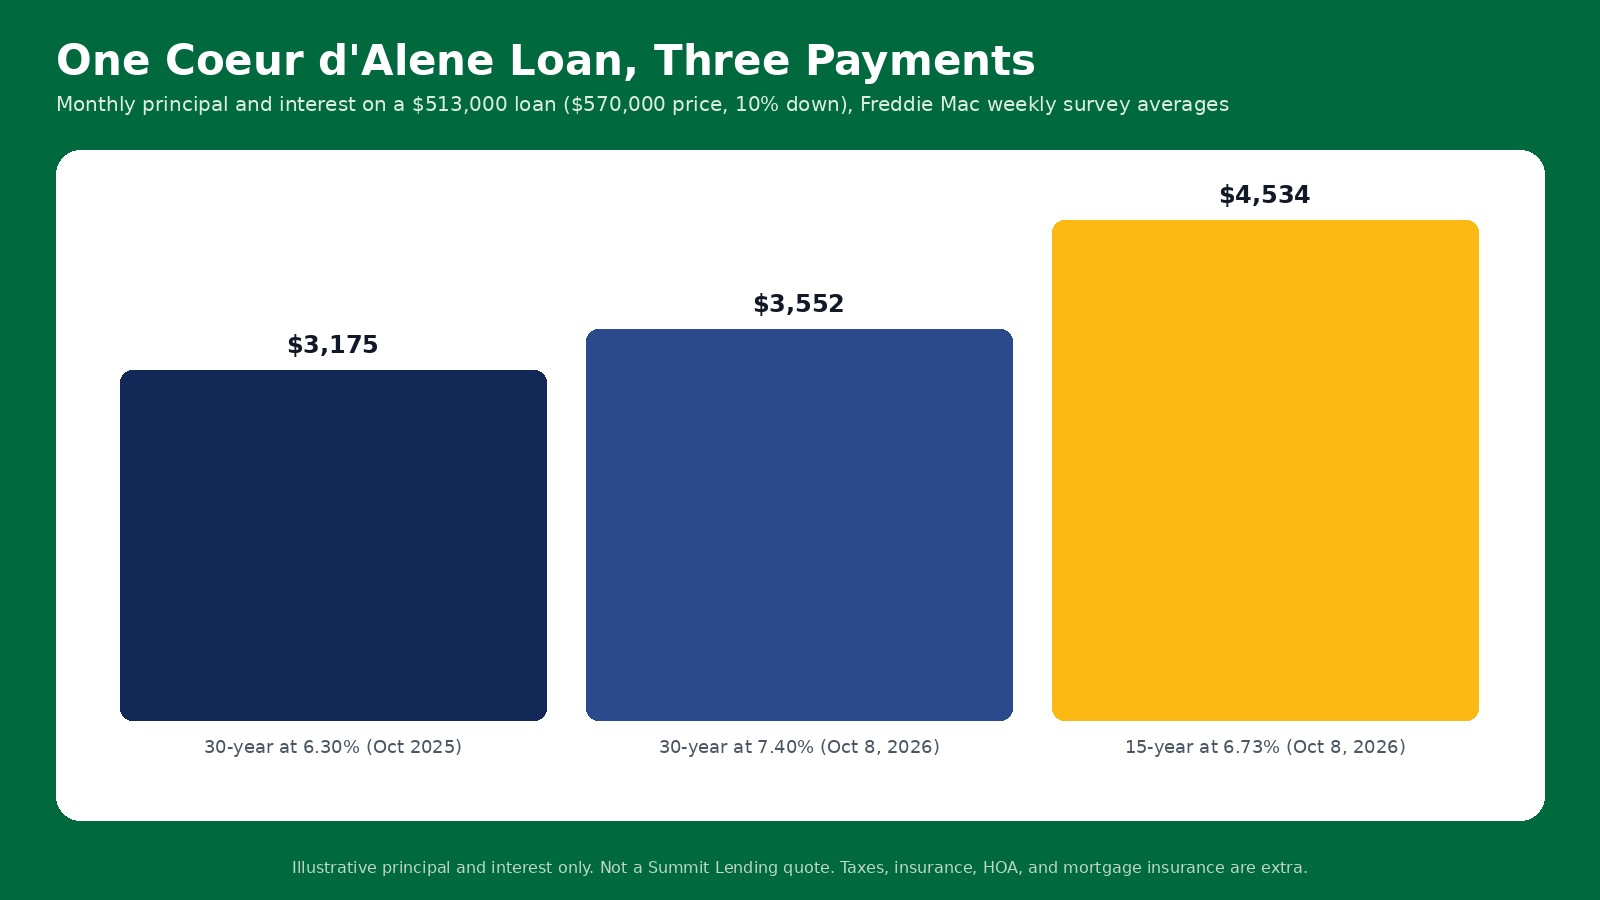
Take a $570,000 home near the Coeur d'Alene median with 10% down. The loan is $513,000. At 7.40%, principal and interest on a 30-year fixed is about $3,552 a month. At last year's 6.30%, the same loan would have been about $3,175, so the rate change alone adds about $377 a month.
A 15-year fixed at 6.73% raises the payment to about $4,534, while total interest drops to about $303,102, compared with about $765,687 over 30 years at 7.40%. Add tax, insurance, PMI, and HOA dues for the full number. If it is more than you want to carry, compare a lower price point, a larger down payment, a temporary or permanent rate buydown paid by the seller, or IHFA down payment assistance.
How the loan type changes your Coeur d'Alene result
Most online calculators assume a conventional loan with a fixed rate, which can make the number look better or worse than what you would actually get. Here is how the same $570,000 Coeur d'Alene home changes by program, using the 7.40% survey average as a stand-in rate. Your actual rate will differ by program and profile.
Conventional
Qualified buyers can put as little as 3% down on a one-unit primary home, which is $17,100 on $570,000 (Fannie Mae eligibility matrix). Below 20% down you pay private mortgage insurance, and you can ask to cancel it once the balance reaches 80% of the original value (CFPB on PMI). PMI is priced by credit score and down payment, so add it as a separate line in the calculator rather than guessing.
FHA
FHA requires 3.5% down with a 580 or higher score (HUD FHA overview). It also adds two insurance costs a basic calculator often skips: an upfront premium of 1.75% that is usually financed into the loan, and an annual premium paid monthly. For a base loan of $726,200 or less with more than 95% loan-to-value, the annual rate is 0.55% (HUD Mortgagee Letter 2023-05). On $570,000 with 3.5% down, the base loan is $550,050, the upfront premium adds $9,626, and principal and interest on $559,676 is about $3,875 at 7.40%. The monthly premium adds roughly $252, for about $4,127 before taxes and insurance. The 2026 FHA one-unit limit in Kootenai County is $572,700, so this price fits, but only just.
VA
Eligible veterans and service members can buy with no down payment and no monthly mortgage insurance (VA purchase loans). A one-time funding fee applies unless you are exempt, and for first use with less than 5% down it is 2.15% of the loan (VA funding fee). Financing that fee on $570,000 brings the loan to about $582,255, with principal and interest near $4,031 at 7.40%.
USDA
USDA guaranteed loans allow no down payment in eligible rural areas for households under the income limits (USDA guaranteed loans). Most of the city is not eligible, but rural parts of Kootenai County and some nearby towns can be. Check an address on the USDA eligibility map before you count on it.
2026 loan limits in Coeur d'Alene
The 2026 conforming loan limit for a one-unit home in Kootenai County is $832,750 (FHFA announcement, FHFA county file). The FHA one-unit limit is $572,700 for the Coeur d'Alene metro (HUD announcement, HUD lookup). Lakefront and view homes often exceed $832,750, which puts them in jumbo territory.
Down payment help in Idaho
Idaho Housing and Finance Association offers down payment and closing cost assistance of up to 8% of the sales price, repaid as a second loan, with a minimum of $500 of your own funds (IHFA down payment help). IHFA says a credit score of 620 or higher is typically beneficial for its loans (IHFA homebuyers). If you use it, add the second loan's payment, if any, to your estimate. Idaho also lets first-time buyers deduct deposits to a first-time homebuyer savings account from state taxable income (Idaho State Tax Commission). Our Coeur d'Alene first-time home buyer guide covers both in detail.
From a calculator estimate to a real number
- Run a few scenarios here. Try two prices, two down payments, and both a 30-year and 15-year term so you know your range.
- Get preapproved. A preapproval means a lender checked your credit, income, and assets. The CFPB points out that lenders use the terms prequalification and preapproval differently, so ask what was verified (CFPB comparison). Several mortgage credit checks within 45 days count as one inquiry for most scoring models, so shopping does not hurt your score more than once (CFPB on credit checks).
- Compare Loan Estimates. Lenders must send a Loan Estimate within three business days of your application, and the standard format makes side-by-side comparison easy (CFPB on Loan Estimates).
- Watch your debt-to-income ratio. Lenders compare your monthly debts, including the new payment, to gross monthly income (CFPB on DTI). A payment that fits your budget can still be too high for a program limit, or the reverse.
- Check the final numbers. Your Closing Disclosure arrives at least three business days before closing. Compare it to your Loan Estimate line by line (CFPB on Closing Disclosures).
Calculators for nearby areas
North Idaho: Kootenai County, Post Falls, Rathdrum, Spirit Lake, Athol, Harrison, and Worley. Elsewhere in Idaho: Sandpoint, Bonner County, Moscow, and Boise. Or use the statewide Idaho mortgage calculator.
Related pages
See the Coeur d'Alene mortgage overview, Coeur d'Alene refinancing, Coeur d'Alene construction loans, Coeur d'Alene reverse mortgages, and Coeur d'Alene commercial loans. Statewide, compare Idaho mortgage loans, Idaho purchase loans, Idaho refinancing, Idaho preapproval, Idaho mortgage calculator.
Sources
- Redfin, Coeur d'Alene, ID housing market
- Redfin, Idaho housing market
- AP via WTOP, Freddie Mac rates for Oct 8, 2026
- Freddie Mac PMMS archive
- Freddie Mac Primary Mortgage Market Survey
- FRED, 30-Year Fixed Rate Mortgage Average
- Idaho State Tax Commission, homeowner's exemption
- Idaho Code 63-602G, homestead exemption
- Kootenai County Assessor
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- HUD, Let FHA loans help you
- HUD Mortgagee Letter 2023-05, FHA annual MIP (PDF)
- VA purchase loan
- VA funding fee and closing costs
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- FHFA, 2026 conforming loan limits
- FHFA 2026 county loan limit list
- HUD No. 25-145, 2026 FHA loan limits
- HUD FHA mortgage limits lookup
- Idaho Housing and Finance Association, down payment help
- Idaho Housing and Finance Association, homebuyers
- Idaho State Tax Commission, first-time homebuyer savings account
- CFPB, prequalification vs. preapproval
- CFPB, when a lender checks your credit
- CFPB, What is a Loan Estimate?
- CFPB, debt-to-income ratio
- CFPB, What is a Closing Disclosure?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.
Have a construction project?
See our construction loan calculator and pricing options for one-time and two-time close loans.
Explore construction loans