Pocatello Mortgage Calculator
Buying your first home?
3% down on conventional loans, 3.5% with FHA
We line up down payment assistance, credit prep and pre-approval for first-time buyers, so you know your payment and cash to close before you make an offer.
See first-time buyer optionsPocatello mortgage calculator: plan the whole payment
Pocatello, in Bannock County, is home to Idaho State University and is one of the more affordable cities in Idaho. Older neighborhoods near campus and downtown sit alongside newer subdivisions on the edges of town, so the payment can vary a lot by home age and HOA. This page gives you current Pocatello numbers, a worked example near the local median, and the Idaho tax and loan rules that belong in any honest estimate. Summit Lending LLC (NMLS 2394434) is a mortgage broker based in Garland, Utah. We compare loans from multiple wholesale lenders and can turn your calculator result into a real quote for a home in Pocatello.
Ready to shop? Start a Pocatello preapproval, or read about Pocatello purchase loans.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
Pocatello numbers to start with
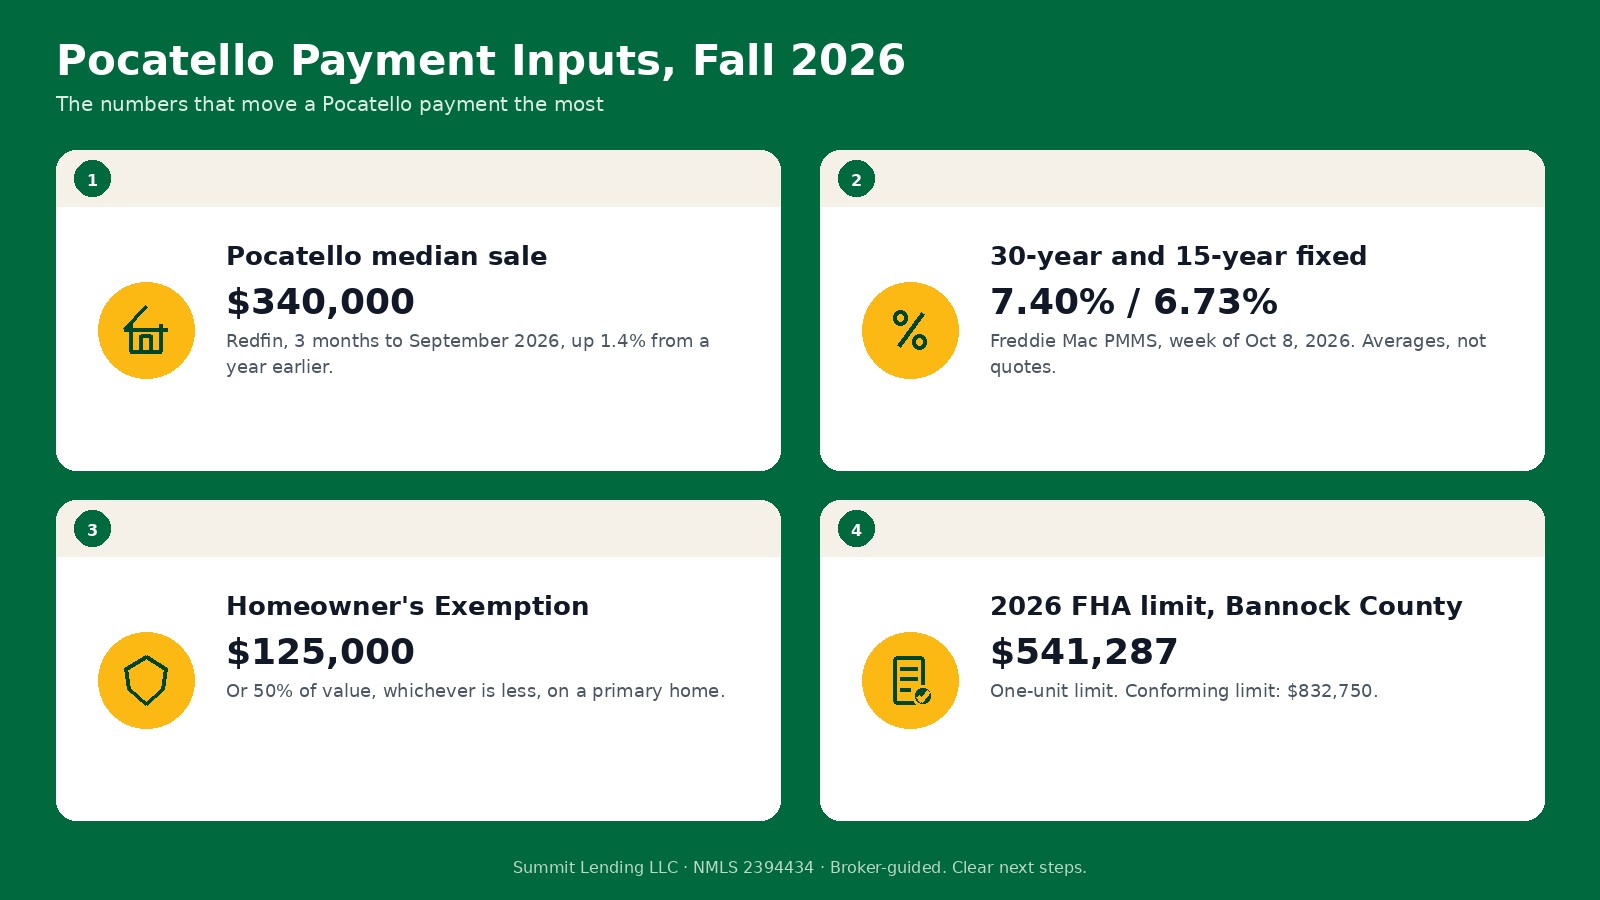
Redfin put the Pocatello median sale price at about $340,000 for the three months ending September 2026, up 1.4% from the same period a year earlier. About 203 homes sold in September, compared with 190 a year earlier, and homes took a median of about 36 days to sell, versus 31 days last year (Redfin Pocatello data). Prices are a little higher than a year ago, and homes are taking a bit longer to sell, which gives buyers some room to negotiate.
For the wider area, compare Bannock County and nearby towns like Inkom, McCammon, American Falls, and Blackfoot. Homes near Idaho State University are often rentals, and a former rental may not have had the homeowner's exemption.
Rates set the base of every estimate. Freddie Mac's weekly survey put the average 30-year fixed rate at 7.40% for the week of October 8, 2026, up from 7.28% a week earlier and 6.30% a year ago. It was the seventh weekly increase in a row and the highest reading since November 2023. The 15-year average was 6.73% (AP report on the Oct 8 survey; weekly history in the PMMS archive and on FRED). Those are national averages for borrowers with strong credit and roughly 20% down, not Pocatello quotes. Freddie Mac publishes a new reading every Thursday (PMMS page), so if you are running numbers a few weeks from now, update the rate first.
What goes into a Pocatello payment
- Principal and interest. The calculator's core result, set by price, down payment, rate, and term.
- Property tax. Based on value after the homeowner's exemption, multiplied by the levy for your taxing district.
- Homeowners insurance. Ask about wind and winter weather coverage, and check wildfire exposure on homes near the foothills.
- Mortgage insurance. PMI on conventional loans with less than 20% down, or FHA's annual premium.
- HOA dues. Less common in older neighborhoods, but many newer subdivisions have them.
Idaho's homeowner's exemption
Idaho exempts part of the value of an owner-occupied primary home from property tax. For 2026, the exemption is the lesser of $125,000 or 50% of the home's value, covering the home and up to one acre of land (Idaho State Tax Commission; Idaho Code 63-602G). On a $340,000 home, that means $125,000 of value is not taxed, so the taxable value is about $215,000. You apply with your county assessor after you buy, and it does not carry over from the seller automatically. The Bannock County Assessor handles exemption applications and value notices for Bannock County.
For the calculator, ask for the most recent tax bill on the address and check whether the seller had the exemption. If they did not, for example because the home was a rental, your bill could drop once yours is approved. If they did, the bill is a reasonable starting point.
Worked example: a $340,000 home in Pocatello
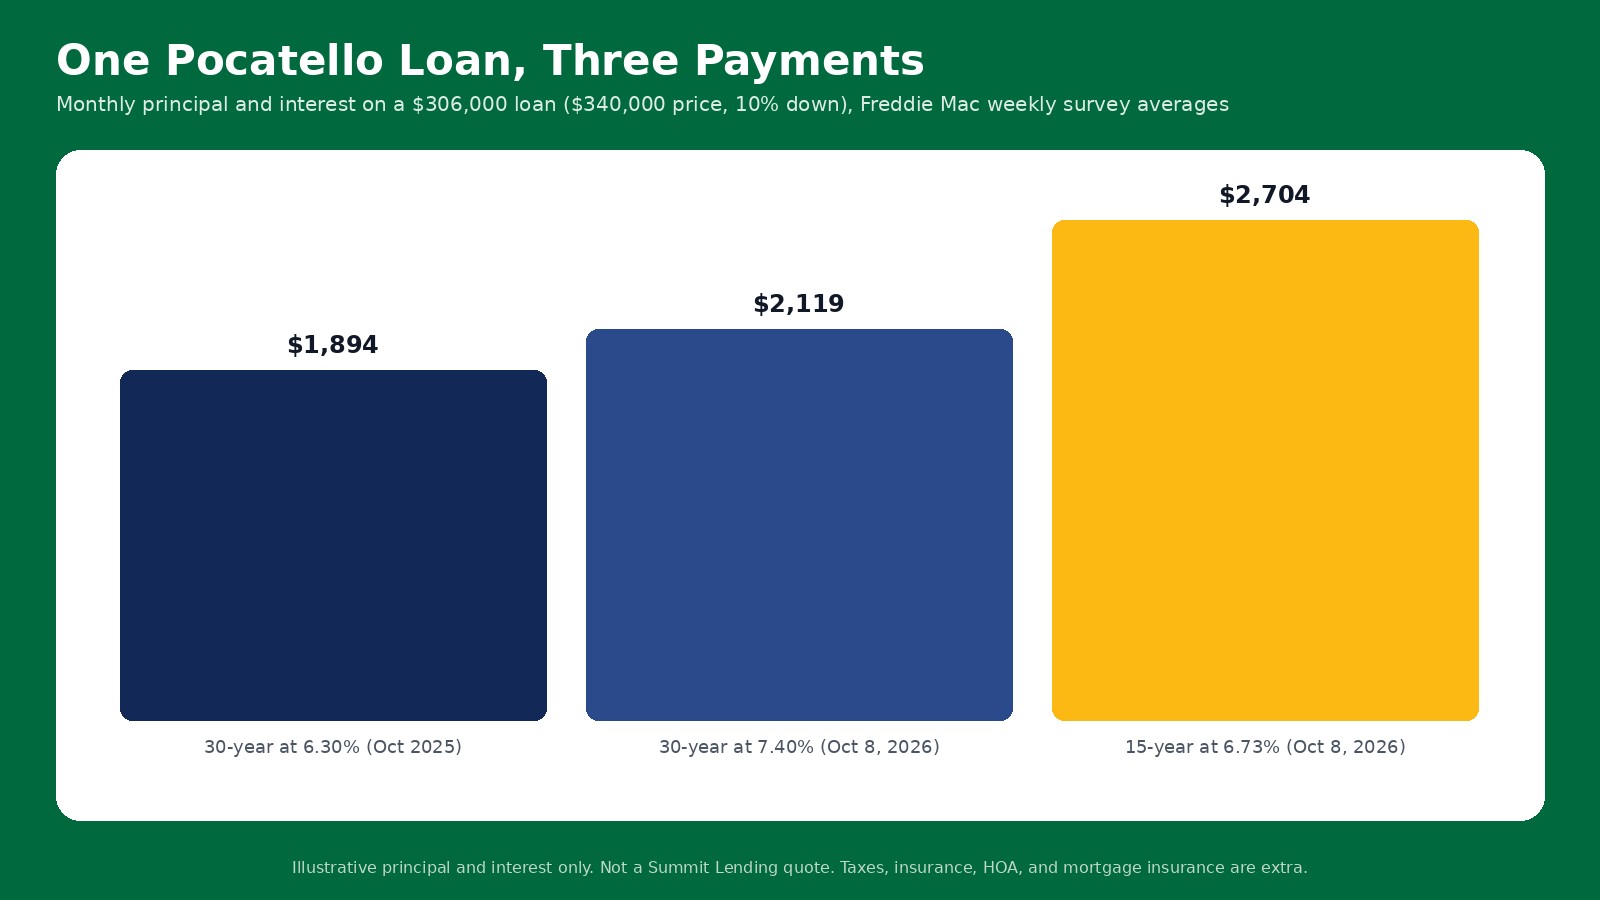
Take a $340,000 home near the Pocatello median with 10% down. The loan is $306,000. At 7.40%, principal and interest on a 30-year fixed is about $2,119 a month. At last year's 6.30%, the same loan would have been about $1,894, so the rate change alone adds about $225 a month.
A 15-year fixed at 6.73% raises the payment to about $2,704, while total interest drops to about $180,798, compared with about $456,726 over 30 years at 7.40%. Add tax, insurance, PMI, and HOA dues for the full number. If it is more than you want to carry, compare a lower price point, a larger down payment, a temporary or permanent rate buydown paid by the seller, or IHFA down payment assistance.
How the loan type changes your Pocatello result
Most online calculators assume a conventional loan with a fixed rate, which can make the number look better or worse than what you would actually get. Here is how the same $340,000 Pocatello home changes by program, using the 7.40% survey average as a stand-in rate. Your actual rate will differ by program and profile.
Conventional
Qualified buyers can put as little as 3% down on a one-unit primary home, which is $10,200 on $340,000 (Fannie Mae eligibility matrix). Below 20% down you pay private mortgage insurance, and you can ask to cancel it once the balance reaches 80% of the original value (CFPB on PMI). PMI is priced by credit score and down payment, so add it as a separate line in the calculator rather than guessing.
FHA
FHA requires 3.5% down with a 580 or higher score (HUD FHA overview). It also adds two insurance costs a basic calculator often skips: an upfront premium of 1.75% that is usually financed into the loan, and an annual premium paid monthly. For a base loan of $726,200 or less with more than 95% loan-to-value, the annual rate is 0.55% (HUD Mortgagee Letter 2023-05). On $340,000 with 3.5% down, the base loan is $328,100, the upfront premium adds $5,742, and principal and interest on $333,842 is about $2,311 at 7.40%. The monthly premium adds roughly $150, for about $2,462 before taxes and insurance. The 2026 FHA one-unit limit in Bannock County is $541,287, the national floor, so this price fits with plenty of room.
VA
Eligible veterans and service members can buy with no down payment and no monthly mortgage insurance (VA purchase loans). A one-time funding fee applies unless you are exempt, and for first use with less than 5% down it is 2.15% of the loan (VA funding fee). Financing that fee on $340,000 brings the loan to about $347,310, with principal and interest near $2,405 at 7.40%.
USDA
USDA guaranteed loans allow no down payment in eligible rural areas for households under the income limits (USDA guaranteed loans). Most of Pocatello is not eligible, but rural parts of Bannock County and nearby towns can be. Check an address on the USDA eligibility map before you count on it.
2026 loan limits in Pocatello
The 2026 conforming loan limit for a one-unit home in Bannock County is $832,750 (FHFA announcement, FHFA county file). The FHA one-unit limit is $541,287, the 2026 national floor for the Pocatello metro (HUD announcement, HUD lookup).
Down payment help in Idaho
Idaho Housing and Finance Association offers down payment and closing cost assistance of up to 8% of the sales price, repaid as a second loan, with a minimum of $500 of your own funds (IHFA down payment help). IHFA says a credit score of 620 or higher is typically beneficial for its loans (IHFA homebuyers). If you use it, add the second loan's payment, if any, to your estimate. Idaho also lets first-time buyers deduct deposits to a first-time homebuyer savings account from state taxable income (Idaho State Tax Commission). Our Pocatello first-time home buyer guide covers both in detail.
From a calculator estimate to a real number
- Run a few scenarios here. Try two prices, two down payments, and both a 30-year and 15-year term so you know your range.
- Get preapproved. A preapproval means a lender checked your credit, income, and assets. The CFPB points out that lenders use the terms prequalification and preapproval differently, so ask what was verified (CFPB comparison). Several mortgage credit checks within 45 days count as one inquiry for most scoring models, so shopping does not hurt your score more than once (CFPB on credit checks).
- Compare Loan Estimates. Lenders must send a Loan Estimate within three business days of your application, and the standard format makes side-by-side comparison easy (CFPB on Loan Estimates).
- Watch your debt-to-income ratio. Lenders compare your monthly debts, including the new payment, to gross monthly income (CFPB on DTI). A payment that fits your budget can still be too high for a program limit, or the reverse.
- Check the final numbers. Your Closing Disclosure arrives at least three business days before closing. Compare it to your Loan Estimate line by line (CFPB on Closing Disclosures).
Calculators for nearby areas
Pocatello area: Bannock County, Inkom, McCammon, American Falls, Blackfoot, and Bingham County. Elsewhere in Idaho: Idaho Falls, Twin Falls, and Boise. Or use the statewide Idaho mortgage calculator.
Related pages
See the Pocatello mortgage overview, Pocatello refinancing, Pocatello construction loans, Pocatello reverse mortgages, and Pocatello commercial loans. Statewide, compare Idaho mortgage loans, Idaho purchase loans, Idaho refinancing, Idaho preapproval, Idaho mortgage calculator.
Sources
- Redfin, Pocatello, ID housing market
- Redfin, Idaho housing market
- AP via WTOP, Freddie Mac rates for Oct 8, 2026
- Freddie Mac PMMS archive
- Freddie Mac Primary Mortgage Market Survey
- FRED, 30-Year Fixed Rate Mortgage Average
- Idaho State Tax Commission, homeowner's exemption
- Idaho Code 63-602G, homestead exemption
- Bannock County Assessor
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- HUD, Let FHA loans help you
- HUD Mortgagee Letter 2023-05, FHA annual MIP (PDF)
- VA purchase loan
- VA funding fee and closing costs
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- FHFA, 2026 conforming loan limits
- FHFA 2026 county loan limit list
- HUD No. 25-145, 2026 FHA loan limits
- HUD FHA mortgage limits lookup
- Idaho Housing and Finance Association, down payment help
- Idaho Housing and Finance Association, homebuyers
- Idaho State Tax Commission, first-time homebuyer savings account
- CFPB, prequalification vs. preapproval
- CFPB, when a lender checks your credit
- CFPB, What is a Loan Estimate?
- CFPB, debt-to-income ratio
- CFPB, What is a Closing Disclosure?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.
Have a construction project?
See our construction loan calculator and pricing options for one-time and two-time close loans.
Explore construction loans