Salt Lake County Mortgage Calculator
Rate History
Are you a first time Home buyer?
Our First Time Home Buyer Assistance Program is just what you need.Salt Lake County mortgage calculator: plan the whole payment
Salt Lake County is Utah's largest housing market and one of its most expensive, so small changes in rate, price, or loan type move the payment more here than in most of the state. This page gives you current county numbers, a worked example at the county median, and the Utah tax and loan rules that belong in any honest estimate. Summit Lending LLC (NMLS 2394434) is a Utah mortgage broker based in Garland, Utah. We compare loans from multiple wholesale lenders and can turn your calculator result into a real quote for a home anywhere in the valley.
Ready to shop? Start a Salt Lake County preapproval, or read about Salt Lake County purchase loans.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
Salt Lake County numbers to start with
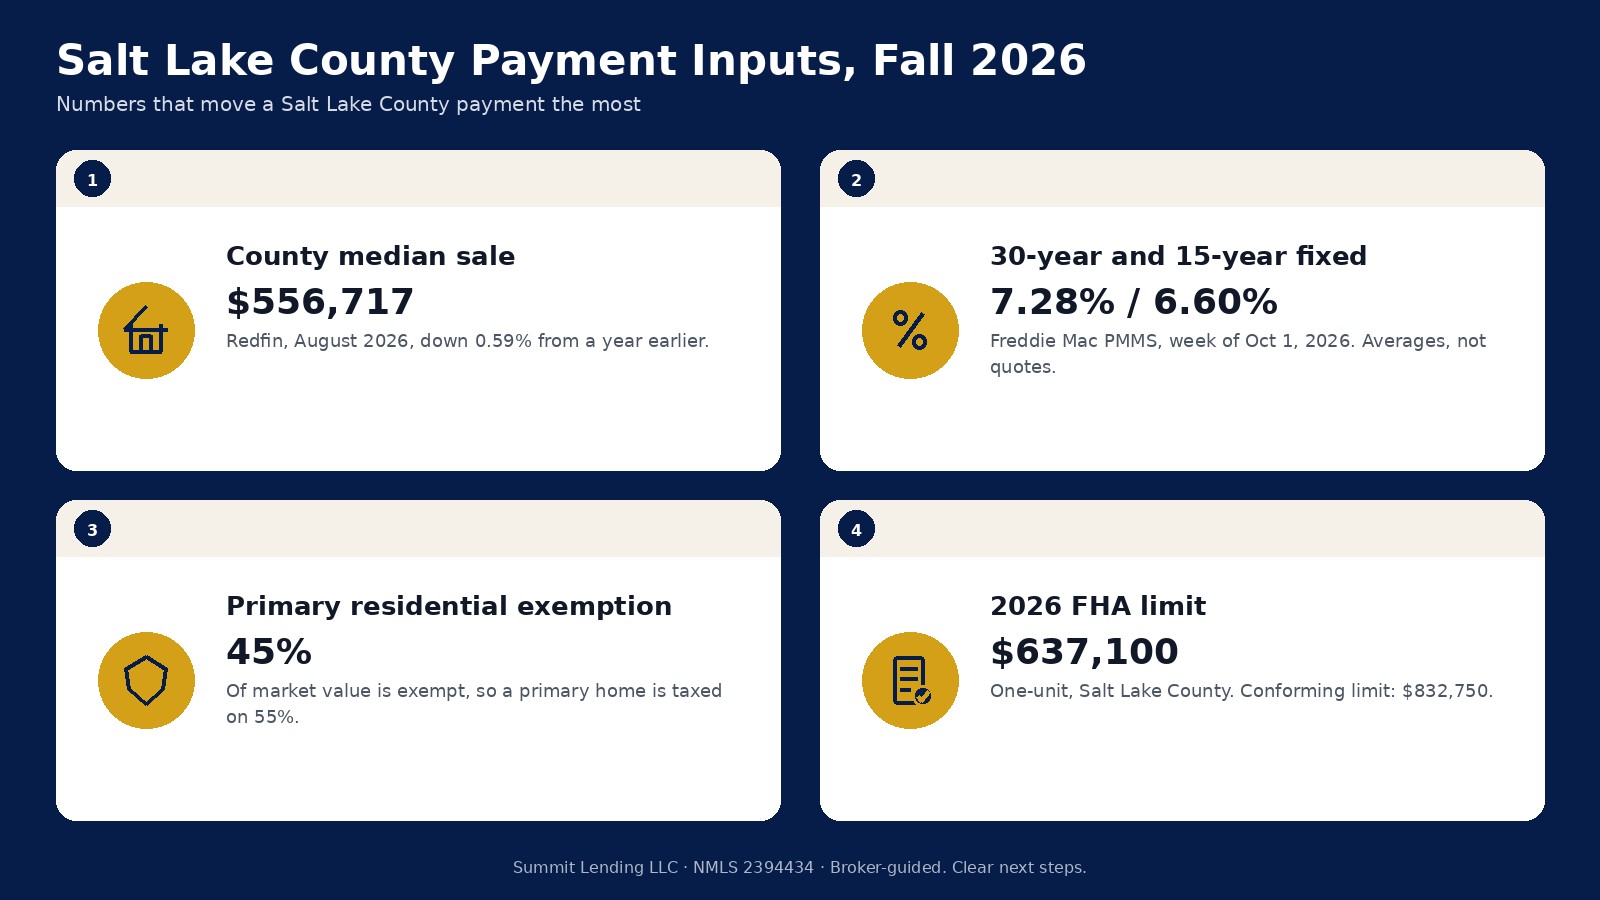
Redfin put the Salt Lake County median sale price at about $556,717 in August 2026, down 0.59% from a year earlier. About 921 homes sold that month, homes took around 48 days to go under contract, and the average sale-to-list ratio was about 98.6% (Redfin Salt Lake County data). That is a flat, balanced market: prices are not running away, and well-priced homes still sell close to asking. The statewide Utah median was about $522,823 (Redfin Utah data), so the county runs above the state.
Prices also vary a lot inside the county. Condos and townhomes near downtown Salt Lake City and Midvale can sit well below the median, while newer single-family homes in Draper, South Jordan, and Riverton often sit above it. Use a price that matches the neighborhood you are shopping.
Rates set the base of every estimate. Freddie Mac's weekly survey put the average 30-year fixed rate at 7.28% for the week of October 1, 2026, up from 7.03% a week earlier and 6.34% a year ago. The 15-year average was 6.60% (Freddie Mac PMMS; history on FRED). Those are national averages for borrowers with strong credit and roughly 20% down, not Salt Lake County quotes. Freddie Mac publishes a new reading every Thursday (PMMS page), so if you are running numbers a few weeks from now, update the rate first.
What goes into a Salt Lake County payment
- Principal and interest. The calculator's core result.
- Property tax. Based on 55% of market value for a primary home, multiplied by the combined rate for your exact taxing area.
- Homeowners insurance. Ask your agent about earthquake coverage, which is usually a separate policy or endorsement along the Wasatch Front.
- Mortgage insurance. PMI on conventional loans with less than 20% down, or FHA's annual premium.
- HOA dues. Most condos and townhomes have them, and many newer subdivisions in the southwest part of the valley do too.
Utah's primary residential exemption
Utah taxes a primary residence on only part of its value. The primary residential exemption is 45% of fair market value, so a qualifying home is taxed on 55% of its value. It covers the home and up to one acre of land, and the home has to be a primary residence for at least 183 days of the year (Utah State Tax Commission; residential property guidance). On a $555,000 home, the taxable value would be about $305,250. A second home or rental is taxed on full value, which can make the same house cost much more to hold as an investment.
For the calculator, start with the seller's most recent tax notice and confirm the home was taxed as a primary residence. If it was a rental, your bill may drop after you qualify for the exemption.
Worked example: a $555,000 home in Salt Lake County
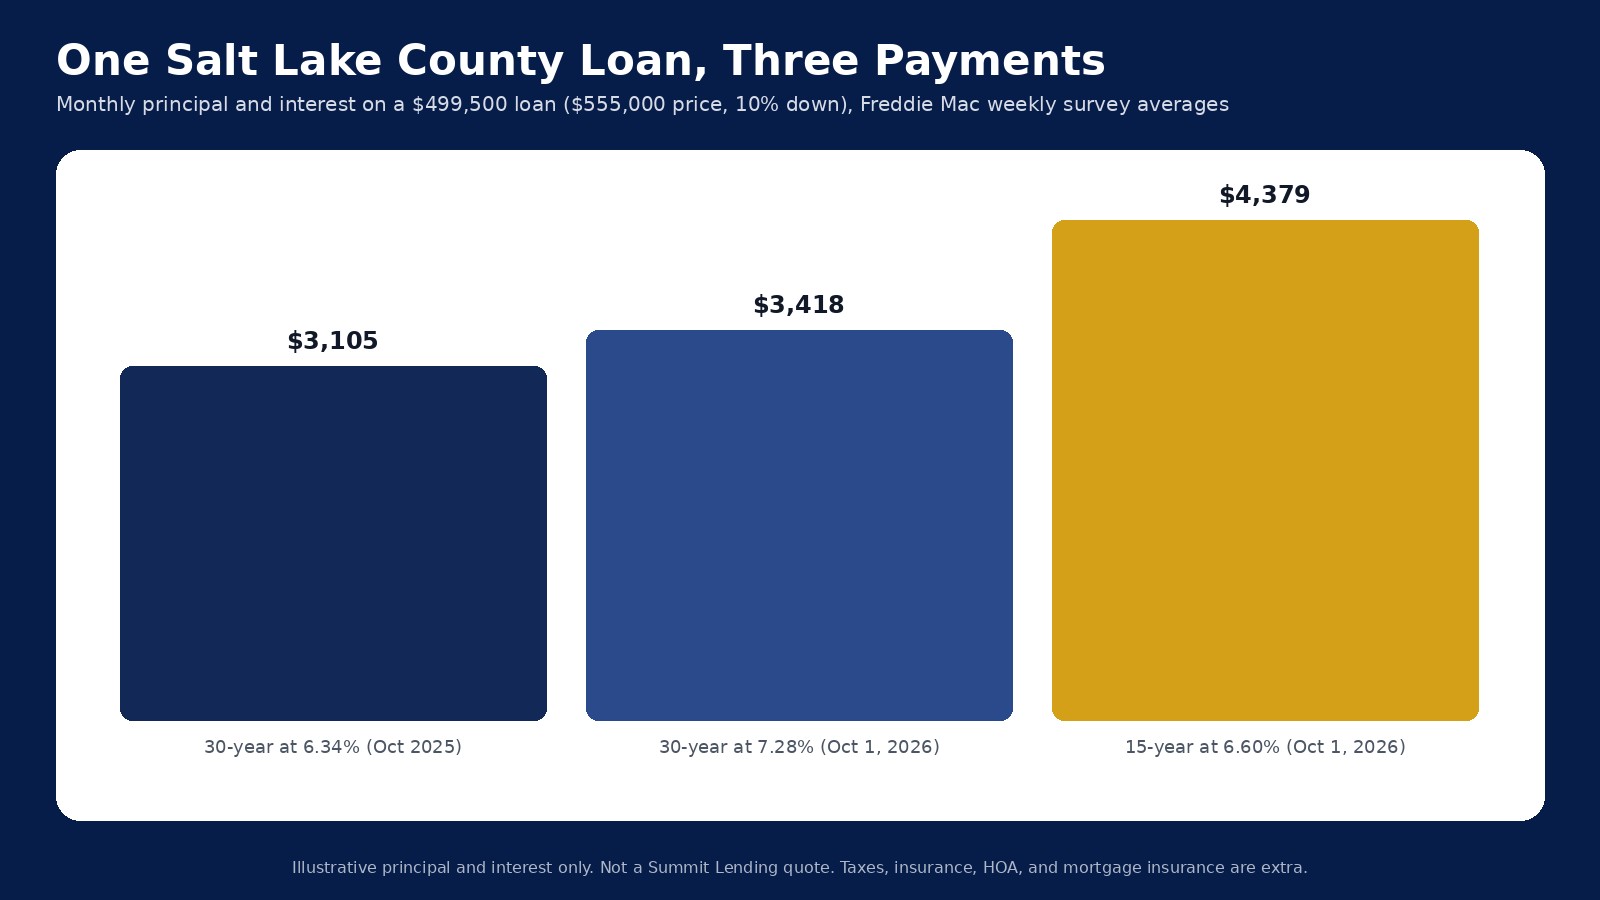
Take a $555,000 home near the county median with 10% down. The loan is $499,500. At 7.28%, principal and interest on a 30-year fixed is about $3,418 a month. At last year's 6.34%, the same loan would have been about $3,105, so the rate change alone adds about $313 a month.
A 15-year fixed at 6.60% raises the payment to about $4,379, while total interest drops to about $288,664, compared with about $730,851 over 30 years at 7.28%. Add tax, insurance, PMI, and HOA dues for the full number. If it is more than you want to carry, compare a lower price point, a larger down payment, or Utah Housing assistance.
How the loan type changes your Utah result
Most online calculators assume a conventional loan with a fixed rate, which can make the number look better or worse than what you would actually get. Here is how the same $555,000 Utah home changes by program, using the 7.28% survey average as a stand-in rate. Your actual rate will differ by program and profile.
Conventional
Qualified buyers can put as little as 3% down on a one-unit primary home, which is $16,650 on $555,000 (Fannie Mae eligibility matrix). Below 20% down you pay private mortgage insurance, and you can ask to cancel it once the balance reaches 80% of the original value (CFPB on PMI). PMI is priced by credit score and down payment, so add it as a separate line in the calculator rather than guessing.
FHA
FHA requires 3.5% down with a 580 or higher score (HUD FHA overview). It also adds two insurance costs a basic calculator often skips: an upfront premium of 1.75% that is usually financed into the loan, and an annual premium paid monthly. For a base loan of $726,200 or less with more than 95% loan-to-value, the annual rate is 0.55% (HUD Mortgagee Letter 2023-05). On $555,000 with 3.5% down, the base loan is $535,575, the upfront premium adds $9,373, and principal and interest on $544,948 is about $3,729 at 7.28%. The monthly premium adds roughly $245, for about $3,974 before taxes and insurance. The 2026 FHA one-unit limit in Salt Lake County is $637,100, so this price fits with room to spare.
VA
Eligible veterans and service members can buy with no down payment and no monthly mortgage insurance (VA purchase loans). A one-time funding fee applies unless you are exempt, and for first use with less than 5% down it is 2.15% of the loan (VA funding fee). Financing that fee on $555,000 brings the loan to about $566,932, with principal and interest near $3,879 at 7.28%.
USDA
USDA guaranteed loans allow no down payment in eligible rural areas for households under the income limits (USDA guaranteed loans). Most of Salt Lake County is outside USDA eligible areas, so most buyers here use FHA, VA, or conventional financing. Check an address on the USDA eligibility map before you count on it.
2026 loan limits in Salt Lake County
The 2026 conforming loan limit for a one-unit home in Salt Lake County is $832,750 (FHFA announcement, FHFA county file). Nearby Summit County and Wasatch County have a higher limit of $1,150,000. The county's FHA one-unit limit is $637,100 (HUD announcement, HUD lookup). A loan above $832,750 is a jumbo loan, which is more common on the east bench and in the southeast part of the valley.
Down payment help
Utah Housing Corporation offers down payment assistance and first mortgage programs through participating lenders (Utah Housing down payment assistance). If you plan to use assistance, include it in the down payment field, and remember that a repayable second loan adds its own payment. See our Salt Lake County first-time home buyer guide for the details.
From a calculator estimate to a real number
- Run a few scenarios here. Try two prices, two down payments, and both a 30-year and 15-year term so you know your range.
- Get preapproved. A preapproval means a lender checked your credit, income, and assets. The CFPB points out that lenders use the terms prequalification and preapproval differently, so ask what was verified (CFPB comparison). Several mortgage credit checks within 45 days count as one inquiry for most scoring models, so shopping does not hurt your score more than once (CFPB on credit checks).
- Compare Loan Estimates. Lenders must send a Loan Estimate within three business days of your application, and the standard format makes side-by-side comparison easy (CFPB on Loan Estimates).
- Watch your debt-to-income ratio. Lenders compare your monthly debts, including the new payment, to gross monthly income (CFPB on DTI). A payment that fits your budget can still be too high for a program limit, or the reverse.
- Check the final numbers. Your Closing Disclosure arrives at least three business days before closing. Compare it to your Loan Estimate line by line (CFPB on Closing Disclosures).
Calculators for Salt Lake County cities and nearby counties
Cities in the county: Salt Lake City, West Jordan, South Jordan, Draper, Riverton, Midvale, and Magna. Nearby counties: Davis County, Utah County, Tooele County, Weber County, Summit County, and Wasatch County. North of the county line, Bountiful also has its own calculator.
Related pages
See the Salt Lake County mortgage overview, Salt Lake County refinancing, Salt Lake County construction loans, Salt Lake County reverse mortgages, and the statewide Utah mortgage calculator. For Salt Lake City itself, see Salt Lake City preapproval.
Sources
- Redfin, Salt Lake County housing market
- Redfin, Utah housing market
- Freddie Mac PMMS, Oct 1, 2026 release
- Freddie Mac Primary Mortgage Market Survey
- FRED, 30-Year Fixed Rate Mortgage Average
- Utah State Tax Commission, primary residential exemption
- Utah State Tax Commission, residential property
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- HUD, Let FHA loans help you
- HUD Mortgagee Letter 2023-05, FHA annual MIP (PDF)
- VA purchase loan
- VA funding fee and closing costs
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- FHFA, 2026 conforming loan limits
- FHFA 2026 county loan limit list
- HUD No. 25-145, 2026 FHA loan limits
- HUD FHA mortgage limits lookup
- Utah Housing Corporation, down payment assistance
- CFPB, prequalification vs. preapproval
- CFPB, when a lender checks your credit
- CFPB, What is a Loan Estimate?
- CFPB, debt-to-income ratio
- CFPB, What is a Closing Disclosure?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.