
Rock Springs Mortgage Calculator

Rate History
Are you a first time Home buyer?
Our First Time Home Buyer Assistance Program is just what you need.Rock Springs mortgage calculator: plan the whole payment
Rock Springs is the largest city in Sweetwater County, with an economy tied to energy, trona mining, and the businesses that support them, plus Western Wyoming Community College. Prices are moderate, and the market moves with local hiring. This page gives you current Rock Springs numbers, a worked example near the local median, and the Wyoming tax and loan rules that belong in any honest estimate. Summit Lending LLC (NMLS 2394434) is a mortgage broker based in Garland, Utah. We compare loans from multiple wholesale lenders and can turn your calculator result into a real quote for a home in Rock Springs.
Ready to shop? Start a Rock Springs preapproval, or read about Rock Springs purchase loans.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
Rock Springs numbers to start with
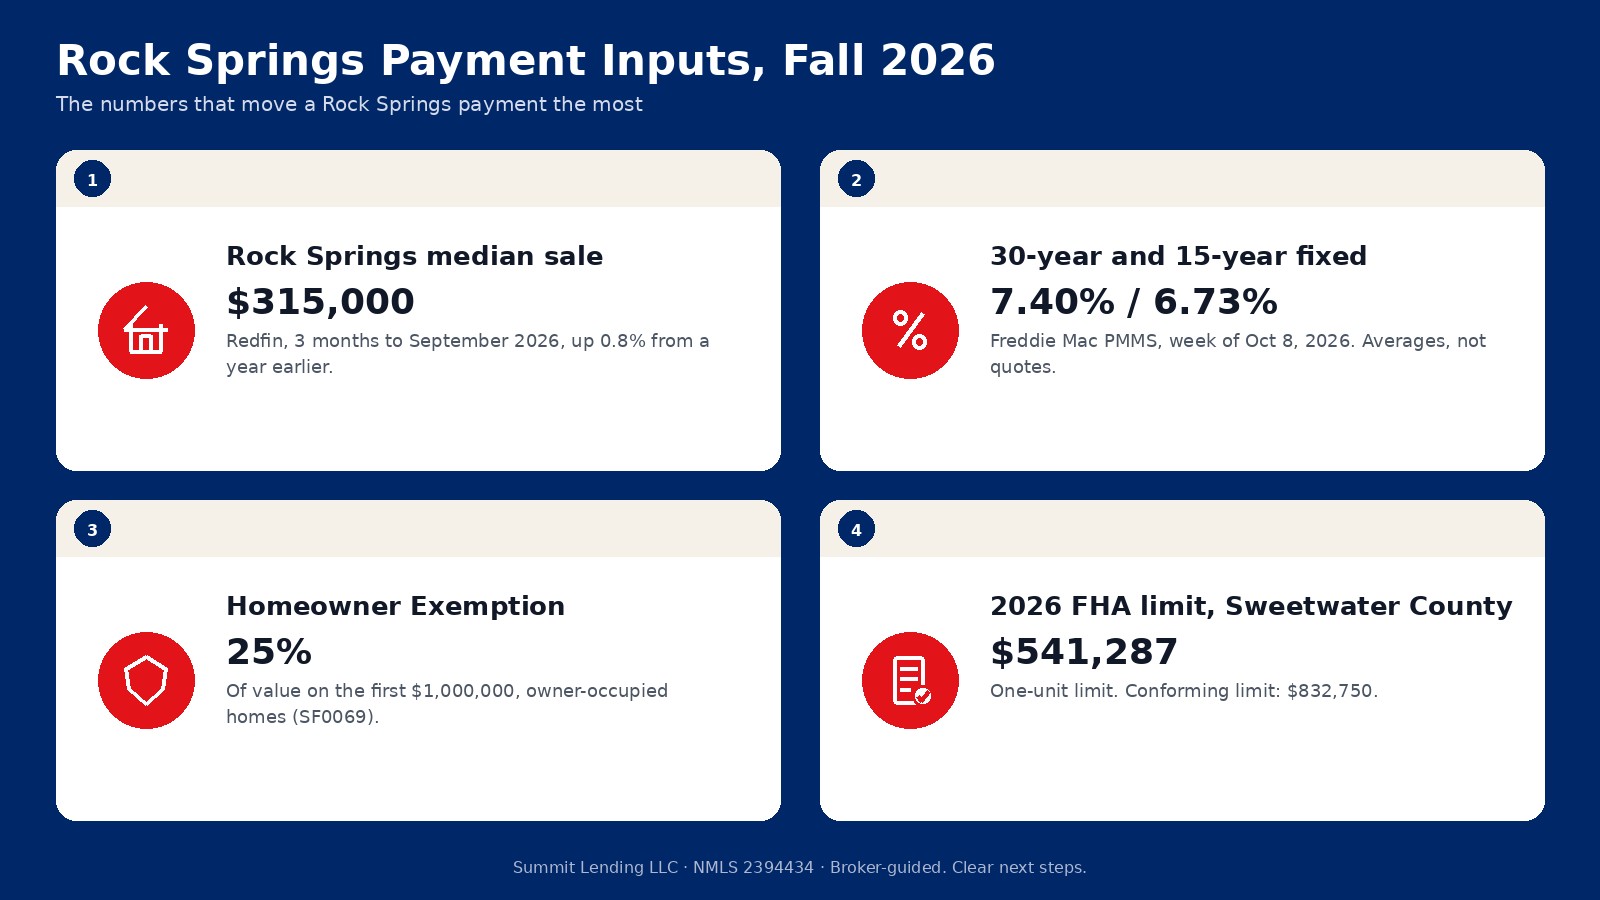
Redfin put the Rock Springs median sale price at about $315,000 for the three months ending September 2026, up 0.8% from the same period a year earlier. About 75 homes sold in September, compared with 68 a year earlier, and homes took a median of about 51 days to sell, versus 26 days last year, with an average sale-to-list ratio near 98.1% (Redfin Rock Springs data). Prices are about flat compared with a year ago, and homes are taking much longer to sell than last year, which gives buyers more room to negotiate.
For the wider area, compare Sweetwater County and other southwest Wyoming towns like Evanston and Kemmerer. If your income includes overtime, shift pay, or bonuses, ask how a lender will average it before you set a price range.
Rates set the base of every estimate. Freddie Mac's weekly survey put the average 30-year fixed rate at 7.40% for the week of October 8, 2026, up from 7.28% a week earlier and 6.30% a year ago. It was the seventh weekly increase in a row and the highest reading since November 2023. The 15-year average was 6.73% (AP report on the Oct 8 survey; weekly history in the PMMS archive and on FRED). Those are national averages for borrowers with strong credit and roughly 20% down, not Rock Springs quotes. Freddie Mac publishes a new reading every Thursday (PMMS page), so if you are running numbers a few weeks from now, update the rate first.
What goes into a Rock Springs payment
- Principal and interest. The calculator's core result, set by price, down payment, rate, and term.
- Property tax. Wyoming has relatively low property tax rates, and owner-occupied homes can qualify for the 25% homeowner exemption from SF0069.
- Homeowners insurance. Ask about wind and hail coverage and deductibles, which matter on the open plains.
- Mortgage insurance. PMI on conventional loans with less than 20% down, or FHA's annual premium.
- HOA dues. Uncommon, but some newer subdivisions and townhomes have them.
Wyoming property tax and the 2025 homeowner exemption
Wyoming lawmakers passed Senate File 69 in 2025, creating a homeowner exemption equal to 25% of fair market value on the first $1,000,000 of value for an owner-occupied single-family home (SF0069 enrolled act). To qualify, the owner must have lived in the home for at least eight months of the year and file an affidavit. The Wyoming Department of Revenue explains the filing process and timing for each tax year (Wyoming homeowner exemption). On a $315,000 home, 25% of value is about $78,750 that would not be taxed once you qualify.
For the calculator, this means two things. First, a listing that shows the seller's tax bill may already include the exemption, which you would only receive once you qualify. Second, your first year of escrow might be estimated without it. We check this with you so the payment does not jump unexpectedly after the first escrow analysis.
Worked example: a $315,000 home in Rock Springs
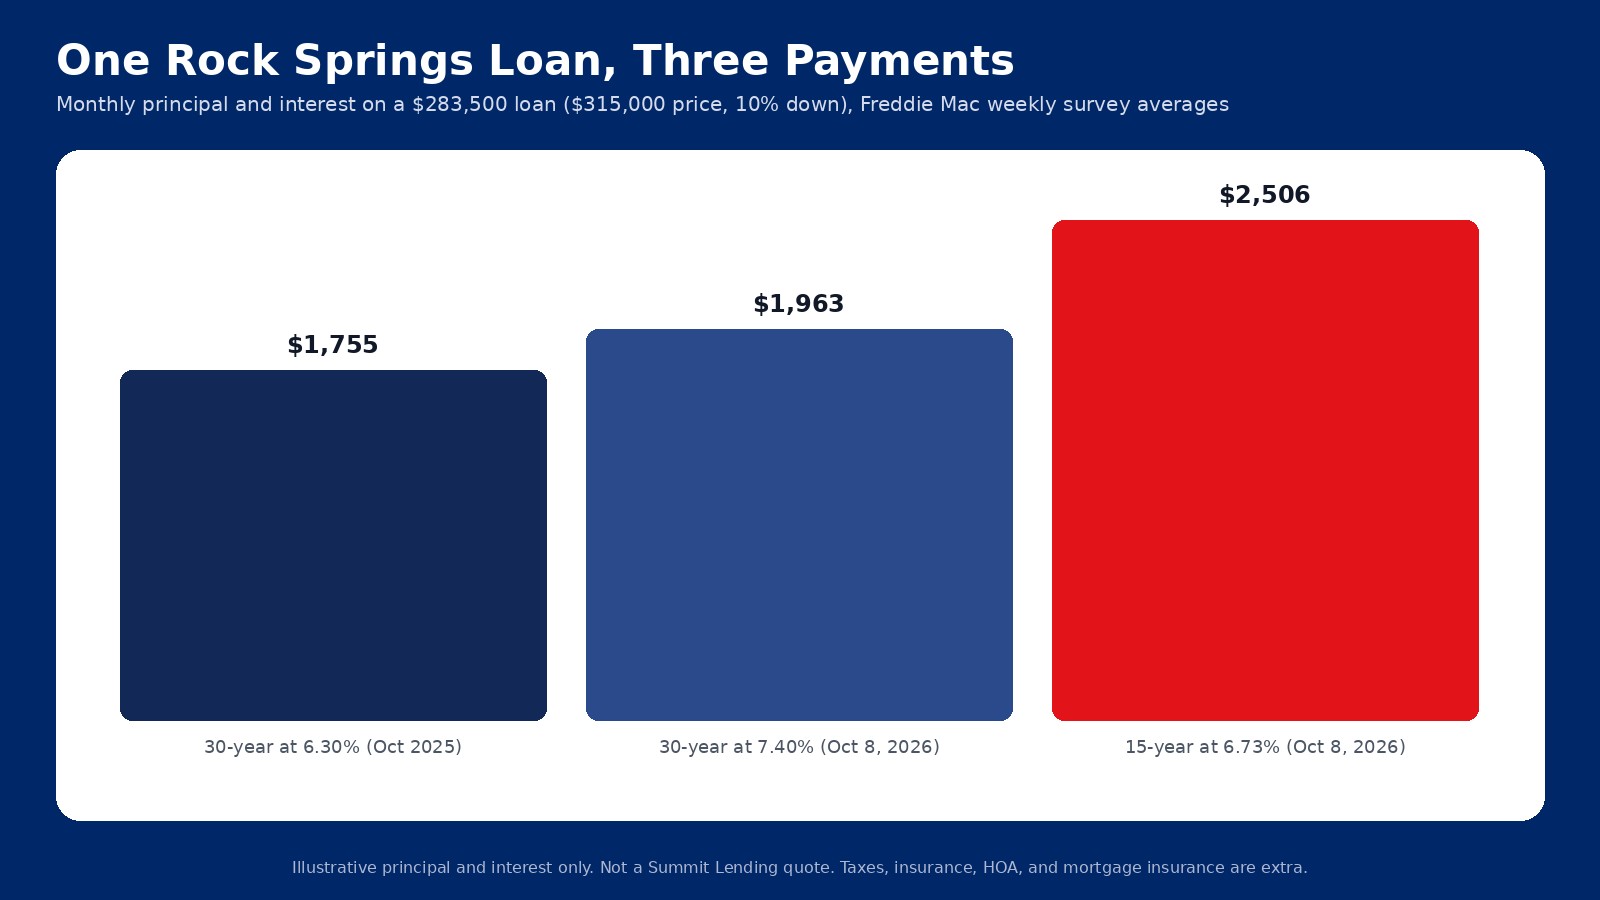
Take a $315,000 home near the Rock Springs median with 10% down. The loan is $283,500. At 7.40%, principal and interest on a 30-year fixed is about $1,963 a month. At last year's 6.30%, the same loan would have been about $1,755, so the rate change alone adds about $208 a month.
A 15-year fixed at 6.73% raises the payment to about $2,506, while total interest drops to about $167,504, compared with about $423,143 over 30 years at 7.40%. Add tax, insurance, PMI, and HOA dues for the full number. If it is more than you want to carry, compare a lower price point, a larger down payment, a temporary or permanent rate buydown paid by the seller, or WCDA down payment assistance.
How the loan type changes your Rock Springs result
Most online calculators assume a conventional loan with a fixed rate, which can make the number look better or worse than what you would actually get. Here is how the same $315,000 Rock Springs home changes by program, using the 7.40% survey average as a stand-in rate. Your actual rate will differ by program and profile.
Conventional
Qualified buyers can put as little as 3% down on a one-unit primary home, which is $9,450 on $315,000 (Fannie Mae eligibility matrix). Below 20% down you pay private mortgage insurance, and you can ask to cancel it once the balance reaches 80% of the original value (CFPB on PMI). PMI is priced by credit score and down payment, so add it as a separate line in the calculator rather than guessing.
FHA
FHA requires 3.5% down with a 580 or higher score (HUD FHA overview). It also adds two insurance costs a basic calculator often skips: an upfront premium of 1.75% that is usually financed into the loan, and an annual premium paid monthly. For a base loan of $726,200 or less with more than 95% loan-to-value, the annual rate is 0.55% (HUD Mortgagee Letter 2023-05). On $315,000 with 3.5% down, the base loan is $303,975, the upfront premium adds $5,320, and principal and interest on $309,295 is about $2,141 at 7.40%. The monthly premium adds roughly $139, for about $2,281 before taxes and insurance. The 2026 FHA one-unit limit in Sweetwater County is $541,287, the national floor, so this price fits with plenty of room.
VA
Eligible veterans and service members can buy with no down payment and no monthly mortgage insurance (VA purchase loans). A one-time funding fee applies unless you are exempt, and for first use with less than 5% down it is 2.15% of the loan (VA funding fee). Financing that fee on $315,000 brings the loan to about $321,772, with principal and interest near $2,228 at 7.40%.
USDA
USDA guaranteed loans allow no down payment in eligible rural areas for households under the income limits (USDA guaranteed loans). Many Rock Springs and Sweetwater County addresses may qualify, but eligibility depends on the exact address. Check an address on the USDA eligibility map before you count on it.
2026 loan limits in Rock Springs
The 2026 conforming loan limit for a one-unit home in Sweetwater County is $832,750 (FHFA announcement, FHFA county file). The FHA one-unit limit is $541,287, the 2026 national floor for the Rock Springs area (HUD announcement, HUD lookup).
Down payment help in Wyoming
The Wyoming Community Development Authority (WCDA) offers down payment assistance of up to $15,000 through participating lenders, with a 620 minimum credit score and a $1,500 minimum borrower contribution, and it also has a Home$tretch option at 0% interest for eligible buyers (WCDA homebuyers). Price and income limits apply by county (WCDA limits). If you plan to use assistance, add it as part of your down payment in the calculator, and remember that a repayable second loan adds its own monthly payment. Our Rock Springs first-time home buyer guide walks through it.
From a calculator estimate to a real number
- Run a few scenarios here. Try two prices, two down payments, and both a 30-year and 15-year term so you know your range.
- Get preapproved. A preapproval means a lender checked your credit, income, and assets. The CFPB points out that lenders use the terms prequalification and preapproval differently, so ask what was verified (CFPB comparison). Several mortgage credit checks within 45 days count as one inquiry for most scoring models, so shopping does not hurt your score more than once (CFPB on credit checks).
- Compare Loan Estimates. Lenders must send a Loan Estimate within three business days of your application, and the standard format makes side-by-side comparison easy (CFPB on Loan Estimates).
- Watch your debt-to-income ratio. Lenders compare your monthly debts, including the new payment, to gross monthly income (CFPB on DTI). A payment that fits your budget can still be too high for a program limit, or the reverse.
- Check the final numbers. Your Closing Disclosure arrives at least three business days before closing. Compare it to your Loan Estimate line by line (CFPB on Closing Disclosures).
Calculators for nearby areas
Nearby: Sweetwater County, Evanston, Kemmerer, Rawlins, and Lander. Elsewhere in Wyoming: Laramie, Casper, and Cheyenne. Or use the statewide Wyoming mortgage calculator.
Related pages
See the Rock Springs mortgage overview, Rock Springs refinancing, Rock Springs construction loans, Rock Springs reverse mortgages, and Rock Springs commercial loans. Statewide, compare Wyoming mortgage loans, Wyoming purchase loans, Wyoming refinancing, Wyoming preapproval, Wyoming mortgage calculator.
Sources
- Redfin, Rock Springs, WY housing market
- Redfin, Wyoming housing market
- AP via WTOP, Freddie Mac rates for Oct 8, 2026
- Freddie Mac PMMS archive
- Freddie Mac Primary Mortgage Market Survey
- FRED, 30-Year Fixed Rate Mortgage Average
- Wyoming SF0069 (2025), homeowner tax exemption (PDF)
- Wyoming Department of Revenue, homeowner exemption
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- HUD, Let FHA loans help you
- HUD Mortgagee Letter 2023-05, FHA annual MIP (PDF)
- VA purchase loan
- VA funding fee and closing costs
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- FHFA, 2026 conforming loan limits
- FHFA 2026 county loan limit list
- HUD No. 25-145, 2026 FHA loan limits
- HUD FHA mortgage limits lookup
- Wyoming Community Development Authority, homebuyers
- WCDA purchase price and income limits
- CFPB, prequalification vs. preapproval
- CFPB, when a lender checks your credit
- CFPB, What is a Loan Estimate?
- CFPB, debt-to-income ratio
- CFPB, What is a Closing Disclosure?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.




