White County Home Purchase Loans
White County home purchase loans, compared across lenders
White County is part of the Searcy micropolitan area, with Searcy as the county seat, and at 1,042 square miles it is the second-largest county in Arkansas by area. In the 2020 Census, 67.5% of occupied homes were owner-occupied and 32.5% were rented (Wikipedia). A renter buying a first home, a current owner moving up, and a buyer looking at a rural address do not all finance the same way, and here a current owner can still use ADFA's StartSmart program because the county is federally targeted. Summit Lending LLC (NMLS 2394434) is a mortgage broker based in Garland, Utah and licensed in Arkansas. We compare purchase loans from multiple wholesale lenders, so buyers can see the real differences in rate, fees, down payment, and mortgage insurance before making an offer.
This page covers the local market, loan options, 2026 limits, Arkansas down payment help, and the costs that catch buyers off guard. To see a payment first, use the White County mortgage calculator. Ready to shop? Start a White County preapproval. For the whole state, see our Arkansas home purchase loans page and the Arkansas preapproval guide. Lonoke County borders White County to the southwest and Faulkner County borders it to the west, and both have their own pages: Lonoke County purchase loans and Faulkner County purchase loans.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
The White County market
Redfin put the White County median sale price at about $211,000 for the three months ending September 2026, down 7.5% from a year earlier. Homes took a median of about 42 days to sell, compared with 57 days a year earlier, and they sold for about 97.7% of list price on average. Fewer homes sold in September than a year earlier: 79 against 88 (Redfin White County data). Redfin also reports that about 13.0% of homes sold above list price. On price cuts, Redfin shows 22.4% of homes with price drops, up 3.0 points from 19.4% a year earlier.
What that means for a buyer: prices are lower than a year ago, homes are selling faster, and fewer homes sold in September than a year earlier. Lower prices with faster sales mean a well-priced home may not wait, so have your budget and letter ready before you tour. A verified preapproval matters in either case. Homes closed an average of about 2.3 points under list (97.7% of list), and about 13.0% sold above it, so a seller comparing two offers will look hard at which buyer is more likely to close. County medians hide differences between the towns and the rural addresses, so price the payment on each home you are serious about rather than on the median.
Rates set the base of every estimate. Freddie Mac's weekly survey put the average 30-year fixed rate at 7.32% as of October 22, 2026, down from 7.40% a week earlier and up from 6.19% a year ago. The 15-year average was 6.68%, down slightly from 6.71% a week earlier (Freddie Mac PMMS, Oct 22, 2026; weekly history in the PMMS archive and on FRED). Those are national averages for borrowers with strong credit and roughly 20% down, not White County quotes. Freddie Mac publishes a new reading every Thursday, so if you are running numbers a few weeks from now, update the rate first.
Purchase loan options for White County buyers
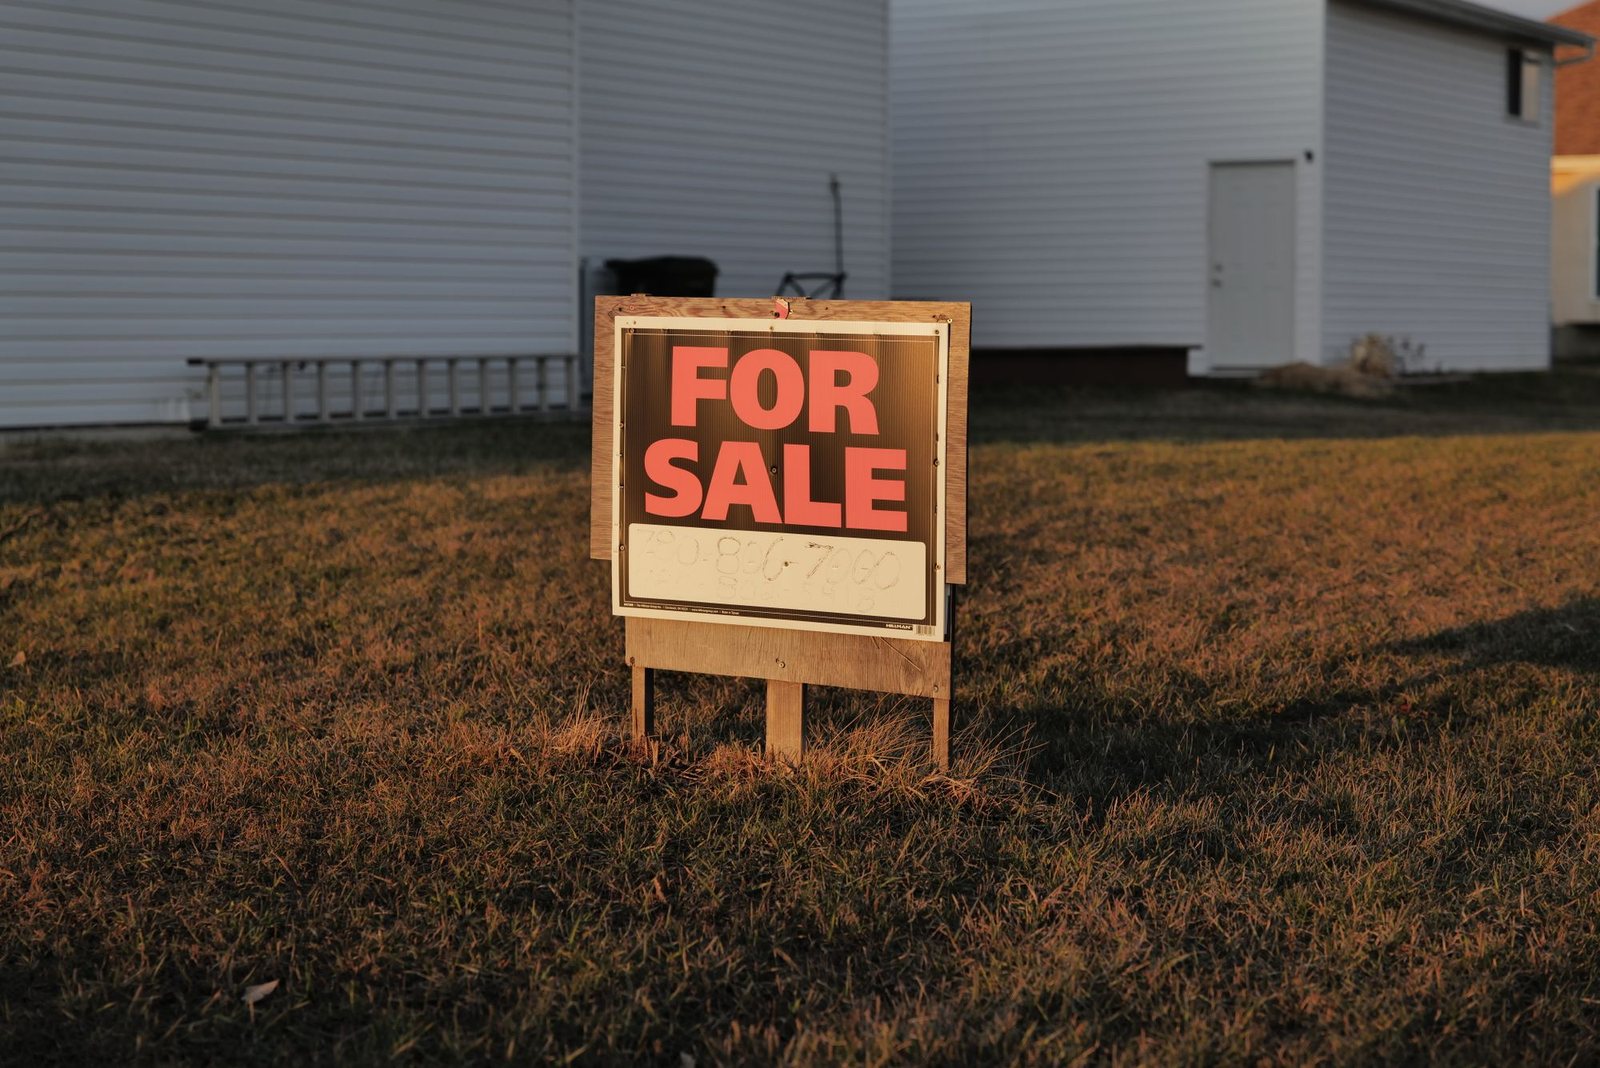
Most White County buyers end up comparing four programs: conventional, FHA, VA, and USDA. The graphic above shows the minimum down payment for each, and the section after the worked example below runs the same home through every program with real mortgage insurance and funding fee math. Two things narrow the choice quickly. VA is usually the first loan to price if you are eligible, and USDA can work at some addresses, but only if the property and your household income qualify.
Loan limits and jumbo loans
The 2026 conforming loan limit is $832,750 for a one-unit home in White County (FHFA announcement; FHFA county file). Loans above that are jumbo loans. With a median price near $211,000, most local buyers never approach the limit, but we can quote a jumbo loan for a higher-priced home. For FHA, the one-unit limit in the Searcy area is $541,287, the national floor (HUD announcement; HUD lookup tool).
Worked example: a $210,000 home in White County
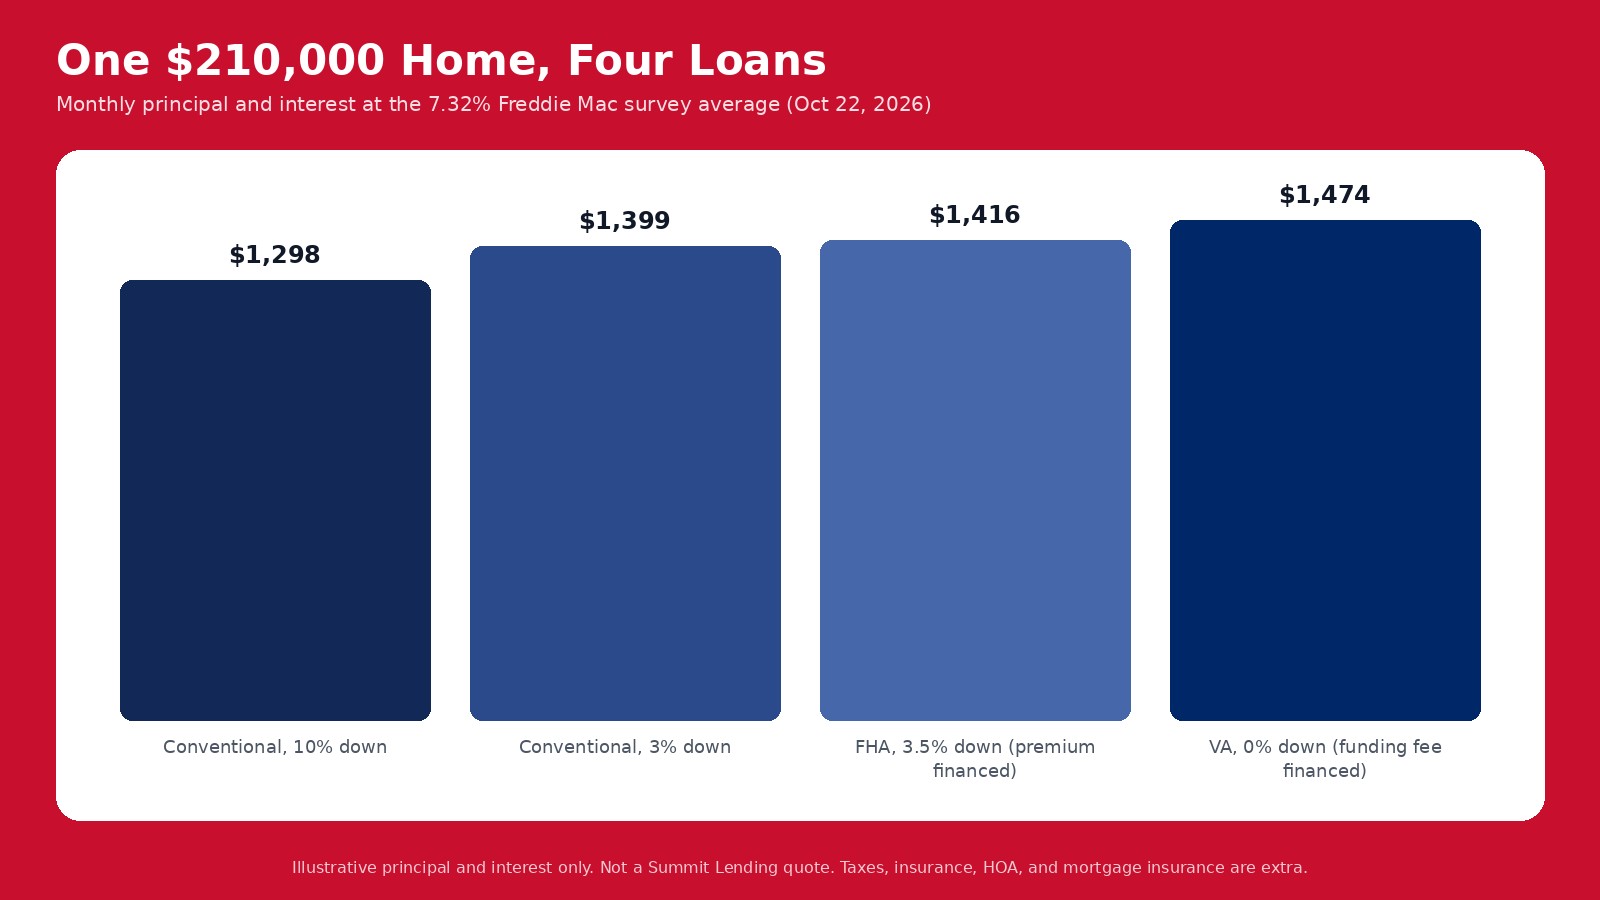
Take a $210,000 home near the county median with 10% down. The down payment is $21,000 and the loan is $189,000. At 7.32%, principal and interest on a 30-year fixed is about $1,298 a month. At last year's 6.19%, the same loan would have been about $1,156, so the rate change alone adds about $142 a month. A 15-year fixed at 6.68% raises the payment to about $1,665, but total interest drops to about $110,727, compared with about $278,388 over 30 years.
Add property tax, homeowners insurance, mortgage insurance, and any HOA dues for the full monthly number. If it is more than you want to carry, compare a lower price, a larger down payment, a seller-paid rate buydown, or ADFA down payment assistance.
How the loan type changes your White County result
Most online calculators assume a conventional loan with a fixed rate, which can make the number look better or worse than what you would actually get. Here is how the same $210,000 White County home changes by program, using the 7.32% survey average as a stand-in rate. Your actual rate will differ by program and profile.
Conventional
Qualified buyers can put as little as 3% down on a one-unit primary home, which is $6,300 on $210,000 (Fannie Mae eligibility matrix). Below 20% down you pay private mortgage insurance, and you can ask to cancel it once the balance reaches 80% of the original value (CFPB on PMI). PMI is priced by credit score and down payment, so add it as a separate line in the calculator rather than guessing.
FHA
FHA requires 3.5% down with a 580 or higher score (HUD FHA overview). It also adds two insurance costs a basic calculator often skips: an upfront premium of 1.75% that is usually financed into the loan, and an annual premium paid monthly. For a base loan of $726,200 or less with more than 95% loan-to-value, the annual rate is 0.55% (HUD Mortgagee Letter 2023-05). On $210,000 with 3.5% down, the base loan is $202,650, the upfront premium adds $3,546, and principal and interest on $206,196 is about $1,416 at 7.32%. The monthly premium adds roughly $93, for about $1,509 before taxes and insurance. The 2026 FHA one-unit limit in White County is $541,287, the national floor, so this price fits with plenty of room.
VA
Eligible veterans and service members can buy with no down payment and no monthly mortgage insurance (VA purchase loans). A one-time funding fee applies unless you are exempt, and for first use with less than 5% down it is 2.15% of the loan (VA funding fee). Financing that fee on $210,000 brings the loan to about $214,515, with principal and interest near $1,474 at 7.32%.
USDA
USDA guaranteed loans allow no down payment in eligible rural areas for households under the income limits (USDA guaranteed loans). The 2020 Census counted the county as 44.1% urban and 55.9% rural, so USDA is a real question here, but eligibility is decided address by address. Check any home you are serious about instead of assuming. Check an address on the USDA eligibility map before you count on it.
The right program is often a question of credit, down payment, and eligibility rather than price, because a $210,000 home sits well below the FHA limit and the conforming limit. The program with the lowest payment is not always the cheapest over time, since mortgage insurance, the VA funding fee, and rate differences all count. We run the options side by side so you can compare them on one page.
ADFA programs and down payment help
The Arkansas Development Finance Authority (ADFA) offers home loans and down payment assistance through participating lenders. Its guidelines, revised in June 2026, describe these options (ADFA program guidelines):
- Move-Up. No first-time buyer requirement, a qualifying income limit of $142,000, and a minimum median credit score of 640 (ADFA Move-Up).
- Down payment assistance. From $1,000 up to $15,000 as a second mortgage repaid over 10 years at the same rate as the first mortgage. The maximum debt-to-income ratio is 45%, including the assistance payment (ADFA DPA).
- StartSmart. Normally for first-time buyers, but the first-time buyer requirement does not apply in White County, a federally targeted county. A $500,000 purchase price limit, a 640 minimum credit score, primary residence use, and a county income limit still apply.
Because ADFA assistance is repayable, add its monthly payment to the estimate. A $10,000 assistance loan over 10 years adds about $118 a month at 7.32%, or about $114 at the 6.50% StartSmart government rate on ADFA's October 20, 2026 rate table (ADFA rates table). See our first-time home buyer guide for more on how assistance fits with FHA and conventional loans.
White County is one of the 30 federally targeted counties named on ADFA's StartSmart page, which is why the first-time buyer rule is waived here. The 2026 StartSmart income limit for White County is $99,960 for one or two people and $116,620 for three or more (ADFA StartSmart). StartSmart also asks for a 640 minimum credit score, a purchase price of $500,000 or less, and use of the home as your primary residence. If you own a home today, tell us at the start and we can check whether your income and the home you have in mind fit.
Arkansas costs to plan for
- Property tax. Arkansas assesses homes at 20% of market value and applies local millage rates, which differ by city and school district. Budget with the actual tax bill for the address.
- Homestead credit. Owner-occupants can claim a credit once the home is their primary residence. A former rental will not have carried it, so the seller's bill may not match yours. See the next section.
- Homeowners insurance. Ask about wind and hail deductibles, and get quotes before you are under contract, since premiums count in your debt-to-income ratio (CFPB on DTI).
- Flood. Homes near creeks and on low ground deserve a flood zone check. Redfin's climate data puts about 8% of White County properties at severe flood risk (Redfin White County data). Ask about flood insurance, which can be required and changes your payment (FEMA flood insurance).
- Wildfire and other risks. Redfin's climate data also lists about 94% of White County properties with some wildfire risk over the next 30 years. That is nearly every property in the county, and 55.9% of residents lived in rural areas in the 2020 Census, so get the homeowners insurance quote early, especially on a rural address and ask your insurer what applies to it.
- School district. The tax bill depends on both the city and the school district the address falls in, because millage differs by city and school district. Ask for the bill on the exact home.
- Closing costs. Your Loan Estimate itemizes lender, title, and prepaid costs, and a seller credit can offset some of them.
Arkansas property tax relief
Arkansas gives owner-occupied homes a homestead property tax credit. The Department of Finance and Administration says the credit is up to $500 and is increasing to up to $600 beginning with 2026 tax bills. Amendment 79 also limits how much the assessed value of a homestead can rise, to 5% a year, and homeowners who are 65 or older or disabled can have their assessed value frozen (Arkansas DFA property tax relief). You claim the credit with the White County assessor once the home is your primary residence.
For the calculator, start with the seller's latest bill and subtract nothing until you know whether the seller already had the credit or a freeze. A home owned for many years by a senior can show a frozen bill that resets when you buy. Millage rates differ by city and school district inside the county, so ask for the tax bill on the exact address you are considering. With 32.5% of occupied homes rented, the home you are buying may have been a rental, and a rental will not have carried the homestead credit, so your bill after you claim it can differ from the seller's.
How a White County purchase works with Summit
These are the steps from a first estimate to closing. The order is the same wherever in the county the home is.
- Run a few scenarios in the calculator. Try two prices, two down payments, and both a 30-year and 15-year term so you know your range.
- Get preapproved. A preapproval means a lender checked your credit, income, and assets. The CFPB points out that lenders use the terms prequalification and preapproval differently, so ask what was verified (CFPB comparison). Several mortgage credit checks within 45 days count as one inquiry for most scoring models, so shopping does not hurt your score more than once (CFPB on credit checks).
- Compare Loan Estimates. Lenders must send a Loan Estimate within three business days of your application, and the standard format makes side-by-side comparison easy (CFPB on Loan Estimates).
- Watch your debt-to-income ratio. Lenders compare your monthly debts, including the new payment, to gross monthly income (CFPB on DTI). A payment that fits your budget can still be too high for a program limit, or the reverse.
- Check the final numbers. Your Closing Disclosure arrives at least three business days before closing. Compare it to your Loan Estimate line by line (CFPB on Closing Disclosures).
A few details are specific to this area. With more than half the county rural, check USDA eligibility on the exact address and get insurance quotes early on a home outside town. Check the flood zone on a home near a creek or on low ground, since it can change insurance and your payment. Millage differs by city and school district, so ask for the tax bill on the exact address. If you are buying a former rental, ask for the tax bill with and without the homestead credit. The CFPB's free buying guide is a good companion to the process (CFPB Buying a House).
Where we help buyers nearby
We work with buyers throughout White County, including Searcy, Beebe, Bald Knob, Bradford, Judsonia, Kensett, McRae, Pangburn, and the smaller towns around them. The 2020 Census counted the county as 44.1% urban and 55.9% rural, so taxes, insurance, flood zone status, and USDA eligibility can change from one address to the next. Run the numbers for the area you are shopping.
Compare nearby areas. Nearby mortgage calculators: Beebe, Bald Knob, Bradford, ZIP 72012 (Beebe), and ZIP 72010 (Bald Knob). Neighboring counties: Independence County, Jackson County, Woodruff County, Prairie County, Lonoke County, Faulkner County, and Cleburne County. Or use the statewide Arkansas mortgage calculator.
Related pages
Start with the White County preapproval to find your price range, or test payments in the White County mortgage calculator. The Arkansas purchase loans page covers the whole state, and the Arkansas preapproval guide explains what we verify. First-time buyers can read the Arkansas first-time home buyer guide. If you already own a home, see refinance options. Building instead? See construction loans. Homeowners 62 and older can read about reverse mortgages. The main loan calculator page links to calculators for every state we serve.
Sources
- Wikipedia, White County, Arkansas
- Redfin, White County, AR housing market
- Freddie Mac Primary Mortgage Market Survey, October 22, 2026
- Freddie Mac PMMS archive
- FRED, 30-Year Fixed Rate Mortgage Average
- FHFA, 2026 conforming loan limits
- FHFA 2026 county loan limit list
- HUD No. 25-145, 2026 FHA loan limits
- HUD FHA mortgage limits lookup
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- HUD, Let FHA loans help you
- HUD Mortgagee Letter 2023-05, FHA annual MIP (PDF)
- VA purchase loan
- VA funding fee and closing costs
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- ADFA single-family program guidelines, rev. June 2026 (PDF)
- ADFA Move-Up loan program
- ADFA down payment assistance program
- ADFA homeownership programs and current rates (table updated October 20, 2026)
- ADFA StartSmart first-time home buyer program
- CFPB, debt-to-income ratio
- FEMA, flood insurance
- Arkansas DFA, property tax relief
- CFPB, prequalification vs. preapproval
- CFPB, when a lender checks your credit
- CFPB, What is a Loan Estimate?
- CFPB, What is a Closing Disclosure?
- CFPB, Buying a House
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.
Related Articles
10 Things Every First-Time Home Buyer Should Know
Buy Smart, Live Happy: The Essential Guide to Buying Your First Home
Move into Your Dream Home with 0% Down Payment
Why 0% Down is a Game-Changer for Homebuyers
Arkansas Mortgage Payments at 7.40%: Bentonville vs. Little Rock vs. Jonesboro (Oct 2026)
Freddie Mac's 30-year average held at 7.40% on Oct. 15, but an Arkansas payment depends on much more than the rate. Here is the full monthly cost of typical homes in Bentonville, Fayetteville, Little Rock, and Jonesboro, how school district millage and the new $675 homestead credit change it, and where ADFA down payment help fits.Frequently Asked Questions
Everything you need to know about home mortgage loans in White County, ArkansasYour ideal loan depends on several factors like your financial situation, long term goals, and risk tolerance. Fixed rate mortgages offer stability, while adjustable rate loans may save you money initially. Government-backed options can be great for those with lower credit scores. At Summit Lending, we’ll guide you through the options to find a perfect fit.