Mortgage Loans Tailored by a Broker Who Compares Options
Mortgage loans compared by a broker, not pushed by a single lender menu
Summit Lending LLC (NMLS 2394434) is a mortgage broker. That means we shop loan programs across lenders instead of steering every borrower into one in-house product. Whether you are buying, refinancing, building, unlocking later-life equity, or financing investment property, the first job is the same: match the goal to a few workable structures and show the payment and cash to close.
We help clients in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona from 4542 W 14800 N, Garland, UT 84312. Call 385-200-1470 or email [email protected].
Core mortgage options
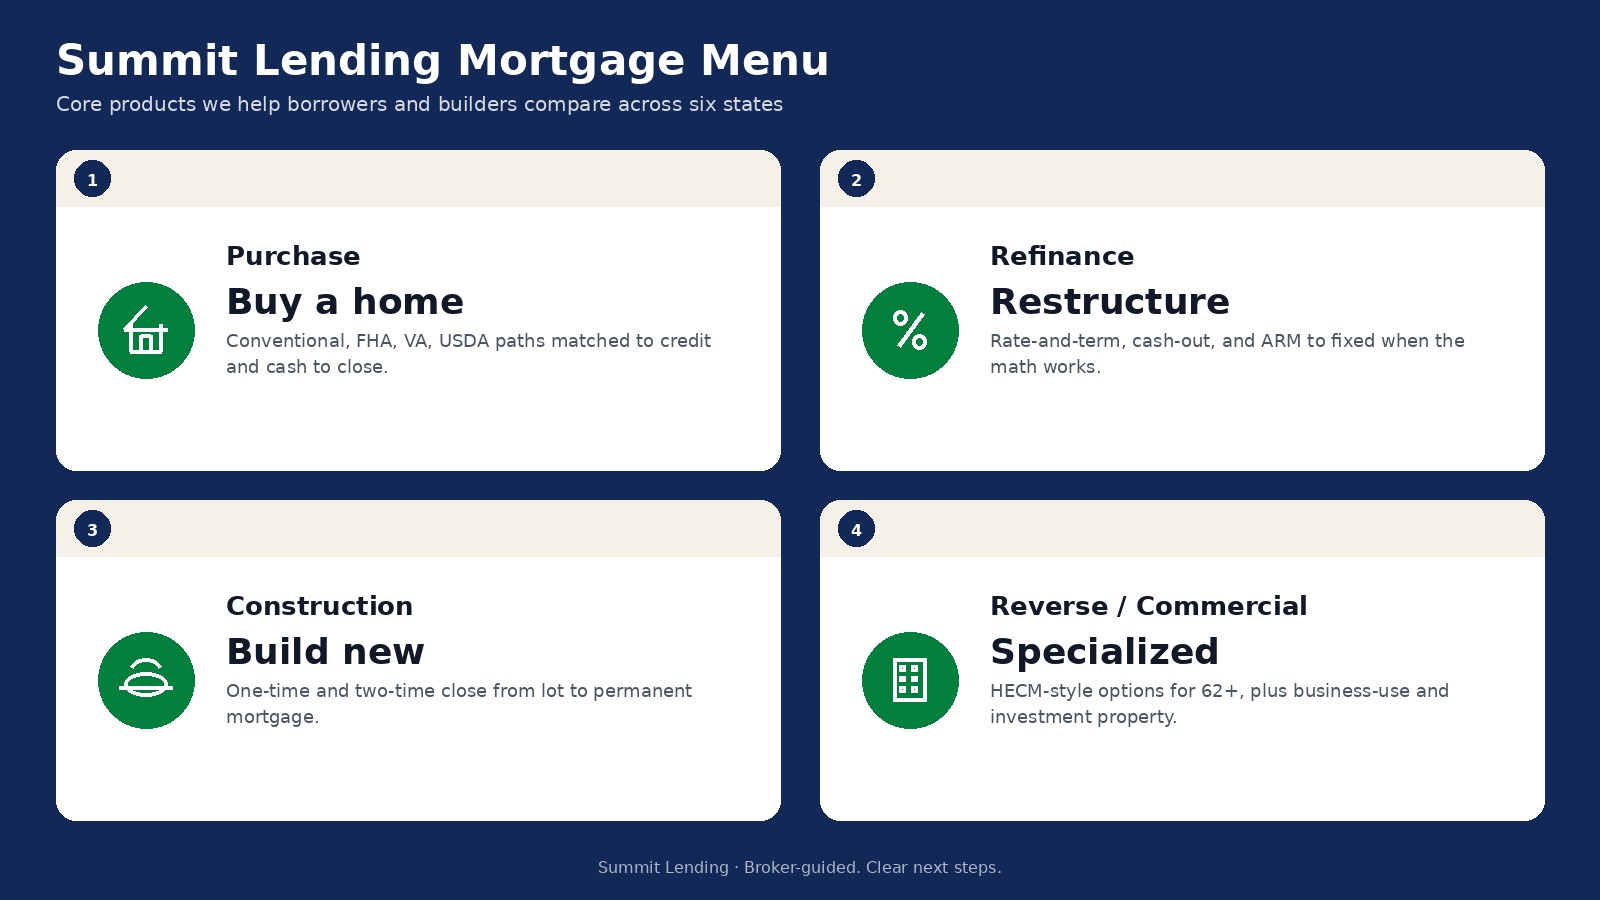
- Purchase loans for primary homes, many second homes, and some investment purchases using Conventional, FHA, VA, or USDA structures when you qualify.
- Refinance for rate-and-term savings, shorter terms, ARM-to-fixed moves, and cash-out when the break-even makes sense.
- Construction loans with one-time and two-time close paths from lot and plans to a permanent mortgage. Builders should also see the Builder Portal.
- Reverse mortgages (HECM-style options for homeowners 62+) when staying in the home is the priority.
- Commercial loans for income property, mixed-use, and owner-user business real estate.
- First-time home buyer guidance and preapproval so offers are backed by verified numbers.
Fall 2026 market numbers worth knowing
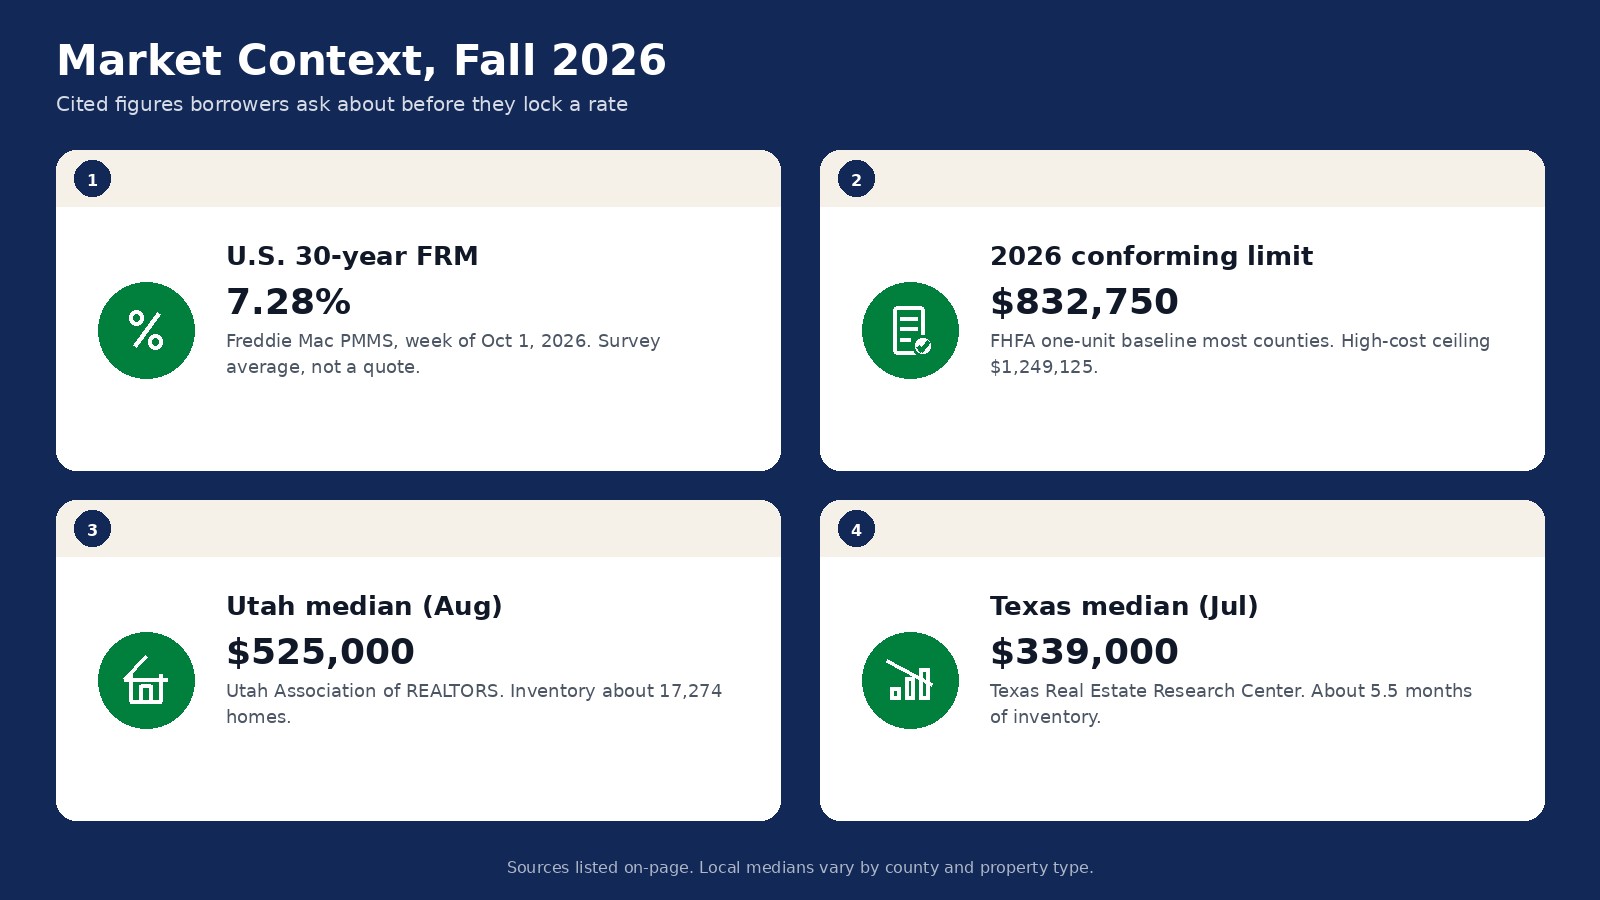
Freddie Mac's Primary Mortgage Market Survey averaged 7.28% on the 30-year fixed for the week of October 1, 2026 (15-year 6.60%; year-ago 30-year 6.34%). Those are national survey averages for well-qualified borrowers putting 20% down. They are useful for modeling and are not Summit Lending quotes.
FHFA set the 2026 one-unit conforming loan limit at $832,750 in most counties, with a high-cost ceiling of $1,249,125. Utah Association of REALTORS reported a statewide median sales price of $525,000 in August 2026 with about 17,274 homes in inventory. The Texas Real Estate Research Center reported a $339,000 statewide median in July 2026. Redfin put Idaho's August 2026 statewide median near $512,859. Local county medians can differ sharply from the state figure.
State mortgage hubs
- Utah mortgages with purchase, refinance, construction, reverse, and commercial child pages
- Texas mortgages covering Houston, Dallas-Fort Worth, Austin, San Antonio, and statewide counties
- Idaho mortgages for the Treasure Valley, East Idaho, and North Idaho
- Wyoming mortgages for statewide purchase, refinance, reverse, and commercial needs
Popular county starting points include Salt Lake County, Utah County, Harris County, Dallas County, Travis County, Ada County, and Laramie County.
How working with Summit Lending feels day to day
- Clarify the goal. Buy, refinance, build, invest, or stay in place later in life.
- Compare a short list. Two or three real programs beat a dozen theoretical ones.
- Verify early. Income, assets, and credit checked before you lean on a letter.
- Close with fewer surprises. Appraisal, title, insurance, and underwriting coordinated against the numbers we already modeled.
Run scenarios in the loan calculator, then talk with us before you lock anything in. Arkansas and Arizona borrowers are welcome even when a dedicated state hub page is still catching up.
Why borrowers use a broker
A single-lender retail shop can only sell what it holds. A broker can compare overlays: credit floors, reserve requirements, condo guidelines, manufactured housing rules, and investor caps that differ from one investor to the next. That does not guarantee a better rate every day. It does mean more ways to solve an awkward file without starting over at a new institution.
You still get a clear explanation of fees, and you still choose whether to proceed. Our role is to make the tradeoffs visible.
Documents that speed every file
Across purchase, refinance, and construction, the same habits save days: complete applications, readable PDFs, documented large deposits, and quick answers when underwriting asks a follow-up. Self-employed borrowers should expect business returns, K-1s when relevant, and a year-to-date profit-and-loss statement. W-2 employees usually need less paper but still need consistent paystubs and asset statements.
Rate quotes versus survey averages
Weekly Freddie Mac averages describe a national sample of well-qualified purchase borrowers. Your quote can be higher or lower based on credit, loan type, occupancy, points, and lock period. We will not invent a teaser rate to win a call. We will show a few executable options and what would change the price.
Information on this page is for general education. It is not a commitment to lend. Loan availability, terms, and pricing depend on your credit, income, assets, property, and lender overlays. Summit Lending LLC, NMLS 2394434.
Frequently Asked Questions
Everything you need to know about home mortgage loansYour ideal loan depends on several factors like your financial situation, long term goals, and risk tolerance. Fixed rate mortgages offer stability, while adjustable rate loans may save you money initially. Government-backed options can be great for those with lower credit scores. At Summit Lending, we’ll guide you through the options to find a perfect fit.
Related Articles
Top Reasons to Refinance Your Mortgage and Why It Works
A 2026 refinance guide aligned to 6% normalization: when payment relief, ARM-to-fixed, PMI removal, cash-out, or term changes make sense, plus break-even math and when to wait.
Don't Let These Homebuying Myths Keep You from Your Dream Home
Navigating the Homebuying Process with Summit Lending: Debunking Common Myths.
Mortgage Rates Above 7%: What Utah Buyers Should Do Now (Sept 2026)
Freddie Mac’s 30-year fixed averaged 7.03% the week of September 24, 2026, after the Fed’s mid-month hike. Here is how Utah buyers and homeowners can plan payments, use improving Salt Lake County inventory, and keep the 6% normalization mindset honest when headlines sit above 7%.
Utah Seller Concessions and Rate Buydowns in a Higher-Inventory Fall Market (Oct 2026)
With Salt Lake County at 4.2 months of supply and sellers offering more credits nationally (Redfin via Deseret News, Sept 22, 2026), Utah buyers can negotiate closing cost help and rate buydowns on resale homes. Here is how to structure the ask without guessing.
Texas Property Taxes and Home Insurance: Budgeting the Real Mortgage Payment (Oct 2026)
Texas property tax bills go out in October, Harris and Dallas counties just raised rates, and TDI shows insurers filing for lower rates on average. Here is how the $140,000 homestead exemption, escrow, and insurance shape the payment you will actually make.
ARM or Fixed at 7.28%? An Idaho Homebuyer's Guide (October 2026)
Freddie Mac's 30-year fixed hit 7.28% on Oct. 1, 2026, and ARMs climbed to 10.3% of applications. Here is how a 5-year ARM really compares with a fixed loan on a $595,000 Ada County home, including resets, caps, and the qualifying rule most buyers miss.