Get Preapproved in Craighead County
Your Guide To Home Loan Pre Approval in Craighead County, Arkansas
What Are Mortgage Loan Pre-Approvals?
A home loan pre-approval serves as a stamp of approval from lenders confirming your financial readiness to buy a home. Before you get pre-approved, the lender will evaluate your debt-to-income ratio and creditworthiness. Upon approval, you will receive a statement that serves as their conditional commitment to lending you money to buy your home while also showing how much they are willing to give you.
Pre-approval Vs Prequalification - What's The Difference?
A prequalification gives you a rough idea of how much you can borrow based on what you tell the lender about your finances. Pre-approval, on the other hand, means the lender has checked and confirmed your financial information, giving you a conditional thumbs-up for a specific loan amount.
When Should You Get Pre-Approved?
You can get approved for a mortgage in as little as one business day if your paperwork is in order, while other lenders may take longer. Pre-approvals are usually valid for 90 days. However, some lenders may keep it valid for 30 or 60 days.
We recommend you start before looking for a home to ensure you can make an offer on the home you like on time.
Do Pre-approvals Affect Your Credit Score?
Before you get preapproved for a mortgage, lenders carry out a hard pull of your credit to check your score, temporarily lowering it by a few points. However, you will have a 45-day window in which multiple credit score inquiries will be considered on your credit report. Are you worried about denial? You can ask the lender why your home loan pre approval was denied and address the issue.
However, when you work with mortgage loan specialists like us, we ensure you apply for the loans that best align with your financial situation, maximizing your chances of approval.
Pre-Approval Costs in Craighead County, Arkansas
You may be wondering if you need to pay money to get pre-approved for a mortgage loan in Craighead County, Arkansas. That depends on the lender you choose to work with. Some do it for free, while others demand a non-refundable application fee you must pay upfront, whether you get approved or not.
Craighead County mortgage preapproval: know your number before you make an offer
A preapproval tells you, and a seller, how much a lender is prepared to lend after looking at your actual credit, income, and assets. In Craighead County it matters for a few practical reasons. Homes are selling faster than they were a year ago. A good share of the county sits outside Jonesboro city limits, where wells, septic systems, and low-lying ground can affect the loan. And Arkansas has state programs that only work if your loan is set up for them from the start. Summit Lending LLC (NMLS 2394434) is a mortgage broker based in Garland, Utah and licensed in Arkansas. We compare loans from multiple wholesale lenders, so your preapproval reflects a loan you can actually close, at a price you have compared.
Want to see the payment first? Try the Craighead County mortgage calculator, then come back here. When you are ready to compare loan types in more depth, read about Craighead County purchase loans.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
Why preapproval matters in Craighead County right now
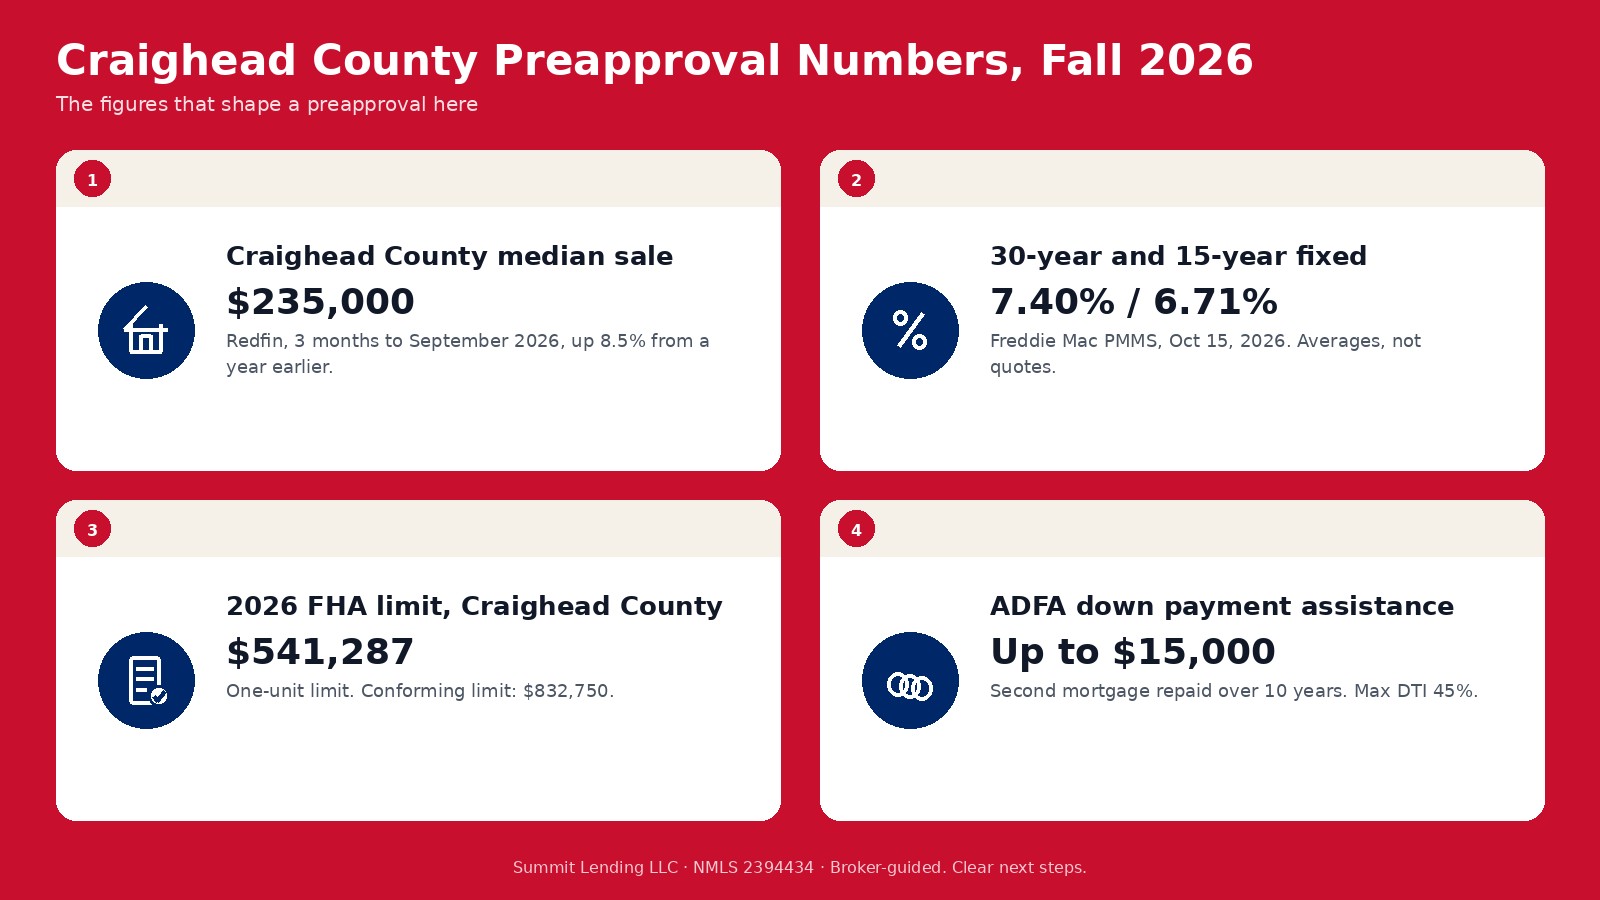
Redfin put the Craighead County median sale price at about $235,000 for the three months ending September 2026, up 8.5% from a year earlier. Homes took a median of about 50 days to sell, compared with 64 days a year earlier, and they sold for about 97.0% of list price on average. More homes sold in September than in the same month a year earlier (Redfin Craighead County data).
What that means for a buyer: homes are moving, but sellers are still negotiating, and a price near 97% of list leaves some room. A seller comparing two offers will look hard at which buyer is more likely to close, and a verified preapproval answers that question before it is asked. That is true near Arkansas State University in Jonesboro, where some buyers are families buying for a student and some are investors. It is just as true in Bono, Brookland, Lake City, Monette, Caraway, and Bay, where there may be fewer listings to choose from and less time to line up financing once you find the right one.
Rates matter too. Freddie Mac's survey put the average 30-year fixed rate at 7.40% on October 15, 2026, unchanged from a week earlier and up from 6.27% a year ago. The 15-year average was 6.71% (Freddie Mac PMMS). Those are national averages for strong-credit borrowers with a large down payment, not a quote. Your own rate depends on your credit, down payment, loan type, and property. A preapproval built on current pricing keeps you shopping in the right range.
Prequalification versus preapproval
The CFPB notes that lenders do not use these two terms the same way. A prequalification can be based only on what you tell the lender, while a preapproval may involve a full review of documents and credit. What matters is what was verified (CFPB comparison). At Summit, a preapproval means we have pulled your credit and reviewed your income and asset documents.
A prequalification is a fine starting point while you are browsing listings and learning what you can afford. Once you are touring homes or talking to an agent about offers, upgrade to a preapproval. It takes more of your time up front, and it saves time later.
What to gather for a Craighead County preapproval
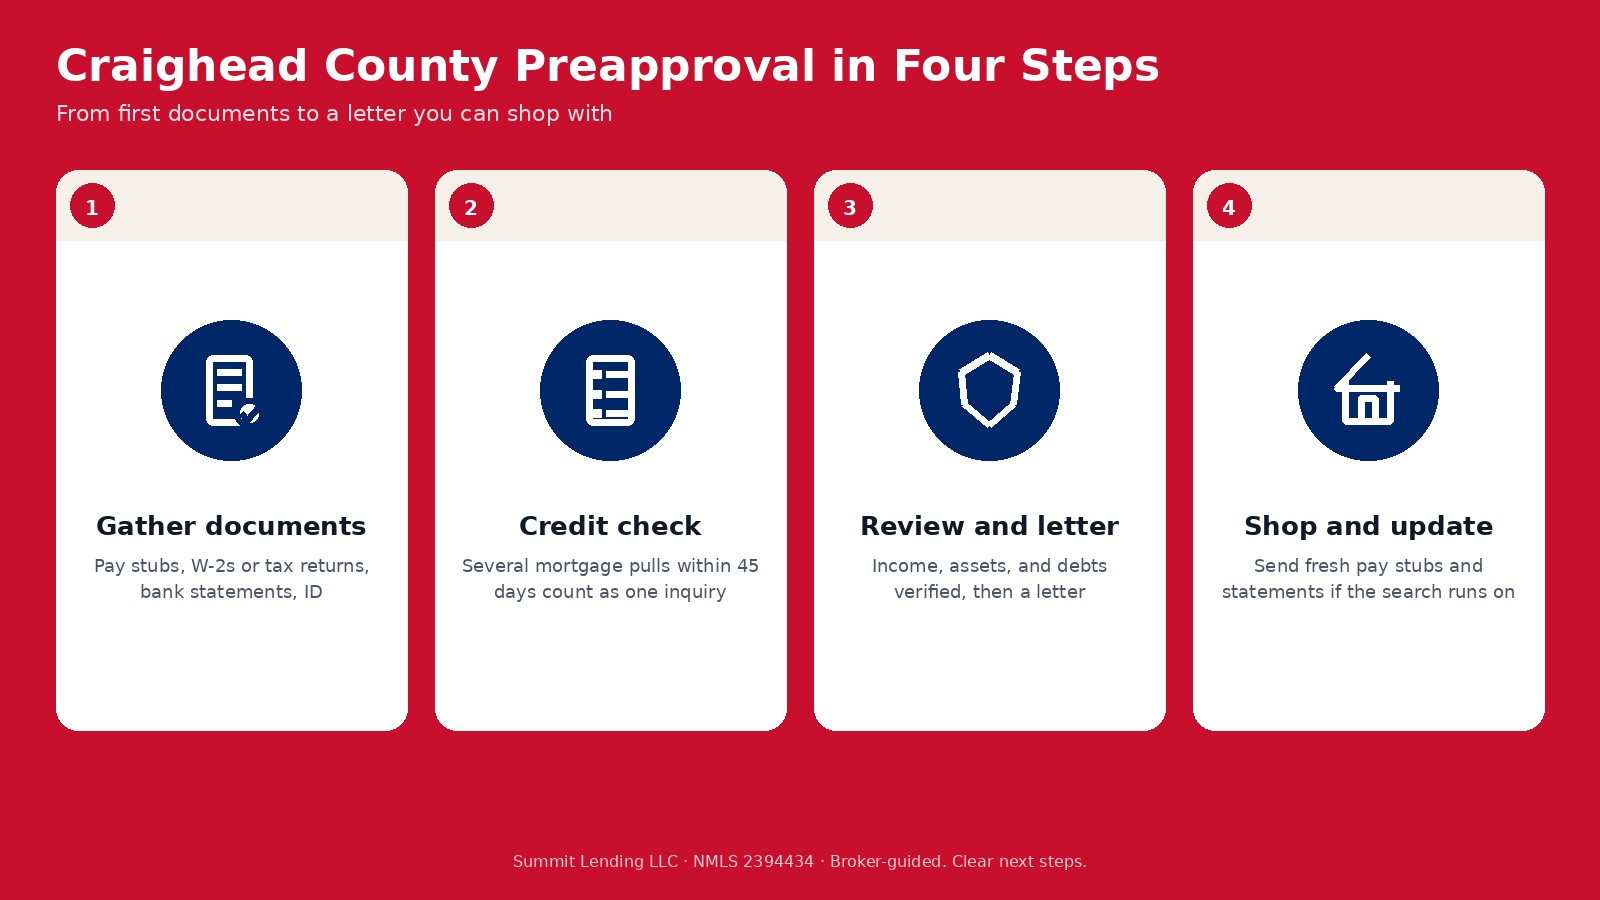
- Income. Recent pay stubs and W-2s. If part of your income comes from farming, self-employment, or commissions, expect to provide tax returns, often for two years, so the lender can see how the income has held up.
- Assets. Recent bank statements, plus any retirement or investment statements you will use for the down payment, closing costs, or reserves. If family is helping, a signed gift letter.
- Credit. Your authorization to pull credit, plus a short note about anything unusual, such as a past late payment or a gap in work.
- Identification and history. A photo ID and two years of address and employment history.
- Program extras. For a VA loan, your Certificate of Eligibility (VA eligibility). For USDA, tell us who will live in the home, because the income limits apply to the household. For ADFA assistance, tell us at the start so we can set the file up for it.
What lenders actually check
- Credit. Your score affects both approval and price. FHA allows 3.5% down with a score of 580 or higher (HUD FHA overview), and ADFA's Move-Up program asks for a minimum median credit score of 640 (ADFA Move-Up). Several mortgage credit checks within a 45-day window generally count as one inquiry for scoring, so comparing lenders will not hurt you more than once (CFPB on credit checks).
- Debt-to-income ratio. Your monthly debts, including the new housing payment, divided by your gross monthly income (CFPB on DTI). The example below shows how this works.
- Down payment and reserves. We confirm the money is yours, where it came from, and what is left after closing.
- The property. Outside town, a home may use a well or septic system, and some parcels sit in low-lying areas near the Cache and St. Francis rivers. Loan programs can have their own property requirements, and a flood zone can add an insurance cost that changes your payment (FEMA flood insurance). Tell us the area you are shopping so we plan for it.
- Program limits. The 2026 FHA one-unit limit in Craighead County (Jonesboro metro) is $541,287, the national floor (HUD lookup; HUD announcement). The 2026 conforming limit is $832,750 (FHFA). With a median price near $235,000, most local buyers are far below both.
An illustration of how debt-to-income limits the payment
Say a buyer earns $5,000 a month before taxes and has $400 a month in other debts, such as a car payment and a credit card minimum. ADFA's maximum debt-to-income ratio is 45%, including the assistance payment (ADFA down payment assistance). At 45%, total monthly obligations could reach $2,250 (0.45 x $5,000). Subtract the $400 of other debts and the total housing payment could be up to about $1,850.
That $1,850 is not just principal and interest. It also has to cover property tax, homeowners insurance, mortgage insurance if it applies, and any HOA dues. This is an illustration, not a promise. Program limits vary, and lenders also look at credit, reserves, and the property. If your debts are higher, the number shrinks, and paying off a small balance before applying can sometimes help more than a larger down payment.
Loan options we preapprove Craighead County buyers for
- Conventional. As little as 3% down for qualified buyers on a one-unit primary home (Fannie Mae eligibility matrix). Private mortgage insurance applies below 20% down, and you can ask to cancel it once the balance reaches 80% of the original value (CFPB on PMI).
- FHA. 3.5% down with a 580 or higher score, plus an upfront premium of 1.75% that is usually financed and an annual premium. The annual rate is 0.55% for a base loan of $726,200 or less with more than 95% loan-to-value (HUD Mortgagee Letter 2023-05).
- VA. No down payment and no monthly mortgage insurance for eligible borrowers (VA purchase loans). A funding fee applies unless you are exempt, and for first use with less than 5% down it is 2.15%. Veterans receiving service-connected disability compensation are exempt (VA funding fee).
- USDA. No down payment in eligible rural areas for households under the income limits (USDA guaranteed loans). Jonesboro itself is generally not eligible, but many smaller towns and rural parts of the county can be. Check the address on the USDA eligibility map before you count on it.
- Jumbo. Only above $832,750. It rarely comes up at Craighead County prices, but we can preapprove for it if you are looking at larger acreage or a custom home.
If you plan to use Arkansas down payment help, say so at the start. ADFA's down payment assistance runs from $1,000 up to $15,000 as a second mortgage repaid over 10 years at the same rate as the first mortgage (ADFA down payment assistance). Its Move-Up program has no first-time buyer requirement but sets an income limit of $142,000 and the 640 median credit score noted above. StartSmart is for buyers who have not owned a home in the past three years, with a $500,000 purchase price limit. ADFA revised its guidelines in June 2026 (ADFA program guidelines). Because the assistance is repayable, we add its payment to your numbers. A $10,000 assistance loan over 10 years at 7.40% adds about $118 a month. Our first-time home buyer guide explains how assistance fits with FHA and conventional loans.
How preapproval works with Summit
- A short conversation. Your goals, timeline, price range, and which part of the county you are looking at. A buyer eyeing a home in Jonesboro and one eyeing acreage near Lake City may need different loan types.
- Application and documents. You upload the items above through a secure link. If something is missing, we tell you exactly what and why.
- Credit and review. We pull credit, review income and assets, and look at the file with more than one wholesale lender in mind, so we know which lender fits best.
- Your letter. You receive a preapproval letter to attach to offers. We can tailor the amount for each offer so you do not show a seller more than you need to.
- When you find a home. Once you apply for a specific property, your Loan Estimate arrives within three business days (CFPB on Loan Estimates). Your Closing Disclosure comes at least three business days before signing (CFPB on Closing Disclosures). For the full path from contract to keys, see our Craighead County purchase loans page.
Keep your preapproval strong
- Do not open new credit, or finance a vehicle or furniture, before closing.
- Document large deposits, and tell us before you move money between accounts.
- Tell us right away if your job or income changes.
- If your search runs on, expect to send updated pay stubs and statements so the letter stays current.
- Get homeowners insurance quotes early. Spring storms are a fact of life in northeast Arkansas, so ask about wind and hail deductibles, and check flood zone status on any home near a creek or river. Premiums feed into your debt-to-income ratio.
- If you are buying a former rental, remember it will not have carried the homestead tax credit. Ask us to estimate the tax bill with and without it.
Preapproval for buyers across Craighead County and nearby
We preapprove buyers throughout Craighead County, including Jonesboro, Bono, Brookland, Lake City, Monette, Caraway, and Bay. Craighead County is one of the few Arkansas counties with two county seats, Jonesboro and Lake City, so the county offices you deal with after closing may depend on where the home is.
Planning a move across the line? Nearby mortgage calculators: Monette, Greene County, Paragould, Poinsett County, Mississippi County, Lawrence County, and Jackson County. Elsewhere in Arkansas: Little Rock, Pulaski County, Benton County, and North Little Rock. Or use the statewide Arkansas mortgage calculator.
Related pages
Read about Craighead County purchase loans, or start with the Craighead County mortgage calculator to test a price range. Our preapproval overview and home purchase loans pages cover every state we serve. First-time buyers can read the first-time home buyer guide. If you already own, see refinance options. Planning to build? See construction loans. Homeowners 62 and older can read about reverse mortgages. The main loan calculator page links to calculators for every state we serve.
Sources
- Redfin, Craighead County, AR housing market
- Freddie Mac Primary Mortgage Market Survey, October 15, 2026
- CFPB, prequalification vs. preapproval
- VA home loan eligibility
- HUD, Let FHA loans help you
- ADFA Move-Up loan program
- CFPB, when a lender checks your credit
- CFPB, debt-to-income ratio
- FEMA, flood insurance
- HUD FHA mortgage limits lookup
- HUD No. 25-145, 2026 FHA loan limits
- FHFA, 2026 conforming loan limits
- ADFA down payment assistance program
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- HUD Mortgagee Letter 2023-05, FHA annual MIP (PDF)
- VA purchase loan
- VA funding fee and closing costs
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- ADFA single-family program guidelines, rev. June 2026 (PDF)
- CFPB, What is a Loan Estimate?
- CFPB, What is a Closing Disclosure?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.